Market Overview and Industry Significance of the Submerged Arc Furnace Market
The Submerged Arc Furnace Market is valued at $2.26 Billion in 2026, underpinning heavy metallurgical production by utilizing high-current arcs buried beneath charge materials. These systems are indispensable for reducing quartz and metal oxides into ferroalloys and silicon metal, acting as the thermal backbone for global infrastructure and specialty steel manufacturing.
Structural Growth Drivers, Restraints, and Opportunities in the Submerged Arc Furnace Market
Our analysis indicates that surging demand for specialty alloy steels and green energy infrastructure drives market expansion. Conversely, stringent carbon emissions regulations from bodies like the EPA and EU pose operational restraints, while opportunities thrive in developing energy-efficient configurations for continuous smelting operations.
Emerging Trends and Growth Patterns Shaping Submerged Arc Furnace Market Industry Trends
The industry trends toward decarbonization have accelerated the adoption of closed-top furnace designs and waste-heat recovery systems. Industrial consumers prioritize ultra-high power capacity units to maximize throughput, while advanced automation minimizes electrode breakage and optimizes energy consumption during continuous smelting cycles.
Pandemic Aftermath: COVID-19 Impact and Recovery Trajectory
Supply chain disruptions and localized lockdowns temporarily stalled heavy equipment manufacturing and port logistics globally. However, post-pandemic stimulus packages targeting renewable energy infrastructure triggered a robust rebound, accelerating demand for silicon solar-grade feedstocks and specialized ferroalloys produced via advanced smelting technology.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is consolidated among engineering heavyweights like SMS group GmbH, Metso Corporation, and Danieli & C Officine Meccaniche S.p.A. These market leaders leverage proprietary electrode control algorithms and turnkey plant execution capabilities to outpace regional fabricators, capturing high-margin contracts for large-scale industrial installations.
Executive Summary of the Submerged Arc Furnace Market
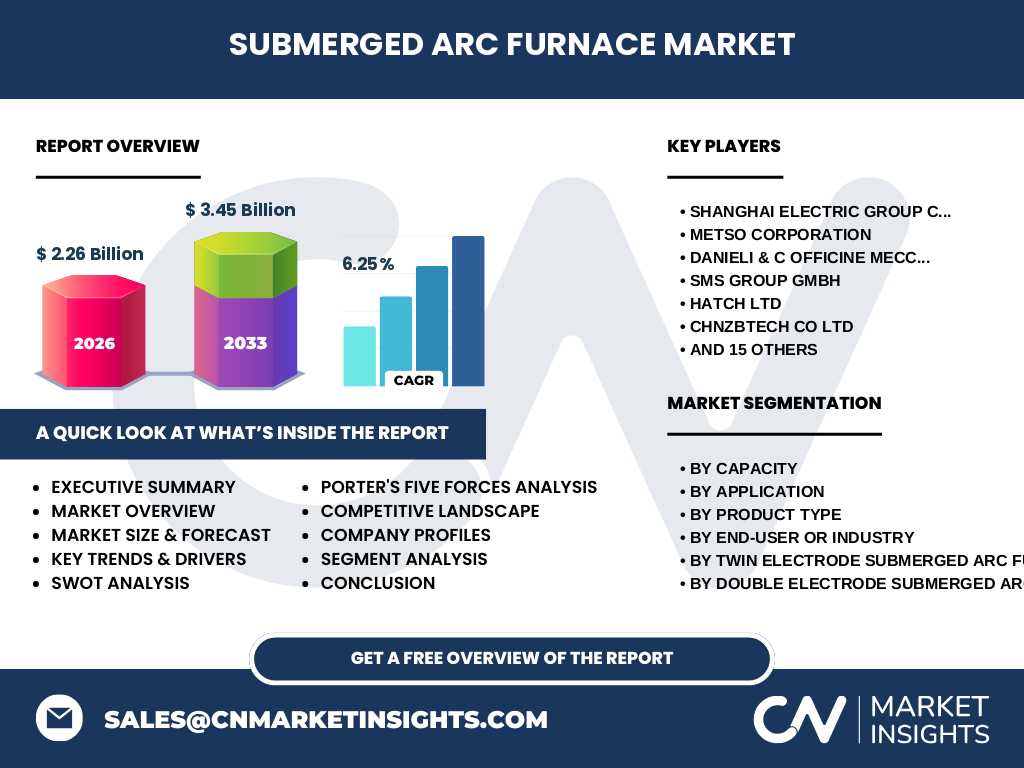
Proprietary research confirms the Submerged Arc Furnace Market is on a definitive upward trajectory, scaling from $2.26 Billion in 2026 to reach $3.45 Billion by 2033 at a CAGR of 6.25%. Strategic consolidation, technological shifts toward energy efficiency, and expanding metallurgical applications anchor this strong valuation.
Market Forecast and Valuation Trajectory (2027-2033)
Based on our econometric modeling, the market will expand steadily at a 6.25% CAGR over the forecast period, culminating in a valuation of $3.45 Billion by 2033. This sustained momentum reflects robust capital expenditure in emerging economies upgrading their domestic steelmaking and chemical processing capacities.
Comprehensive Segmentation Analysis of the Submerged Arc Furnace Market
Our research categorizes the sector by capacity, application, product type, and end-user. Capacity tiers range from less than 100 tonnes to above 500 tonnes, servicing ferroalloy, silicon metal, and calcium carbide production across metallurgical, chemical, and foundry industries utilizing single, double, and twin electrode designs.
Geographic Distribution and Regional Performance
Regional performance is heavily skewed toward Asia-Pacific, driven by intense steel production and foundry activities in China and India. Meanwhile, European markets focus on retrofitting legacy units for energy efficiency to comply with strict regional carbon taxation and environmental directives.
In-Depth Regional Review and Localized Market Constraints
Asia-Pacific dominates manufacturing output due to abundant raw material access and localized engineering expertise from firms like Xi'an Hani Metallurgy Co Ltd and Shanghai Electric Group Company Limited. Conversely, North American and European operations face stringent grid capacity constraints and high electricity tariffs, favoring automated, energy-optimized furnace models.
Company Profiles and Strategic Positioning
Industry leaders deploy distinct competitive strategies to capture market share. Hatch Ltd and Consarc Engineering Limited focus on custom metallurgical process engineering, whereas Electrotherm India Limited and Inductotherm Group emphasize modular, cost-effective foundry solutions tailored for emerging industrial economies.
Porter's Five Forces Assessment of Competitive Intensity
Bargaining power of suppliers remains moderate due to specialized refractory and electrode material requirements. Rivalry is intense among established global EPC contractors, while the threat of substitutes is low given the unique electrochemical reduction capabilities required for primary silicon and ferroalloy smelting.
SWOT Analysis of the Submerged Arc Furnace Market
Key strengths lie in high thermal efficiency and robust mechanical durability. Weaknesses involve high initial capital expenditure and intensive power consumption. Opportunities abound in green-hydrogen reduction integration, while threats stem from volatile raw material costs for carbon electrodes and silicon ores.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining raw materials like quartz, carbon reductants, and metal ores, progressing through specialized equipment design by firms like SMS group GmbH and Metso Corporation. Fabrication leads to smelter commissioning, ultimately supplying metallurgical, chemical, and casting end-users.
Investment Insights and Strategic Recommendations
High-potential areas include retrofitting existing furnaces with advanced digital twin monitoring and energy recovery systems. Investors should prioritize partnerships with technology providers specializing in continuous operation types and ultra-high power capacity units designed to lower carbon intensity.
Conclusion and Key Industry Takeaways
The Submerged Arc Furnace Market represents a critical pillar of heavy industry, balancing traditional smelting necessity with modern environmental demands. Achieving the projected $3.45 Billion by 2033 valuation requires continuous innovation in energy efficiency and electrode optimization by key market participants.
Research Methodology and Baseline Estimation Techniques
Our market sizing relies on rigorous data triangulation, combining customs export registries for heavy machinery, primary stakeholder interviews with plant operators and EPC contractors, and macroeconomic secondary indicators covering global steel and chemical output to establish reliable baseline estimates.
Scope of the Report and Coverage Parameters
This report encompasses global deployment data for submerged arc furnaces across all major capacity ranges and end-use applications from 2026 to 2033. Limitations include restricted transparency into state-owned smelting operations in select developing regions and proprietary pricing agreements.
Recent Developments, Strategic Partnerships, and Product Launches
Recent strategic moves highlight a surge in R&D partnerships aimed at reducing carbon footprints in ferroalloy production. Market players such as Danieli & C Officine Meccaniche S.p.A. and Hatch Ltd have focused on introducing digital automation suites to enhance process control and thermal efficiency in newly commissioned plants.