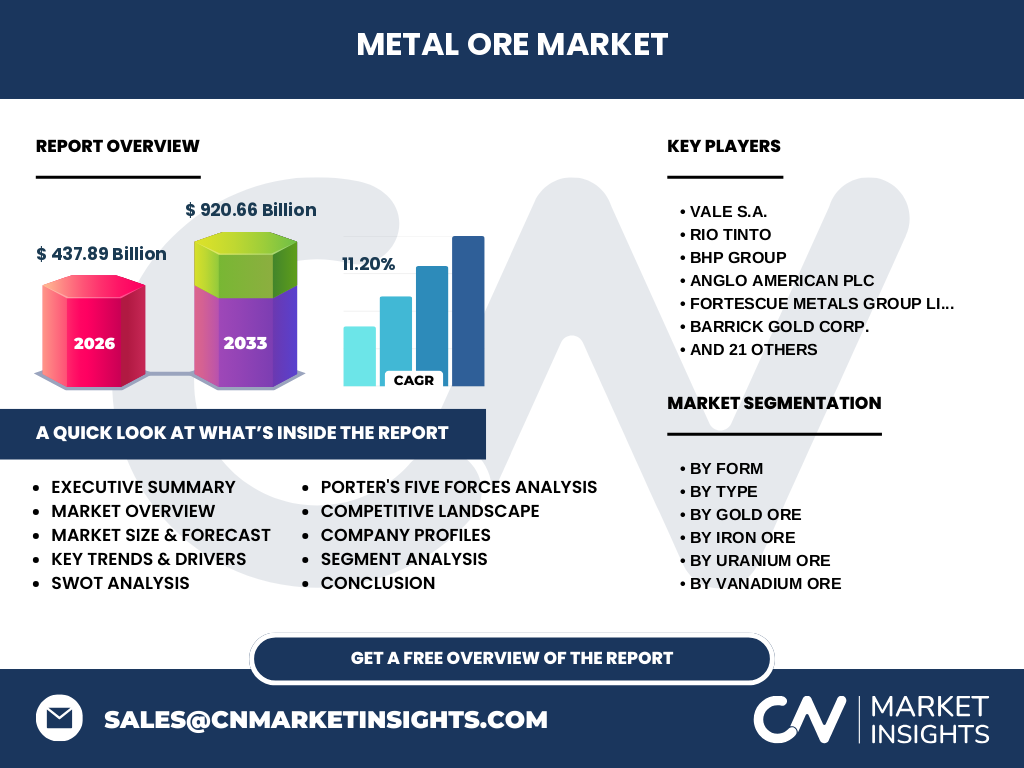
Market overview of the Metal Ore Market
Our analysis indicates that the Metal Ore Market encompasses the extraction, beneficiation, and initial processing of critical raw materials including iron ore, gold ore, uranium ore, and vanadium ore. Valued at $437.89 Billion in 2026, this foundational sector supplies essential feedstocks to global steel mills, precious metals refiners, and nuclear energy providers. Industry significance stems from its direct correlation with heavy industrial manufacturing and infrastructure development worldwide.
What are the primary drivers and restraints shaping the Metal Ore Market?
Growth is primarily accelerated by surging global demand for decarbonization infrastructure, which requires vast quantities of base and precious metals. However, the industry faces severe restraints, including stringent environmental compliance enforced by agencies like the EPA and localized grade-decline in mature deposits. Logistical bottlenecks at critical export terminals in Western Australia and South Africa further constrain operational throughput for major mining houses.
Emerging trends and growth patterns in the Metal Ore Market
The sector is witnessing a decisive pivot toward digitalized, autonomous extraction operations and low-carbon processing technologies. Mining leaders are increasingly adopting automated haulage systems and green hydrogen-powered smelting trials to reduce Scope 1 and Scope 2 emissions. Advanced ore sorting technologies are also gaining traction, allowing operators to process lower-grade hematite and magnetite efficiently without exponentially increasing energy consumption.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain fractures, temporary site suspensions, and acute labor shortages across major extraction hubs in South America and Australia. Despite these initial disruptions, a rapid post-lockdown fiscal stimulus cycle in major economies triggered an unprecedented commodity super-cycle. The recovery trajectory established robust operational resilience, prompting miners to diversify supply chains and heavily invest in remote-operation monitoring capabilities.
Competitive landscape and strategic market dynamics
Market concentration remains moderately high, dominated by multinational mining giants such as Vale S.A., Rio Tinto, and BHP Group, alongside specialized precious metal producers like Barrick Gold Corp. and Newmont Corporation. Strategic dynamics center on mega-mergers, joint ventures in greenfield copper and nickel projects, and aggressive vertical integration to secure long-term offtake agreements with EV battery manufacturers and global steel producers.
Executive summary of the Metal Ore Market
Our comprehensive research projects the Metal Ore Market to expand from a 2026 valuation of $437.89 Billion to an impressive $920.66 Billion by 2033, achieving a robust CAGR of 11.20%. This stellar trajectory is propelled by accelerating global electrification, urbanization in emerging economies, and sustained high-grade resource depletion driving up commodity values.
Market forecast from 2027 to 2033
Driven by compounding industrial demand and tight supply fundamentals, the market will scale rapidly over the forecast window. Our proprietary econometric modeling indicates that the sector will achieve a remarkable 11.20% CAGR, propelling total market revenue from $437.89 Billion in 2026 to $920.66 Billion by 2033. This expansion reflects sustained capital expenditure into both traditional iron ore assets and energy-transition-critical metal deposits.
Segmentation analysis of the Metal Ore Market
The market exhibits complex segmentation: By Form (Sinter Fines, Lumps, Pellets, Other Forms), By Type (Gold Ore, Iron Ore, All Other Metal Ores, Silver Ore, Uranium Ore, Vanadium Ore), By Gold Ore (Primary, Secondary), By Iron Ore (Hematite, Magnetite, Limonite, Siderite), By Uranium Ore (Pitchblende, Uraninite, Coffinite), By Vanadium Ore (Vanadinite, Carnotite), By Organization Size (Large Enterprises, SMEs), By Silver-bearing Ore (Silver-rich), and By All Other Metal Ores (Copper, Zinc, Lead, Nickel, Silver Ore).
Regional market analysis and geographic distribution
Geographically, the market is anchored by Asia-Pacific, which commands the largest consumption share due to massive steel production capacities in China and India. Latin America and Africa serve as primary export powerhouses, housing world-class iron and precious metal reserves. Meanwhile, North America and Europe exhibit stable, highly regulated demand focused heavily on critical minerals and technological upgrade cycles within existing extraction facilities.
In-depth regional review of key extracting territories
Latin America remains a dominant supply anchor for copper and iron ore, led by operations from Grupo Mexico S.A.B. de C.V. and Freeport-McMoRan Inc. Concurrently, the Pilbara region in Western Australia continues to be the global benchmark for low-cost, high-volume iron ore output facilitated by Fortescue Metals Group Limited and Anglo American plc, despite mounting water scarcity challenges.
Company profiles and strategic positioning
Industry leaders leverage distinct competitive advantages: Glencore International and AngloGold Ashanti Limited focus on strategic portfolio diversification across precious and base metals. Meanwhile, Norilsk Nickel and KGHM Polska Miedz SA secure dominant positions in specialized transition metals like nickel and copper, aligning directly with high-growth electric vehicle supply chains and renewable energy infrastructure requirements.
Porter's Five Forces analysis of the sector
The industry exhibits high barriers to entry due to immense capital expenditure requirements and lengthy government permitting processes. Supplier power remains moderate, as major miners control vast tier-one deposits. Conversely, buyer power is significant among major steel conglomerates and smelting complexes, while the threat of substitution is low given the irreplaceable nature of primary metal ores in heavy manufacturing.
SWOT analysis of the Metal Ore Market
Key strengths include robust asset bases among tier-one producers and deep integration into global supply chains. Weaknesses involve high exposure to volatile commodity pricing cycles and carbon-intensive extraction profiles. Opportunities abound in deep-sea mining and green-steel feedstocks, while major threats include escalating geopolitical trade tensions, resource nationalism, and stringent environmental taxation.
Value chain analysis from raw materials to end-users
The value chain initiates with geological exploration and resource delineation, progressing to drilling, blasting, and bulk extraction. Ore is subsequently routed through crushing, grinding, and beneficiation plants before being transported via specialized rail and maritime networks to global ports. Final value capture occurs at smelting and refining facilities operated by end-users in the automotive, construction, and electronics sectors.
Investment insights and high-potential areas
Our analysis highlights substantial investment potential in low-emission beneficiation technologies and critical mineral assets, particularly copper and nickel deposits. Investors should prioritize asset owners with robust ESG frameworks capable of navigating tightening regulatory landscapes while capitalizing on the projected $920.66 Billion market size by 2033.
Conclusion and key takeaways
The Metal Ore Market stands at a critical juncture of industrial transformation, transitioning from traditional volume-driven extraction to sustainable, tech-enabled production. With a projected expansion to $920.66 Billion by 2033 at a 11.20% CAGR, the sector offers compelling opportunities for stakeholders who successfully integrate decarbonization strategies with core operational excellence.
Research methodology for baseline estimates
Baseline market estimates are rigorously triangulated using a robust tripartite methodology. This combines exhaustive trade registry data from international customs bodies, primary stakeholder interviews with C-suite executives across top mining conglomerates, and secondary macroeconomic indicators assessing global manufacturing indices, steel output, and energy transition targets.
Scope of the report and coverage parameters
This report covers global market dynamics for the Metal Ore Market across all specified form, type, and organizational segments from 2026 through 2033. Analytical limitations include unpredictable geopolitical shifts, sudden regulatory interventions in major mining jurisdictions, and unforeseen macroeconomic fluctuations impacting global commodity pricing.
Recent developments in the Metal Ore Market
Recent industry momentum features major strategic moves, including joint venture agreements for greenfield copper exploration by First Quantum Minerals Ltd. and multi-billion-dollar decarbonization partnerships forged by Zijin Mining Group Co. Ltd. and China Molybdenum Co. Ltd. to transition fleet operations to renewable power sources.