Market overview and structural significance of the Drilling Services Market
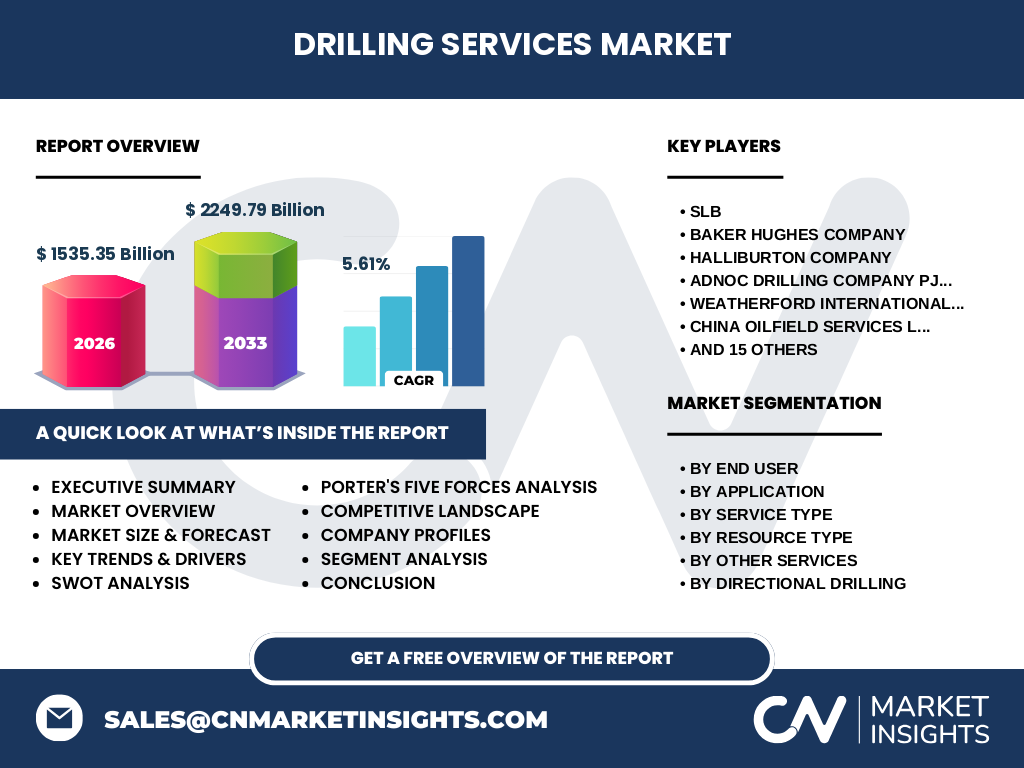
The Drilling Services Market represents a critical operational backbone for global energy extraction and mineral exploration. Valued at $1535.35 Billion in 2026, this sector encompasses essential technical interventions—ranging from directional drilling to mud logging—required to access complex hydrocarbon reserves, deep mineral deposits, and subterranean water tables. Industry significance lies in its direct correlation with global energy security and raw material supply chains.
Structural Growth Drivers and Market Restraints
Our analysis indicates that rising global energy demand and technological advancements in Rotary Steerable Systems (RSS) act as primary growth catalysts. Conversely, stringent environmental mandates enforced by bodies like the EPA and capital expenditure discipline among operators create notable restraints. The market must navigate these competing forces while maintaining project viability in increasingly complex geological formations.
Emerging trends and technological evolution
The shift toward automated and high-precision operations is redefining operational efficiencies across the sector. Industry participants are heavily investing in Measurement While Lrilling (MWD) and Logging While Drilling (LWD) innovations to optimize well placement. Real-time data telemetry has become standard, drastically reducing non-productive time and mitigating subsurface hazards in offshore environments.
COVID-19 impact analysis and subsequent recovery trajectory
The pandemic caused an unprecedented contraction in capital expenditure, disrupting logistics across major oilfield services hubs. However, the subsequent recovery trajectory has been robust, driven by aggressive post-pandemic energy demand and elevated commodity prices. Companies utilized this downtime to accelerate digital transformation, positioning the market for sustained expansion toward 2033.
Competitive landscape and market concentration dynamics
The competitive landscape features a mix of Tier-1 global oilfield service providers and specialized regional operators. Firms like SLB, Baker Hughes Company, and Halliburton Company dominate through comprehensive technological portfolios, while regional specialists such as ADNOC Drilling Company PJSC and Cocer AQS LLC leverage localized asset ownership to secure long-term concessions.
Executive Summary of the Drilling Services Market
Our comprehensive assessment reveals a thriving sector projected to reach $2249.79 Billion by 2033, expanding at a steady CAGR of 5.61%. This growth is underpinned by technological integration in directional drilling and sustained brownfield development. Strategic consolidation and digitalization remain key themes for stakeholders navigating this capital-intensive landscape.
Market forecast trajectory from 2027 to 2033
Based on our research, the Drilling Services Market is poised for accelerated expansion, scaling from its 2026 baseline to $2249.79 Billion by 2033. This trajectory reflects a consistent 5.61% CAGR, fueled by offshore deepwater developments, complex shale plays, and rising demand for critical minerals required in green energy transitions.
Segmentation analysis by End User, Application, and Service Type
Segmentation reveals diverse demand pockets across the industry. By End User, the market spans Oil And Gas, Mining, Water Exploration, and Construction And Geotechnical sectors. Applications divide into Onshore and Offshore, with Deepwater and Ultra Deepwater sub-segments demanding advanced Rotary Steerable Systems and specialized drilling fluids.
Geographic distribution and regional performance
Regional performance varies significantly based on resource endowment and regulatory frameworks. North America maintains substantial market share driven by onshore shale efficiency, while the Middle East and Africa exhibit robust activity anchored by state-led capacity expansions. Asia-Pacific demonstrates strong growth in mining and groundwater exploration, supported by rapid industrialization.
In-depth regional review of key operational hubs
A closer examination of the Middle East highlights intensive brownfield and offshore development managed by national oil companies alongside international partners. In contrast, the North American market prioritizes technological adoption, utilizing advanced extended reach drilling and geosteering services to maximize asset recovery from mature basins while complying with stringent emissions monitoring.
Strategic positioning of leading companies
Industry leaders maintain distinct competitive moats through proprietary hardware and software integration. Companies like Weatherford International plc and Nabors Industries Ltd. focus on rig automation and advanced tubular running services. Meanwhile, offshore specialists such as Transocean Ltd. and Seadrill Limited concentrate on ultra-deepwater floaters equipped with high-spec dynamic positioning.
Porter's Five Forces analysis of competitive pressures
Porter's analysis indicates moderate-to-high supplier power for specialized downhole tool manufacturers, while buyer power remains tempered by the technical criticality of drilling services. Threat of substitution is low due to the irreplaceable nature of physical wellbore creation, whereas competitive rivalry is intense among tier-one contractors vying for Tier-1 operator contracts.
SWOT analysis of the Drilling Services Market
Key strengths include advanced technological capabilities and entrenched client relationships. Weaknesses involve high capital expenditure requirements and exposure to commodity price volatility. Opportunities lie in geothermal energy expansion and automated rig operations, while threats center on regulatory tightening and geopolitical disruptions affecting cross-border supply chains.
Value chain analysis from raw materials to end-users
The value chain begins with raw material inputs like alloy steels and specialized chemical additives for drilling fluids. It progresses through engineering design, equipment manufacturing, and on-site service execution by firms such as Boart Longyear Group Ltd. or Precision Drilling Corporation, ultimately delivering operational wells to resource-extracting end-users.
Investment insights and high-potential areas
Investors should target technological innovators specializing in automated steering systems, real-time formation evaluation, and low-emission rig solutions. High-potential areas also include offshore deepwater support services and geothermal drilling applications, where traditional oilfield expertise translates directly into renewable energy deployment.
Conclusion and core industry takeaways
The Drilling Services Market remains an indispensable pillar of global resource extraction, balancing traditional fossil fuel demand with emerging energy transition requirements. Sustained by a 5.61% CAGR through 2033, the sector rewards firms that successfully integrate digital automation, environmental compliance, and operational efficiency into their service delivery models.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated using a multi-tiered approach. This combines primary stakeholder interviews with C-suite executives, comprehensive trade registry data from major port authorities, and secondary macroeconomic indicators sourced from international energy agencies to ensure high fidelity in our market sizing.
Scope of the report and analytical limitations
This report covers global drilling services across onshore and offshore applications, incorporating quantitative financial modeling up to the $2249.79 Billion horizon. Limitations include potential unforeseen geopolitical shifts, rapid macroeconomic policy adjustments, and localized regulatory changes that could alter near-term operational expenditure forecasts.
Recent developments, partnerships, and strategic moves
Recent market activity is characterized by strategic joint ventures and technology acquisitions aimed at expanding digital footprint and reducing carbon intensity. Firms such as Borr Drilling Limited and Archer Limited have actively secured contract extensions and deployed advanced rig-monitoring software to enhance operational transparency for discerning operators.