Market overview and structural significance of the Cricket Equipment Market
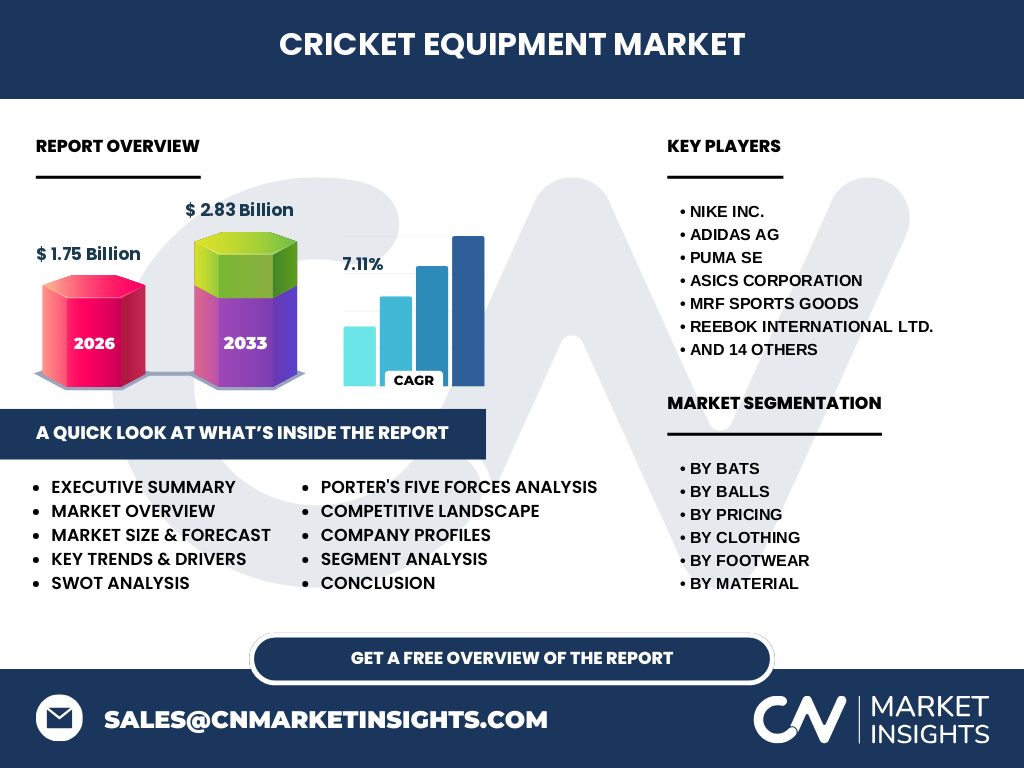
Our analysis indicates that the Cricket Equipment Market commands a valuation of 1.75 Billion in 2026, driven by formal governance under the International Cricket Council (ICC). The industry encompasses specialized manufacturing of English Willow and Kashmir Willow bats, protective gear like BS7928:2013-certified helmets, and technical footwear. Supply chains depend heavily on imported Salix alba timber and vulcanized rubber sourced via major maritime hubs in South Asia and Australasia.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is accelerated by lucrative franchise T20 leagues globally, yet manufacturers face severe raw material volatility regarding Grade 1 cleft availability. Regulatory pressures from standardization bodies demand rigorous impact testing for batting pads and helmets. Opportunities emerge in bio-composite materials and direct-to-consumer digital commerce, favoring brands capable of scaling agile supply chain networks across emerging cricket-playing nations.
Emerging trends and growth patterns in the Cricket Equipment Market
The shift toward lightweight, pre-knocked English Willow bats and smart sensor-embedded training bats is redefining consumer expectations. Brands are focusing on ergonomic moisture-wicking cricket jerseys and customized footwear featuring hybrid spiked configurations. This product premiumization directly supports higher average selling prices across digital and brick-and-mortar sports retail stores.
COVID-19 impact analysis and post-pandemic recovery trajectory
Pandemic-era lockdowns caused profound supply chain disruptions, halting timber harvesting and shuttering traditional sports retail stores. However, the subsequent rebound showcased robust pent-up demand. The market recovered swiftly as grassroots coaching academies reopened, accelerating inventory replenishment cycles for leather balls, protective gear, and junior-sized training equipment.
Competitive landscape, market concentration, and strategic dynamics
Market concentration features a mix of heritage legacy brands and aggressive multi-national sportswear conglomerates. Dominant players leverage high-profile athlete endorsements and exclusive kit-sponsorship deals with international boards. Key participants continuously invest in proprietary bat-pressing technologies and aerodynamic helmet shells to secure competitive differentiation.
Executive summary of the Cricket Equipment Market report
Our research forecasts the Cricket Equipment Market to expand from 1.75 Billion in 2026 to reach 2.83 Billion by 2033, registering a robust 7.11% CAGR. Strategic investments in e-commerce infrastructure, sustainable bio-composite materials, and localized manufacturing in South Asia represent the primary levers for capturing expanding market share.
Market forecast trajectory from 2027 to 2033
Driven by expanding broadcast footprints in North America and continental Europe, the sector is projected to scale steadily toward its 2.83 Billion target by 2033. Maintaining a steady 7.11% CAGR, growth will be propelled by rising disposable incomes in developing economies and increasing institutional funding for women's cricket programs globally.
Segmentation analysis across product categories and pricing tiers
The ecosystem is segmented by Bats (English Willow, Kashmir Willow, Training, Plastic, Tennis), Balls (Leather, Tennis, Rubber, Synthetic, Plastic), Pricing (Budget, Mid-range, Premium), Clothing, Footwear, Material, Product Type, Protective Gear, and Distribution Channel. Premium English Willow bats and leather balls anchor high-margin revenue streams, while tennis and plastic variants dominate high-volume recreational segments.
Regional market analysis and geographic distribution performance
Geographically, the Indian subcontinent commands dominant volume share due to immense participation rates and professional leagues. Meanwhile, Australasia and the United Kingdom represent mature, high-value markets with stringent safety compliance demands. Emerging pockets across the Middle East and North America exhibit accelerating adoption driven by expatriate communities and dedicated infrastructure development.
In-depth regional review of primary manufacturing and consumption hubs
India and Pakistan serve as the global epicenter for raw bat cleft processing and hand-crafted willow production, leveraging localized artisan expertise. Conversely, consumption hubs in the UK and Australia prioritize advanced protective gear engineering to meet strict domestic safety standards, shaping global export specifications and compliance benchmarks.
Company profiles and strategic positioning of leading industry participants
Industry stalwarts like Kookaburra Sport Pty. Ltd., GM (Gunn & Moore), and Sanspareils Greenlands Pvt. Ltd. (SG) dominate ball and bat manufacturing through century-old heritage. Concurrently, giants like Nike Inc., Adidas AG, and PUMA SE leverage massive global supply chains to capture high-volume footwear and apparel segments.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate-to-high due to finite supplies of premium Salix alba willow clefts. Buyer power is tempered by brand loyalty and professional player endorsements. Threat of substitutes is low in professional play due to strict Laws of Cricket, whereas competitive rivalry among established brands remains intense.
SWOT analysis of the global cricket gear ecosystem
Strengths include deep-rooted brand heritage and unmatched artisan craftsmanship. Weaknesses involve vulnerability to raw material scarcity and seasonal demand fluctuations. Opportunities lie in expanding youth leagues across non-traditional geographies, while threats encompass counterfeit manufacturing and rising logistics tariffs impacting cross-border trade.
Value chain analysis from raw materials to end-users
The value chain originates with sustainable timber harvesting and raw leather tanning, transitioning to specialized manufacturing facilities in South Asia. Finished goods move through complex logistics networks via ports like Mumbai and Melbourne, supplying hypermarkets, specialty sports retail stores, and direct-to-consumer online platforms.
Investment insights and high-potential growth areas
High-potential targets for institutional capital include direct-to-consumer digital platforms and eco-friendly equipment manufacturing initiatives. Investors should prioritize brands expanding into North American emerging markets and those developing certified lightweight protective gear tailored for the rapidly growing women's professional cricket circuit.
Conclusion and key strategic takeaways for market stakeholders
The Cricket Equipment Market presents compelling growth prospects, anchored by a projected 7.11% CAGR through 2033. Success requires balancing heritage craftsmanship with advanced digital marketing, rigorous safety compliance, and agile supply chain management to navigate fluctuating raw material availability and evolving consumer preferences.
Research methodology for baseline estimates and data triangulation
Our findings are synthesized by triangulating comprehensive trade registry data, primary stakeholder interviews with key manufacturing executives, and secondary macroeconomic indicators. Quantitative market sizing models cross-reference import-export tariffs, consumer spending metrics, and sports federation registration databases to ensure absolute analytical accuracy.
Scope of the report and analytical coverage parameters
This proprietary report evaluates the Cricket Equipment Market market size across global regions from 2026 to 2033. Coverage encompasses exhaustive product segmentation, distribution channel evaluations, and competitive benchmarking, while excluding non-regulated recreational backyard accessories and unverified counterfeit manufacturing output.
Recent developments, corporate announcements, and strategic partnerships
Recent industry momentum highlights major sportswear brands securing exclusive kit-sponsorship contracts with premier international cricket boards. Concurrently, specialized manufacturers like Masuri UK Shop have introduced upgraded stem guard technologies to enhance player safety, reflecting continuous product innovation across the sector.