What is the Market overview of the Digital Video Advertising Market?
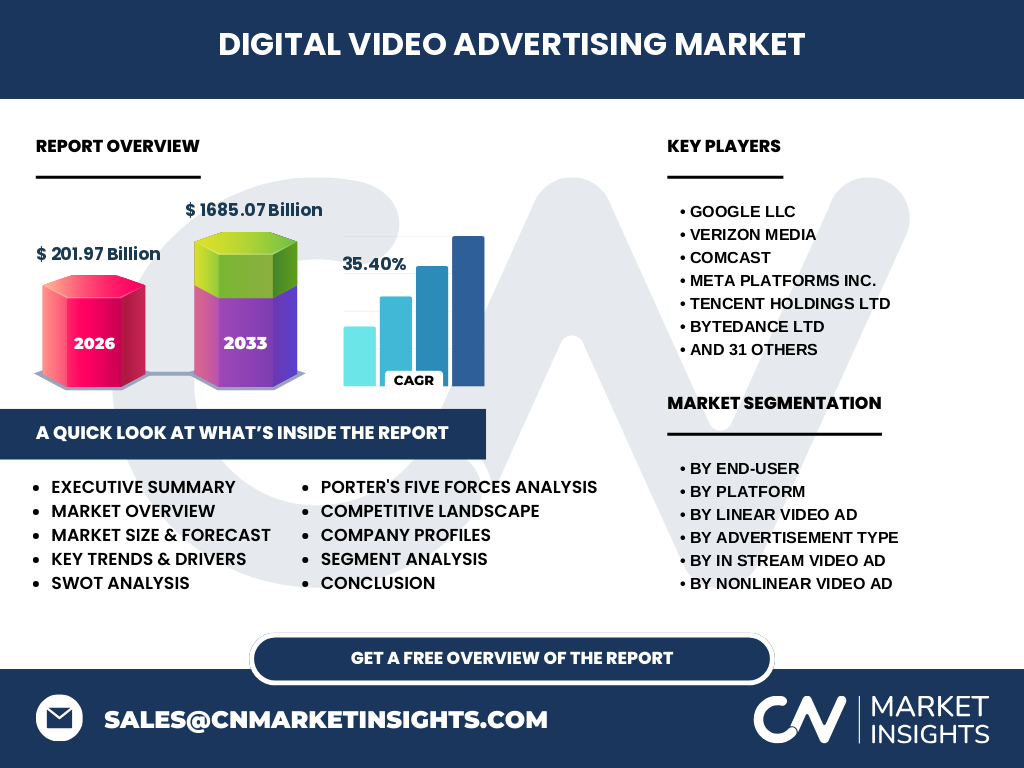
Our proprietary research values the Digital Video Advertising Market size at $201.97 Billion in 2026. This dynamic sector encompasses programmatic buying, Connected TV (CTV), and addressable linear insertions governed by bodies like the IAB. Industry significance lies in shifting brand budgets from legacy broadcast networks to precision-targeted digital screens.
Structural Growth Drivers and Market Restraints
The Digital Video Advertising Market industry trends highlight surging cord-cutting behaviors as primary growth catalysts. Conversely, strict privacy regulations enforced by the FTC and EU GDPR act as key restraints. Technical challenges include ad-fraud in programmatic exchanges, while immense opportunities persist within addressable Smart TV inventory.
Emerging Trends and Growth Patterns in the Sector
The Digital Video Advertising Market analysis reveals an aggressive migration toward programmatic guaranteed buying and shoppable video formats. Consumers increasingly favor ad-supported streaming tiers over traditional cable. Innovators like Roku Inc. and Samsung Ads are leading this shift, capturing high-intent audiences across fragmented household device ecosystems.
COVID-19 Impact Analysis and Market Recovery
The pandemic dramatically accelerated streaming consumption while temporarily depressing brand ad spend. As supply chains stabilized, our data indicates a rapid V-shaped recovery driven by surging e-commerce demand. Publishers quickly pivoted to server-side ad insertion (SSAI) to bypass ad blockers, securing long-term resilience for digital video formats.
Competitive Landscape and Strategic Dynamics
The Digital Video Advertising Market features intense competition among walled gardens and independent adtech providers. Major players like Google LLC, Meta Platforms Inc., and Amazon Advertising dominate audience reach, while specialists like The Trade Desk Inc. and PubMatic Inc. provide critical transparent demand-side and supply-side infrastructure.
Executive Summary of Key Findings
With a projected valuation reaching $1685.07 Billion by 2033, the Digital Video Advertising Market is expanding at an unprecedented 35.40% CAGR from 2027 to 2027. CTV expansion, retail media network integration, and advanced audience targeting are fundamentally reshaping media monetization models globally.
Market Forecast and Long-Term Projections
Driven by explosive consumer adoption of streaming video on demand, the Digital Video Advertising Market size is forecast to surge from $201.97 Billion in 2026 to $1685.07 Billion by 2033 at a 35.40% CAGR. This trajectory reflects robust publisher yields and continuous advertiser migration.
Segmentation Analysis Across Platforms and Ad Types
Our Digital Video Advertising Market analysis segments the industry by End-User (Retail, Automotive, BFSI, IT, Consumer Goods, Media, Government), Platform (Desktops, Mobile, Tablets, Smart TV, Gaming Consoles, Billboards), and Ad Type (Linear, Nonlinear, In-Stream, Out-Stream). Smart TVs and In-Stream VOD capture the highest marginal growth.
Regional Market Analysis and Geographic Distribution
North America commands the largest Digital Video Advertising Market share due to early programmatic adoption and massive streaming penetration. Meanwhile, Asia-Pacific represents the fastest-growing region, fueled by mobile-first populations in Southeast Asia and advanced social commerce ecosystems managed by Tencent Holdings and ByteDance.
In-Depth Regional Review
In North America, ad spend concentrates on premium CTV inventory and retail media integrations. Europe remains heavily influenced by stringent GDPR and DMA compliance, forcing localized players like Adform and Criteo S.A. to innovate privacy-safe identity solutions while maintaining robust campaign attribution metrics.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats: Amazon Advertising leverages first-party retail data; Google LLC utilizes expansive publisher networks and YouTube inventory; and Connected TV pioneers like Roku Inc. dominate living-room screens. Independent specialists such as Magnite Inc. and PubMatic optimize programmatic yield transparency.
Porter's Five Forces Analysis of Industry Competitiveness
Bargaining power of buyers is moderate to high due to massive demand-side platform (DSP) options. Threat of substitutes remains low given video engagement metrics. Competitive rivalry is fierce among walled gardens and independent exchanges, compelling continuous technological innovation in identity resolution and measurement.
SWOT Analysis of the Market Ecosystem
Key strengths include precise audience targeting and high engagement. Weaknesses involve complex supply chain transparency and ad fraud. Opportunities lie in emerging gaming console ads and shoppable formats. Threats stem from tightening privacy regulations and cookie deprecation by major browser operators.
Value Chain Analysis and Industry Structure
The value chain flows from content creators and publishers to supply-side platforms (SSPs), ad exchanges, demand-side platforms (DSPs), and finally to brand advertisers. Efficiency depends on low latency bidders like OpenX and Smaato maximizing yield across fragmented inventory sources.
Investment Insights and High-Potential Areas
Strategic capital should target Connected TV measurement solutions, privacy-compliant identity graphs, and AI-driven creative optimization tools. Investors will find outsized returns in companies bridging the gap between walled gardens and open web programmatic ecosystems.
Conclusion and Key Takeaways
The Digital Video Advertising Market industry trends confirm that video is the undisputed anchor of modern brand strategy. Achieving a 35.40% CAGR through 2033 underscores the sector's unstoppable momentum, rewarding market participants who prioritize transparency, privacy compliance, and cross-screen attribution.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining regulatory filings from bodies like the SEC, primary stakeholder interviews with adtech executives, and macroeconomic indicators. Bottom-up platform revenue analysis validates top-down programmatic spend data to ensure absolute market sizing accuracy.
Scope of the Report and Coverage Parameters
This report covers global digital video ad expenditures across desktop, mobile, tablet, Smart TV, and gaming platforms from 2026 to 2033. Exclusions include traditional offline broadcast television investments that lack digital measurement capabilities or programmatic addressability features.
Recent Developments in the Sector
Recent strategic moves include major consolidation among SSPs like Magnite, and retail media network expansions by Amazon and Walmart. Furthermore, platforms like Netflix and Disney+ launching ad-supported tiers have radically altered premium inventory availability across the Digital Video Advertising Market.