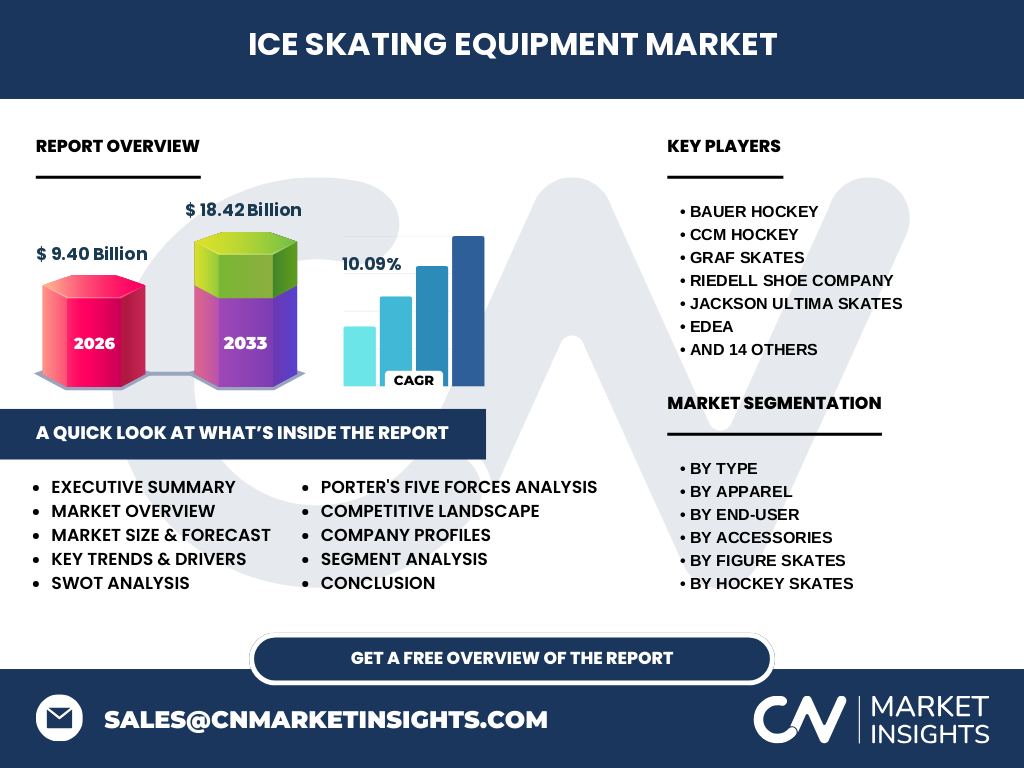
Market overview of the Ice Skating Equipment Market
Our analysis indicates that the Ice Skating Equipment Market represents a highly specialized sector encompassing specialized footwear, protective gear, and apparel. Valued at 9.40 Billion in 2026, this industry supports competitive sports, recreational leisure, and professional ice performances globally.
Key market drivers, restraints, challenges, and opportunities
The market thrives on rising disposable incomes and expanding indoor rink infrastructure. However, high raw material costs for carbon fiber and stainless steel constrain margins. Growth opportunities lie in customizable beginner figure skates and sustainable packaging across major ports.
Emerging trends and growth patterns in the Ice Skating Equipment Market
The shift toward lightweight composite materials is transforming Ice Skating Equipment Market industry trends. Manufacturers increasingly integrate thermoformable polymers to enhance ankle stability and reduce break-in periods for elite competitors using performance hockey skates.
COVID-19 impact analysis and recovery trajectory
Pandemic-related arena closures temporarily depressed demand for skating dresses and outfits and professional gear. However, the post-lockdown surge in outdoor recreational activities catalyzed a robust recovery, driven by strong online retail sales.
Competitive benchmarking and strategic market concentration
The landscape features intense rivalry among legacy brands like Bauer Hockey, CCM Hockey, and Jackson Ultima Skates. Companies maintain dominance through proprietary blade technologies, such as MK Blades and John Wilson Blades, creating high barriers to entry.
Executive summary of the Ice Skating Equipment Market
Driven by robust demand across recreational and professional sectors, our comprehensive Ice Skating Equipment Market analysis projects the market to reach 18.42 Billion by 2033, expanding at a notable CAGR of 10.09% from 2027.
Market forecast from 2027 to 2033
Our baseline estimates indicate steady acceleration, scaling the market from its 2026 baseline to 18.42 Billion by 2033. This expansion is powered by increasing youth participation in ice hockey leagues and televised figure skating events.
Segmentation analysis across product categories
The ecosystem breaks down by type into accessories, apparel, figure skates, hockey skates, and recreational skates. Sub-segments like skate sharpeners and helmet and protective gear ensure recurring aftermarket revenue streams for sporting goods retailers.
Regional market analysis and geographic distribution
North America and Europe currently dominate the geographic distribution due to dense winter sports infrastructure. Meanwhile, emerging economies in Asia-Pacific show the fastest growth rate, fueled by government investments in winter sports facilities.
In-depth regional review of key consumption hubs
Cold-climate regions maintain steady replacement cycles for youth hockey skates and adult gear. Conversely, non-traditional markets rely heavily on newly constructed indoor shopping mall rinks, driving demand for adjustable recreational skates.
Company profiles and strategic positioning
Industry leaders like Riedell Shoe Company, Edea, and Risport Skates focus on artisanal boot-making paired with modern thermoplastics. Meanwhile, brands like True Temper Sports leverage advanced engineering to capture market share in elite hockey.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized steel requirements, while buyer power is low given brand loyalty among professionals. Threat of substitutes is minimal, but competitive rivalry is fierce among established skate manufacturers.
SWOT analysis of the Ice Skating Equipment sector
Strengths include strong brand heritage and technical patents. Weaknesses involve seasonal sales volatility. Opportunities stem from e-commerce expansion, while threats include rising logistics expenses and regulatory compliance for protective equipment standards.
Value chain analysis from raw materials to end-users
The value flow begins with raw leather, steel, and synthetic polymers sourced by specialized vendors. It proceeds through precision manufacturing by firms like Harlick Skating Boots and SP Teri, moving down to sporting goods retailers and online stores.
Investment insights and high-potential focus areas
Investors should target direct-to-consumer digital channels and manufacturers of eco-friendly skate guards and apparel. Companies incorporating IoT-enabled performance tracking in advanced figure skates present exceptional capital appreciation potential.
Conclusion and strategic industry takeaways
The Ice Skating Equipment Market offers lucrative prospects through 2033. Success requires balancing heritage craftsmanship with digital marketing agility and lightweight material innovations to capture shifting consumer preferences.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with executives from K2 Sports and Tecnica Group, and secondary macroeconomic indicators regarding discretionary consumer spending.
Scope of the report and coverage parameters
This report covers global revenue trends, volume shipments, and pricing dynamics across all major product categories from 2026 to 2033. Excluded from this scope are commercial ice-rink refrigeration systems and arena construction services.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic acquisitions and athlete sponsorships by brands like Botas and GAM Skates. Collaborative product launches between blade makers and boot manufacturers continue to redefine high-performance edge control standards.