Market overview and industry significance of the Single-cell Analysis Market
Our analysis indicates that the Single-cell Analysis Market encompasses advanced technologies for resolving cellular heterogeneity at high resolution. Valued at 4.90 Billion in 2026, this sector is indispensable for oncology, immunology, and stem cell research, enabling precise profiling that bulk analysis obscures.
Key market drivers, restraints, challenges, and opportunities shaping the Single-cell Analysis Market
The market is driven by surging investments in precision medicine and technological leaps in Next Generation Sequencing. However, high instrument costs and complex workflow integration act as restraints, while emerging markets present lucrative expansion opportunities for forward-thinking players.
Emerging trends and growth patterns in the Single-cell Analysis Market
The data suggests a strong shift toward multi-omics integration and automated microfluidic platforms. Innovators like 10X Genomics Inc. and Standard BioTools Inc. are pioneering throughput enhancements, directly addressing laboratories' demands for high-fidelity cellular profiling.
COVID-19 impact analysis and recovery trajectory
The pandemic temporarily disrupted supply chains for specialized reagents and assay plates, yet it ultimately accelerated the adoption of single-cell transcriptomics for viral immunology studies. Post-pandemic recovery has been robust, catalyzing unprecedented funding into molecular diagnostics.
Competitive landscape and strategic market concentration
The market features intense competition among established life science giants and agile innovators. Companies such as Thermo Fisher Scientific Inc., Illumina Inc., and Becton Dickinson and Company leverage broad distribution networks, whereas specialized firms focus on proprietary single-cell isolation tech.
Executive summary of key findings for the Single-cell Analysis Market
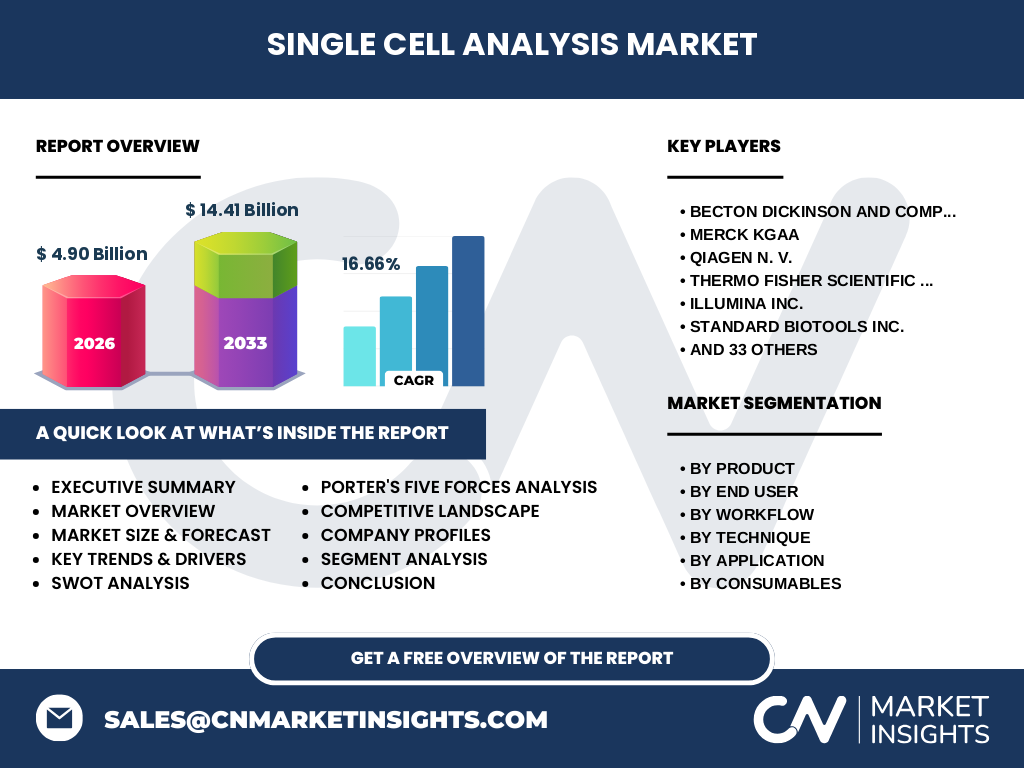
Our research forecasts the market to expand from 4.90 Billion in 2026 to reach 14.41 Billion by 2033, expanding at a robust 16.66% CAGR. Growth is anchored by surging translational research and rapid adoption of advanced flow cytometry and single-cell sequencers.
Market forecast from 2027 to 2033
Driven by compounding investments in biotechnology and pharmaceutical R&D, the market is projected to surge from 4.90 Billion in 2026 to 14.41 Billion by 2033. This trajectory reflects a sustained 16.66% CAGR, underscoring exceptional commercial viability.
Segmentation analysis across product, end-user, workflow, technique, and application
Segmentation spans multiple dimensions: Products (Consumables, Instruments), End Users (Academic labs, Biotech/Pharma, Hospitals), Workflows (Isolation, Downstream, Data analysis), Techniques (Flow cytometry, NGS, PCR, Microscopy, Mass spec), and Applications (Cancer, Immunology, Neurology, Stem cell, NIPD, IVF).
Regional market analysis and geographic distribution
Geographic performance highlights North America as the dominant revenue generator, bolstered by established biopharmaceutical clusters and robust NIH funding. Europe follows closely, driven by stringent regulatory frameworks supporting clinical genomics, while Asia-Pacific emerges as the fastest-growing frontier.
In-depth regional review of high-potential geographies
North America maintains dominance due to early technology adoption by major research institutions. Meanwhile, Asia-Pacific exhibits exceptional promise, fueled by expanding genomics infrastructure in China and Japan, alongside rising government investments in precision oncology.
Company profiles and strategic positioning of leading participants
Industry leaders occupy distinct strategic niches: Danaher Corporation and Agilent Technologies Inc. focus on workflow automation, while Oxford Nanopore Technologies Ltd. and Akoya Biosciences Inc. advance spatial and nanopore sequencing innovations to capture high-value diagnostic segments.
Porter's Five Forces analysis of competitive intensity
Our assessment reveals moderate-to-high supplier power for specialized microfluidic chips, contrasted by intense rivalry among established sequencer manufacturers. High switching costs for validated workflows create a protective moat, though threat of new entrants remains driven by venture-backed startups.
SWOT analysis of the Single-cell Analysis Market
Key strengths include high analytical resolution and broad oncology applications. Weaknesses involve prohibitive capital expenditure requirements. Opportunities lie in emerging multi-omics workflows, whereas threats encompass stringent regulatory clearance hurdles for clinical diagnostic adoption.
Value chain analysis from raw materials to end-users
The value chain flows from raw chemical and semiconductor material suppliers to reagent manufacturers and instrument fabricators like Bio-Rad Laboratories Inc. and Sartorius AG. Value is ultimately captured by pharmaceutical firms and clinical diagnostic laboratories executing translational research.
Investment insights and strategic recommendations
High-potential areas include AI-driven data analysis platforms and automated single-cell isolation kits. Investors are advised to target partnerships bridging hardware manufacturers with clinical software providers to capture synergies in precision medicine.
Conclusion and key takeaways for industry stakeholders
The Single-cell Analysis Market represents a cornerstone of modern molecular biology, supported by a 16.66% CAGR through 2033. Stakeholders must prioritize scalable workflows and multi-omics capabilities to secure long-term market share.
Research methodology utilizing triangulation and primary validation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, trade registry data, and primary stakeholder interviews with key opinion leaders across pharmaceutical firms, academic laboratories, and instrument manufacturing houses.
Scope of the report and coverage parameters
This report covers global revenue estimations from 2026 to 2033, segmented by product, workflow, technique, application, and end user. Limitations include localized reimbursement policy shifts and varying regulatory approval timelines across global health authorities.
Recent developments, partnerships, and strategic product launches
Recent industry momentum is defined by strategic acquisitions and platform launches, such as Takara Bio USA Holdings Inc. and Mission Bio Inc. releasing high-throughput multi-omics kits, enhancing single-cell resolution for rare cell detection in clinical oncology trials.