Retail Coolers Market Overview
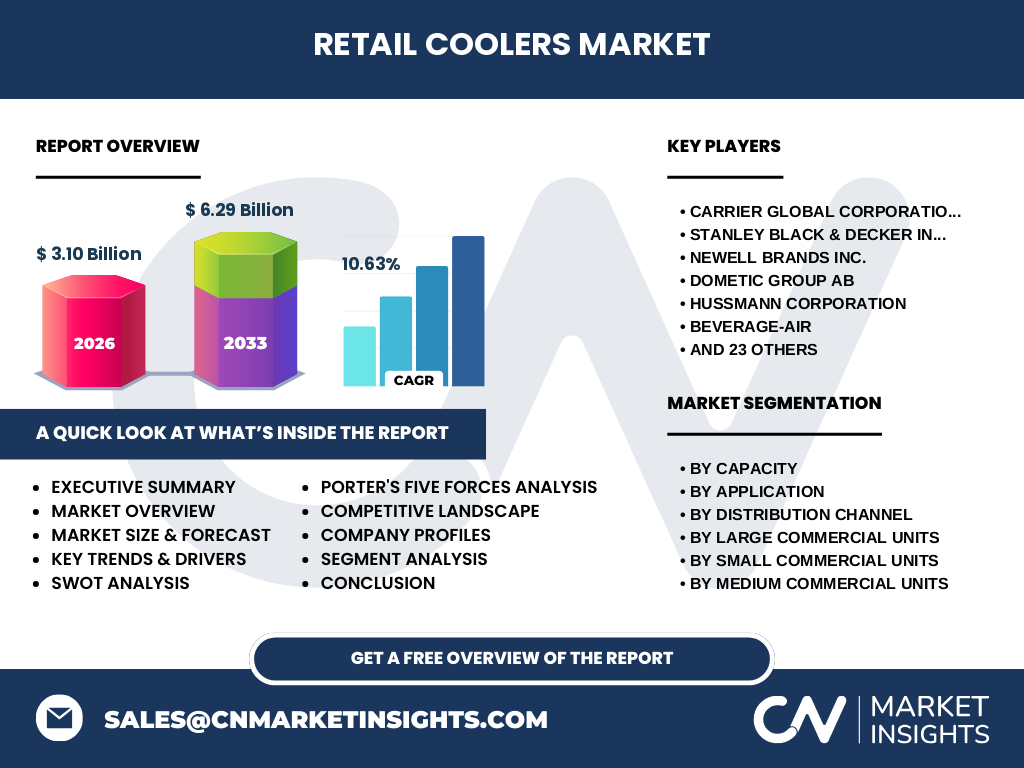
Our analysis values the Retail Coolers Market at $3.10 Billion in 2026, highlighting its vital role in global cold chain infrastructure. This ecosystem encompasses specialized commercial refrigeration assets—ranging from point-of-sale merchandisers to industrial walk-in units—designed to maintain strict thermal compliance for perishable foods, beverages, and pharmaceuticals across high-throughput retail environments.
Key Market Drivers, Restraints, and Opportunities
Growth is propelled by expanding convenience store formats and stringent food safety mandates set by bodies like the FDA. However, high initial capital expenditures and stringent refrigerant regulations, such as the AIM Act targeting HFC phase-downs, restrain deployment. Lucrative opportunities lie in integrating IoT-enabled predictive maintenance systems to minimize operational downtime.
Emerging Trends and Growth Patterns in Retail Coolers Market
The industry is pivoting aggressively toward eco-friendly natural refrigerants like R-290 (propane) and advanced inverter compressors that drastically lower energy consumption. Retailers increasingly demand transparent glass-door merchandisers equipped with LED illumination and smart inventory sensors to optimize stock rotation and boost impulse purchases.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially disrupted supply chains and delayed commercial store retrofits. Yet, it accelerated the demand for touchless glass doors, antimicrobial handles, and robust vaccine storage capabilities in pharmacies. The post-pandemic recovery trajectory reflects a resilient rebound driven by convenience retail expansion and contactless retail upgrades.
Competitive Benchmarking and Market Dynamics
The competitive landscape features established heavyweights like Carrier Global Corporation, Hussmann Corporation, and True Manufacturing Co. Inc. Market concentration is moderate-to-high, with industry leaders leveraging extensive global distribution networks and proprietary energy-saving technologies to outpace regional assemblers and secure lucrative supermarket chain contracts.
Executive Summary of the Retail Coolers Market
Driven by robust demand across grocery and pharmaceutical sectors, the Retail Coolers Market is projected to surge from $3.10 Billion in 2026 to $6.29 Billion by 2033 at a CAGR of 10.63%. Strategic investments in energy-efficient modular units and natural refrigerant technologies will separate market leaders from legacy manufacturers.
Market Forecast Projections Through 2033
Based on our macroeconomic and industry modeling, the market will expand aggressively, achieving a CAGR of 10.63% from 2027 to 2033. This trajectory will scale total sector valuation from the 2026 baseline of $3.10 Billion to an impressive $6.29 Billion by 2033, fueled by rapid urbanization and cold chain modernization.
Segmentation Analysis by Capacity and Application
Segmentation spans capacity tiers—Small, Medium, Large Commercial Units, and Walk-In or Modular Units—alongside applications including Supermarkets, Convenience Stores, and Pharmacy Retail. Large commercial and walk-in systems anchor heavy-duty backroom storage, while compact uprights and under-counter merchandisers drive front-of-store impulse sales.
Regional Market Distribution and Performance
Geographic performance varies significantly, with North America and Europe leading in adoption due to stringent energy regulations and mature retail chains. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by expanding organized retail, rising disposable incomes, and the proliferation of modern convenience store chains across urban centers.
In-Depth Regional Review
In North America, replacement cycles are dictated by EPA regulations favoring low-GWP refrigerants. In contrast, the Asia-Pacific region experiences greenfield installations driven by the rapid build-out of cold logistics infrastructure. European markets prioritize ultra-low energy consumption units to comply with strict EU Ecodesign directives.
Strategic Positioning of Leading Companies
Industry leaders optimize distinct strategic positions: Carrier Global Corporation and Hussmann Corporation dominate large supermarket retrofits with centralized refrigeration racks. Meanwhile, specialists like Beverage-Air, True Manufacturing Co. Inc., and Imbera capture high-volume convenience store placements through reliable, highly customized plug-in merchandisers.
Porter's Five Forces Analysis
The threat of new entrants remains low due to high manufacturing tooling costs, rigorous safety certifications, and established distributor relationships. Supplier power is moderate, balanced by raw material commoditization. However, buyer power is high, as major retail chains demand custom branding, IoT integration, and aggressive volume pricing.
SWOT Analysis of the Industry
Strengths include advanced thermal engineering and ubiquitous retail presence. Weaknesses involve high logistical costs for heavy, bulky units. Opportunities abound in smart IoT telemetry integration, while threats stem from volatile steel and copper commodity prices alongside tightening global environmental compliance standards.
Value Chain Analysis
The value chain flows from raw material extraction (stainless steel, copper tubing, polyurethane insulation) through component fabrication, compressor integration, and final assembly. Value is maximized at the distribution and retail integration stage, where smart IoT controllers and bespoke branding command premium margins for manufacturers.
Investment Insights and High-Potential Areas
High-potential investment pockets center on IoT-enabled predictive telemetry and natural refrigerant retrofitting technologies. Capital deployed toward manufacturers offering modular, easily scalable walk-in units will yield superior returns as retailers continuously reconfigure store footprints to optimize square footage.
Conclusion and Key Takeaways
The Retail Coolers Market represents a dynamic, high-growth sector set to reach $6.29 Billion by 2033. Success hinges on mastering energy efficiency, embracing natural refrigerants, and aligning product portfolios with the explosive growth of urban convenience retail and pharmaceutical cold storage.
Research Methodology
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with C-level executives, exhaustive secondary trade registry data from customs authorities, and macroeconomic indicators such as retail floor-space expansion rates and cold chain logistics investments.
Scope of the Report
This report covers global revenue estimations and volume shipments from 2026 to 2033 across specified capacity segments, end-use applications, and global geographic regions. Limitations exclude domestic residential refrigeration and industrial cold storage warehouses exceeding standard retail footprints.
Recent Industry Developments and Strategic Moves
Recent market activities feature major players launching propane-based (R-290) eco-friendly display lineups and forging strategic partnerships with IoT software providers. Companies like Epta Group and Hillphoenix have intensified merger and acquisition activities to secure proprietary energy-saving patents and expand geographic footprints in emerging economies.