Market overview of the Integrated Geophysical Services Market
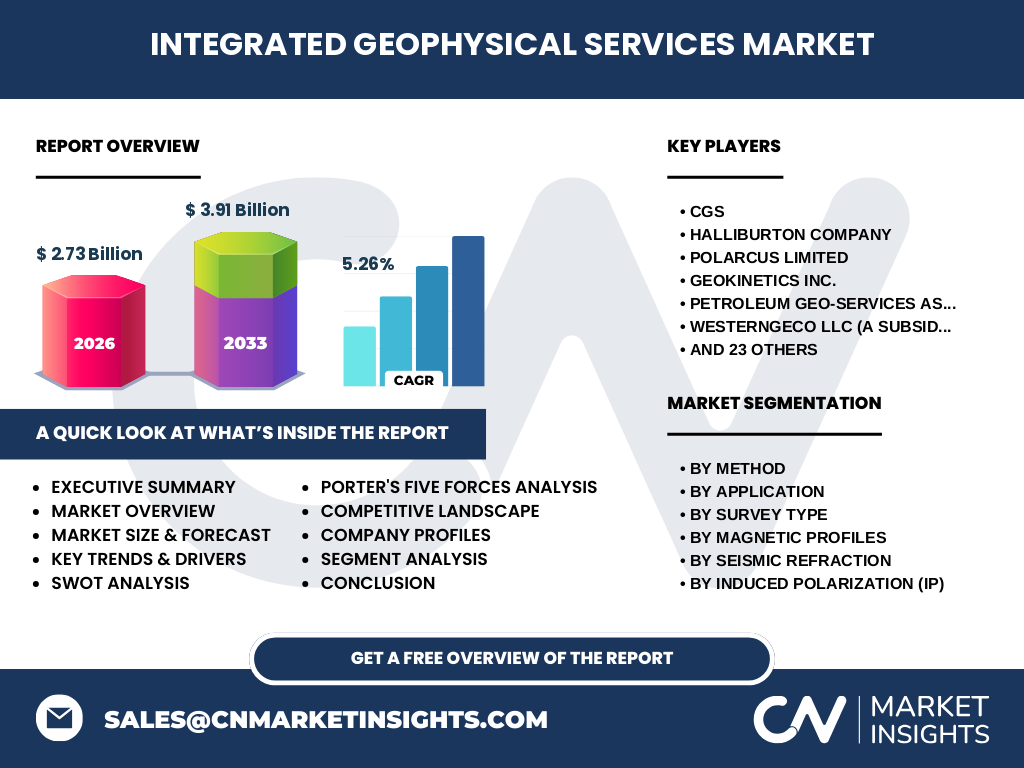
Our analysis indicates the Integrated Geophysical Services Market is valued at USD 2.73 Billion in 2026, serving as a critical backbone for subsurface characterization. The sector encompasses advanced techniques like Electrical Resistivity Tomography (ERT) and seismic prospection, supporting infrastructure development, offshore wind farms, and resource extraction across global energy hubs.
What are the primary growth drivers, restraints, challenges, and opportunities?
Structural growth is propelled by escalating demand for offshore wind farm surveys and mineral exploration. However, market expansion faces regulatory friction from bodies like the EPA and stringent environmental permitting. Opportunities lie in integrating differential GPS with microgravity surveys to enhance resolution for complex geotechnical engineering and waste management projects.
Emerging trends and growth patterns shaping the industry
The shift toward multi-component data acquisition is transforming the landscape, particularly in Shear Wave (S-Wave) studies and 3D Ground Penetrating Radar surveys. Industry participants are increasingly deploying autonomous aerial-based drone magnetometers to streamline high-sensitivity magnetic anomaly detection while lowering operational expenditures in remote terrains.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted field operations, delaying offshore cable tracking surveys and natural resource projects due to port lockdowns and travel restrictions. The post-COVID recovery trajectory has been robust, accelerated by stimulus-backed infrastructure spending and rapid digital transformation favoring remote data processing tools.
Competitive landscape and strategic market dynamics
Market concentration is moderately high, dominated by established tier-one players such as WesternGeco LLC, Petroleum Geo-Services ASA, and Halliburton Company. These industry leaders leverage proprietary marine acquisition vessels and advanced processing software to secure high-margin offshore energy contracts against agile regional service providers.
Executive summary of key findings
Our comprehensive research confirms a robust expansion trajectory, projecting the market to reach USD 3.91 Billion by 2033 at a CAGR of 5.26% from 2027. Stakeholders must prioritize technological integration across 2D seismic prospection and multi-channel analysis of surface waves to capture shifting demand.
Market forecast from 2027 to 2033
Driven by accelerating global energy transitions and infrastructure renewal, the market is set to scale steadily from its 2026 baseline of USD 2.73 Billion to hit USD 3.91 Billion by 2033, maintaining a consistent 5.26% CAGR as demand for water resource management intensifies.
Segmentation analysis across methods and applications
The market bifurcates across methodologies—ranging from Vertical Electrical Sounding using Schlumberger configurations to advanced Spectral Induced Polarization—and applications spanning infrastructure construction, mineral mining, and archaeological mapping. Each segment plays a specialized role in mitigating subsurface risk for engineering firms and energy operators.
Regional market analysis and geographic distribution
Geographic performance reflects distinct regional priorities, with North America and Europe leading in environmental waste management and offshore wind compliance. Meanwhile, Asia-Pacific demonstrates aggressive growth in infrastructure building construction, driven by rapid urbanization and heavy industrial investments requiring rigorous microgravity elevation corrections.
In-depth regional review of key markets
North America benefits from mature oil and gas basins coupled with stringent environmental monitoring mandates, while European markets prioritize high-frequency GPR for shallow imaging in densely populated urban zones. Asia-Pacific emerges as the fastest-growing region, propelled by maritime expansion and complex sedimentary basin analysis.
Company profiles and strategic positioning
Key innovators like Sercel SA and Phoenix Geophysics Limited focus on hardware manufacturing excellence, whereas firms like BGP Inc. and SAExploration Holdings Inc. dominate large-scale acquisition services. Strategic partnerships between hardware developers and data processors are becoming crucial for maintaining competitive moats.
Porter's Five Forces analysis
Industry rivalry is intense among tier-one contractors, while buyer power remains moderate due to the specialized nature of high-resolution 3D imaging. Threat of substitutes is low given the irreplaceable precision of combined seismic and electrical resistivity methods in complex geological formations.
SWOT analysis of the sector
Strengths include proprietary multi-channel analysis techniques and established vessel fleets. Weaknesses involve high capital expenditure hurdles. Opportunities abound in renewable energy site characterization, while threats stem from volatile commodity cycles impacting natural resource exploration budgets.
Value chain analysis from raw materials to end-users
The value chain originates with electronic component manufacturers supplying sensors and geophones to firms like OYO Geospace Corporation. It flows through data acquisition and inversion software processing, ultimately delivering actionable subsurface models to civil engineering contractors and energy developers.
Investment insights and high-potential areas
Investors should target niche service providers specializing in time-lapse ERT monitoring and offshore wind cable tracking. These high-potential domains offer superior margin resilience compared to traditional, highly commoditized seismic reflection services.
Conclusion and key takeaways
The integrated geophysical sector represents a vital, expanding frontier valued at USD 2.73 Billion heading toward USD 3.91 Billion by 2033. Capitalizing on environmental remediation and offshore renewable integration will separate market leaders from legacy laggards.
Research methodology and baseline estimation
Our baseline estimates are rigorously triangulated by synthesizing primary stakeholder interviews with c-suite executives, secondary macroeconomic indicators from energy ministries, and trade registry data from maritime authorities, ensuring robust bottom-up and top-down validation.
Scope of the report and coverage parameters
This report covers global deployment parameters across land-based and aerial-based survey types, analyzing 2026 baseline data through 2033 forecasts. Limitations exclude unverified grey-market proprietary surveys and uncertified local operators lacking international compliance standards.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights aggressive vessel fleet upgrades by Shearwater GeoServices AS and strategic software integration alliances forged by DMT GmbH & Co KG. These moves underscore a broader industry pivot toward automated, real-time inversion processing and reduced carbon footprint acquisition methodologies.