Market overview and structural significance of the Recyclable Cups Market
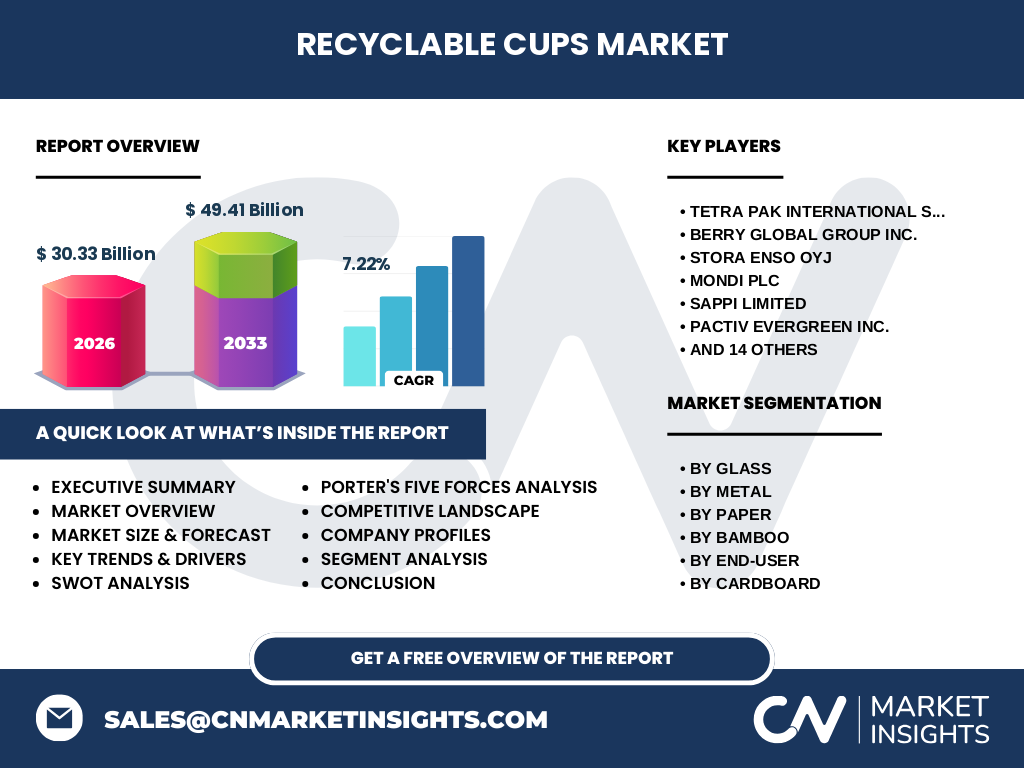
The Recyclable Cups Market represents a transformative shift in sustainable packaging, valued at $30.33 Billion in 2026. This sector encompasses diverse material ecosystems including glass, metal, paper, bamboo, and bioplastics, serving critical roles across food service, retail, and e-commerce supply chains worldwide.
Key market drivers, restraints, challenges, and opportunities shaping the Recyclable Cups Market
Stringent single-use plastics bans by regulatory bodies like the European Union act as primary catalysts. However, high collection costs and variable recycling infrastructure present severe logistical hurdles. Lucrative opportunities lie in developing advanced fiber-based coatings and bio-based polymers to capture surging eco-conscious demand.
Emerging trends and growth patterns in the Recyclable Cups Market
The shift toward strawless lids and bioplastics like PHA and starch blends defines current industry evolution. Leading converters are heavily investing in circular supply chain integration, prioritizing mono-material paper structures to facilitate seamless mechanical recycling at standard municipal recovery facilities.
COVID-19 impact analysis and recovery trajectory for the Recyclable Cups Market
The pandemic initially disrupted supply chains through widespread food service closures and hygiene anxieties favoring disposable plastics. Post-pandemic recovery accelerated hyper-growth, as corporate sustainability targets and heightened consumer hygiene awareness redirected capital toward certified sustainable paper and compostable alternatives.
Competitive landscape, major players, and strategic dynamics
Market concentration remains moderately fragmented, dominated by global packaging powerhouses like Tetra Pak, Huhtamäki Oyj, and Berry Global Group Inc. Strategic dynamics focus on vertical integration, proprietary barrier coating technologies, and aggressive cross-border mergers to secure sustainable raw material streams.
Executive summary of the Recyclable Cups Market
Our analysis indicates that the Recyclable Cups Market is positioned for robust expansion, projecting to reach $49.41 Billion by 2033 at a CAGR of 7.22%. Regulatory pressures and corporate net-zero pledges continue to drive unprecedented investments across both paper and bioplastic segments.
Market forecast and growth trajectory from 2027 to 2033
Driven by compounding sustainability mandates, the market will scale aggressively from 2027 through 2033. The projected CAGR of 7.22% underscores sustained volume growth, transitioning the industry from niche eco-friendly adoption to standard commercial deployment across global hospitality and retail.
Segmentation analysis across materials, end-users, and applications
Segmentation spans Material Type (Bioplastics, Cardboard, Paper, Glass, Bamboo, Metal), End-User (Food Service, Retail, E-Commerce, Hospitality), and Application (Hot vs. Cold Beverages). Paper and bioplastics lead volume share, while bamboo and metal capture premium retail segments.
Regional market analysis and geographic performance distribution
Geographic performance is heavily influenced by regional legislative frameworks. Europe leads adoption due to strict EU packaging directives, while North America exhibits rapid growth propelled by corporate sustainability initiatives. Asia-Pacific emerges as the fastest-growing manufacturing and consumption hub.
In-depth regional review of key packaging markets
In Europe, players like Stora Enso Oyj and Mondi plc leverage proximity to advanced forestry resources. North America relies on major converters like Dart Container Corporation and Pactiv Evergreen Inc. to navigate complex interstate recycling regulations and shifting municipal capabilities.
Company profiles and strategic positioning of leading market participants
Industry leaders utilize distinct competitive moats. Tetra Pak and Huhtamäki Oyj focus on aseptic paperboard innovations, while NatureWorks LLC and Sabert Corporation pioneer advanced bioplastics and closed-loop manufacturing frameworks to satisfy demanding global brand-owner specifications.
Porter's Five Forces analysis of the Recyclable Cups Market
Supplier power remains moderate, constrained by raw material availability like certified sustainable wood pulp. Buyer power is high due to low switching costs among food chains. Threat of substitutes is mitigated by tightening regulatory bans on traditional non-recyclable plastics.
SWOT analysis for strategic positioning in sustainable packaging
Strengths include robust regulatory tailwinds and enhanced corporate brand equity. Weaknesses involve higher production costs than virgin plastics. Opportunities center on emerging biopolymers, while threats include raw material price volatility and inadequate municipal composting infrastructure.
Value chain analysis from raw materials to end-users
The value chain originates with forestry, chemical, and agricultural raw material extraction. Mid-stream involves specialized barrier coating, thermoforming, and printing by converters like Metsä Board Corporation, culminating in distribution via online and offline channels to hospitality end-users.
Investment insights and high-potential areas for capital allocation
High-potential areas include proprietary aqueous barrier coatings replacing traditional PE linings and scalable PHA bioplastic production. Investors should target innovators collaborating closely with waste-sorting technology providers to ensure true circularity and regulatory compliance.
Conclusion and key takeaways for industry stakeholders
The Recyclable Cups Market represents a mandatory evolution for packaging stakeholders. Success requires aligning product portfolios with circular economy principles, investing in mono-material innovations, and navigating complex regional compliance frameworks effectively.
Research methodology for robust market sizing and validation
Our research combines rigorous bottom-up and top-down methodologies, triangulating customs trade registry data, primary executive interviews with packaging converters, and secondary macroeconomic indicators to deliver highly accurate baseline estimates and forecast models.
Scope of the report and analytical boundaries
This report covers global market dynamics from 2026 to 2033 across specified material, application, and distribution segments. Limitations include unforeseen geopolitical trade disruptions and fluctuating raw material commodity prices impacting regional cost structures.
Recent developments, corporate announcements, and strategic partnerships
Recent market activity highlights aggressive joint ventures between paper producers and chemical innovators. Companies like BioPak Pty Ltd and CupPrint Limited actively launch pilot circular recycling loops, reflecting an industry-wide pivot toward verified closed-loop operations.