Market overview of the mPOS Terminals Market
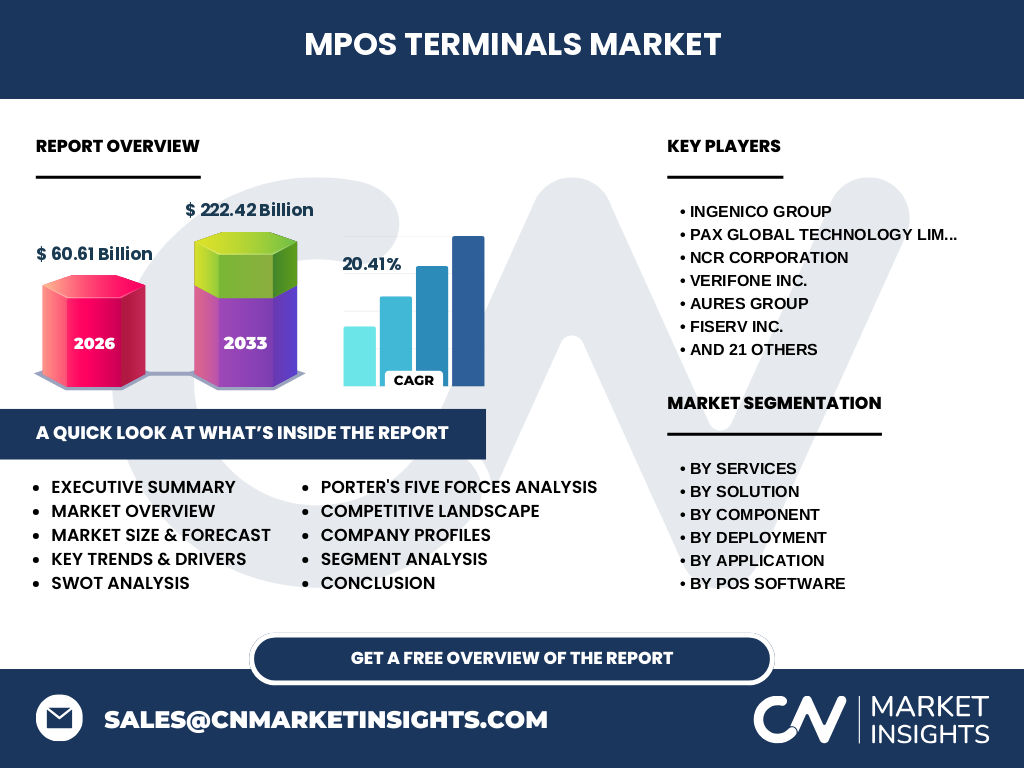
Our analysis indicates that the mPOS Terminals Market represents a transformative paradigm in transaction processing, bridging hardware and cloud software. Valued at 60.61 Billion in 2026, this sector encompasses mobile card readers, integrated systems, and contactless terminals governed by stringent PCI-DSS security frameworks and EMVCo standards, fundamentally altering how merchants accept digital payments.
What are the primary market drivers, restraints, challenges, and opportunities in the mPOS Terminals Market?
Growth is propelled by surging consumer preference for tap-and-go transactions and declining cash usage. However, high compliance costs and cross-border regulatory friction act as restraints. Hardware supply chain constraints pose operational hurdles, while lucrative opportunities emerge in integrating advanced inventory management software and customer relationship management solutions for micro-merchants.
Emerging trends and growth patterns in the mPOS Terminals Market
The shift toward cloud-based software deployment is revolutionizing merchant agility, allowing real-time analytics and reporting software integration. Market leaders like Square Inc. and Adyen N.V. are pioneering software-defined POS (SoftPoS) solutions that transform standard smartphones into secure payment acceptance devices, eliminating dedicated hardware overhead for small retailers.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as a powerful catalyst for the mPOS Terminals Market, permanently shifting consumer habits toward touchless commerce. Regulatory relaxations on contactless transaction limits during lockdowns accelerated deployment. The subsequent recovery trajectory has normalized growth, anchoring a robust CAGR of 20.41% as businesses permanently adopted omnichannel payment architectures.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of legacy payment giants and agile fintech innovators. Companies like Ingenico Group, VeriFone Inc., and PAX Global Technology Limited dominate hardware manufacturing, while disruptive players like SumUp Payments UAB and iZettle AB capture the micro-merchant segment. Strategic consolidation remains high as firms acquire software capabilities.
Executive summary of the mPOS Terminals Market report
Our research forecasts explosive expansion, with the mPOS Terminals Market surging from 60.61 Billion in 2026 to 222.42 Billion by 2033 at a CAGR of 20.41%. Accelerating digitalization across hospitality, healthcare, and retail sectors underpins this trajectory, making strategic software integration critical for long-term stakeholder profitability and market share acquisition.
Long-term market forecast from 2027 to 2033
Driven by widespread 5G rollout and IoT adoption, the market will scale aggressively over the forecast window. Reaching 222.42 Billion by 2033 at an impressive CAGR of 20.41%, growth will be heavily concentrated in emerging economies where unbanked populations leapfrog legacy desktop infrastructure directly into mobile-first payment ecosystems.
Comprehensive segmentation analysis of the industry
The ecosystem breaks down across services, solutions, components, deployment, and applications. Solutions split into hardware and software, while components comprise POS terminals, software, and services. Deployment models favor cloud-based architectures over on-premise setups, tailored to diverse end-users including retail, restaurant, healthcare, warehouse, and entertainment sectors.
Geographic distribution and regional performance dynamics
Regional performance varies based on local banking infrastructure, smartphone penetration, and regulatory mandates. North America and Europe exhibit high maturity with strict compliance protocols, whereas Asia-Pacific displays the fastest adoption rates, propelled by government-backed digital payment initiatives and surging smartphone usage among small and medium-sized enterprises.
In-depth regional review and localized market constraints
Localized constraints heavily dictate regional product strategies. In developing Asian markets, hardware durability and low-cost mobile card readers dominate. Conversely, North American and European merchants prioritize contactless payment terminals integrated with sophisticated customer relationship management software to navigate complex tax regulations and consumer privacy laws.
Strategic positioning of leading companies in the industry
Industry stalwarts balance hardware reliability with software versatility. Zebra Technologies Corp. and PAR Technology target specialized verticals like warehousing and restaurants, whereas Fiserv Inc., PayPal Inc., and Ingenico Group offer comprehensive end-to-end commerce solutions. Partnerships with SaaS providers allow these firms to capture recurring transactional revenue streams.
Porter's Five Forces analysis of the mPOS ecosystem
Competitive rivalry is intense, driven by numerous hardware manufacturers and nimble fintech entrants. Buyer power is moderate to high due to low switching costs for basic card readers. Supplier power remains moderate, concentrated around semiconductor and secure secure-element chip providers, while threat of substitutes is mitigated by continuous software feature innovation.
SWOT analysis of the mPOS Terminals Market
Strengths include high mobility, low setup friction, and robust encryption standards. Weaknesses involve vulnerability to cyber threats and hardware fragmentation. Opportunities lie in emerging market penetration and analytics integration. Threats encompass tightening global data privacy regulations and aggressive price wars among low-cost hardware manufacturers.
Value chain analysis from raw materials to end-users
The value chain originates with semiconductor fabrication and secure-element chip manufacturing. Component assemblers like BBPOS Limited and Newland Auto-ID Tech Co Ltd build the hardware. Software developers overlay payment processing and inventory tools, before distributors and ISOs deliver the final mPOS solution to retail and hospitality end-users.
Strategic investment insights and high-potential areas
Investors should target software-as-a-service (SaaS) integration capabilities and proprietary analytics platforms. Companies offering bundled inventory and customer relationship management software alongside payment processing command higher valuations and better merchant retention, representing the most lucrative deployment avenues through 2033.
Conclusion and key industry takeaways
The mPOS Terminals Market is transitioning from a simple hardware-swapping utility to a complex, data-driven software ecosystem. Achieving a projected 222.42 Billion valuation by 2033 underscores the permanent nature of mobile commerce. Stakeholders must prioritize software integration and regulatory compliance to capture sustained value.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated using a multi-tiered approach. We combine statutory trade registry data from customs authorities, primary qualitative interviews with C-level executives across POS providers, and secondary macroeconomic indicators, validated against historical transaction volumes to ensure absolute market sizing accuracy.
Scope of the report and analytical boundaries
This report evaluates the global mPOS Terminals Market across specified solution, service, component, deployment, application, and software segments. Geographic scope covers North America, Europe, Asia-Pacific, Latin America, and MEA. Macroeconomic forecasting models exclude unforeseen geopolitical shocks beyond the baseline data parameters.
Recent developments, partnerships, and strategic corporate moves
Recent market activity highlights aggressive ecosystem expansion. Major players like Adyen N.V., Square Inc., and VeriFone Inc. have launched advanced Android-based smart terminals featuring embedded software development kits, enabling seamless third-party app integration and cementing their competitive advantage in omnichannel retail environments.