What is the market overview and definition of the Onshore Artificial Lift Systems Market?
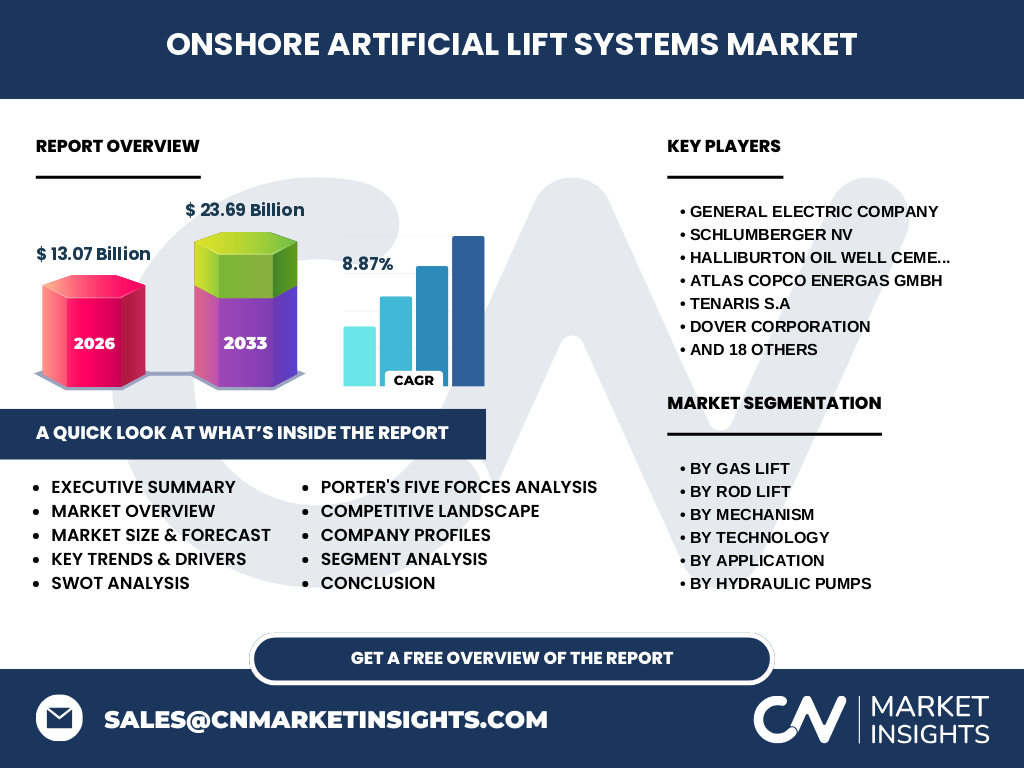
The Onshore Artificial Lift Systems Market represents a critical sector valued at $13.07 Billion in 2026, engineered to elevate fluids from mature onshore wells where reservoir pressure proves insufficient. Our analysis indicates that this market encompasses diverse mechanisms like electrical submersible pumps and rod lifts deployed across harsh land environments, ensuring sustained hydrocarbon recovery.
What are the key market drivers, restraints, challenges, and opportunities shaping the Onshore Artificial Lift Systems Market?
Structural growth relies on maturing onshore basins and the imperative to maximize recovery factors. However, supply chain bottlenecks for raw materials like specialty alloys and stringent environmental regulations imposed by agencies such as the EPA restrain rapid expansion. Opportunities lie in integrating automation technologies from innovators like SPOC Automation to optimize well performance.
Emerging trends and growth patterns in Onshore Artificial Lift Systems Market
The shift toward digitalization and real-time downhole telemetry is transforming operations. Operators increasingly demand variable-speed electrical submersible pumps and high-performance progressive cavity pumps. Upwing Energy Inc. and similar technology pioneers are redefining subsurface artificial lift efficiency to handle complex multiphase flows in depleted reservoirs.
How did the COVID-19 pandemic impact the Onshore Artificial Lift Systems Market and what is the recovery trajectory?
The pandemic triggered severe capital expenditure contractions, causing widespread deferred well completions and delayed infrastructure projects. Recovery has been robustly propelled by soaring global energy demand and aggressive supply replenishment, driving the market toward a projected valuation of $23.69 Billion by 2033.
Competitive landscape, major players, market concentration, and strategic dynamics
The competitive landscape is consolidated among tier-one oilfield service giants such as Schlumberger NV, Halliburton Oil Well Cementing Co., and Baker Hughes equivalents, alongside specialized providers like Dover Corporation and Weatherford International plc. Strategic dynamics center on proprietary variable-speed drive integrations and comprehensive lifecycle service bundles.
Executive summary of key findings in the Onshore Artificial Lift Systems Market report
Our comprehensive research reveals that the Onshore Artificial Lift Systems Market is poised for an impressive 8.87% CAGR from 2027 to 2033. Key findings highlight that technological convergence with automation and a growing reliance on progressive cavity and rod lift systems will capture disproportionate revenue shares across key onshore basins.
What is the market forecast and projected growth trajectory from 2027 to 2033?
Driven by persistent mature asset decline curves and rising unconventional drilling activities, the market will scale from its 2026 baseline to reach $23.69 Billion by 2033. This trajectory underscores a compound annual growth rate of 8.87%, reflecting sustained investments in artificial lift optimization.
Segmentation analysis of the Onshore Artificial Lift Systems Market
Segmentation spans multiple dimensions: By Gas Lift (Continuous, Intermittent, Assisted), By Rod Lift (Conventional, High-Efficiency, Dual Pump), By Mechanism (Pump and Gas Assisted), By Technology (Rod Lift, ESP, PCP, Gas Lift, Hydraulic, Plunger, Pump Jack), and By Application (Oil and Gas). Each segment addresses specific reservoir rheology and lifting constraints.
Regional market analysis and geographic distribution
Geographic performance is heavily concentrated in regions with massive onshore land rig counts, notably North America, the Middle East, and Russia. Logistical hurdles, local content mandates, and distinct regional crude viscosities dictate whether operators deploy high-temperature ESPs or rugged surface-mounted hydraulic pumps.
In-depth regional review of high-potential onshore production zones
North America remains a dominant revenue generator due to extensive unconventional shale plays requiring high-frequency artificial lift interventions. Meanwhile, Middle Eastern onshore fields favor robust, high-volume electrical submersible pumps and continuous gas lift configurations to manage prolific production rates under extreme thermal conditions.
Company profiles and strategic positioning in the Onshore Artificial Lift Systems Market
Industry participants deploy distinct strategies: Tenaris S.A. leverages robust tubular solutions, Lufkin Industries LLC dominates rod lift manufacturing, and Alkhorayef Petroleum secures regional dominance through localized service delivery. Innovators like Upwing Energy Inc. focus on sub-surface compression technologies to unlock marginal reserves.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers remains moderate to high due to consolidated E&P operators demanding cost-effective lifting solutions. Threat of substitutes is mitigated by the physical necessity of artificial lift in depleted wells, while supplier power is constrained by specialized raw material dependencies for high-grade pump components.
SWOT analysis of the Onshore Artificial Lift Systems Market
Strengths include entrenched technological reliability and essential roles in mature asset management. Weaknesses involve high initial capital expenditures. Opportunities stem from automated telemetry integrations, while threats encompass macroeconomic commodity price volatility and stringent environmental compliance mandates governing fugitive emissions.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material suppliers providing corrosion-resistant alloys, flows through precision manufacturing by entities like National Oilwell Varco Inc. and Atlas Copco Energas GmbH, progresses via service providers handling field deployment, and culminates with oil and gas operators achieving optimized hydrocarbon extraction.
Investment insights and high-potential areas for capital deployment
Investors should target high-temperature and variable-speed electrical submersible pump technologies, alongside automated surface controllers that minimize manual well interventions. Companies offering integrated digital monitoring solutions exhibit superior margin expansion potential within this 8.87% CAGR landscape.
Conclusion and key takeaways for industry stakeholders
Sustained revenue expansion toward $23.69 Billion by 2033 proves that artificial lift remains indispensable for global energy security. Stakeholders must prioritize technological agility, digital integration, and robust regional service footprints to capture maximum value from maturing onshore acreage.
Research methodology used to triangulate market estimates
Our analytical framework triangulates baseline estimates by combining proprietary trade registry data, extensive primary interviews with C-suite executives and petroleum engineers, and secondary macroeconomic indicators. This rigorous validation process ensures precise sizing of the $13.07 Billion 2026 market baseline.
Scope of the report and coverage parameters
This report covers global onshore deployment of artificial lift systems across oil and gas applications, excluding offshore infrastructure. Limitations include unforeseen geopolitical disruptions and sudden regulatory shifts impacting regional onshore drilling activity across key producing nations.
Recent developments, product launches, and strategic moves
Recent industry momentum features strategic acquisitions, joint ventures, and advanced product rollouts focused on energy efficiency. Companies like SPOC Automation and Haimo Technologies Group Corp. have introduced next-generation automated controllers designed to reduce downtime and carbon footprints across onshore production fields.