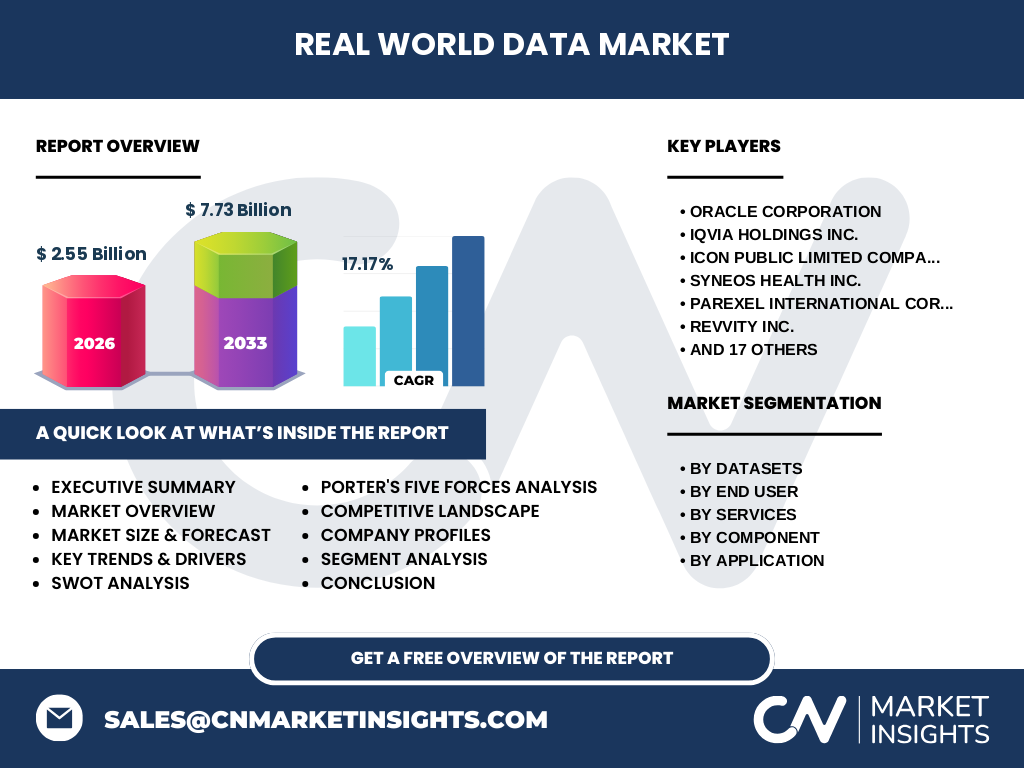
Market overview of the Real World Data (RWD) Market
The Real World Data (RWD) Market is valued at $2.55 Billion in 2026 and encompasses patient-level information derived from diverse non-interventional sources. Our analysis indicates this ecosystem forms the empirical backbone of modern health economics, supporting regulatory submissions overseen by agencies like the FDA and EMA while navigating strict privacy frameworks such as HIPAA and GDPR.
What are the core drivers and constraints shaping the Real World Data (RWD) Market industry trends?
Structural growth is propelled by the acute demand for evidence-based medicine and post-marketing surveillance. However, our research highlights persistent logistical hurdles, including fragmented data silos across regional hospital networks, severe interoperability bottlenecks, and mounting cybersecurity threats that constrain rapid data aggregation for life sciences enterprises.
Emerging trends and growth patterns in Real World Data (RWD) Market
The shift toward multi-modal data integration is revolutionizing the Real World Data (RWD) Market market size expansion. Industry innovators are fusing unstructured Electronic Health Records with high-throughput genomic data and patient-generated health metrics, enabling precision oncology and hyper-targeted clinical trial recruitment through advanced machine learning pipelines.
COVID-19 impact analysis and recovery trajectory
The pandemic served as an unprecedented catalyst, forcing regulatory bodies to embrace decentralized clinical trials and rapid-cycle evidence generation. Based on our research, this crisis-driven agility permanently accelerated enterprise reliance on longitudinal datasets from platforms like Datavant and TriNetX to monitor vaccine safety and treatment efficacy in real time.
Competitive Benchmarking: Major players and strategic dynamics
Market concentration is intensifying as analytics giants acquire specialized curation startups. Industry titans like IQVIA Holdings Inc. and Flatiron Health Inc. leverage proprietary network access to clinical feeds, while specialized innovators such as Tempus Labs and Komodo Health carve out dominant niches in oncology and disease-specific journey mapping.
Executive summary of key findings
Our comprehensive audit projects the Real World Data (RWD) Market to surge from $2.55 Billion in 2026 to $7.73 Billion by 2033, expanding at a robust CAGR of 17.17%. This trajectory underscores a strategic industry pivot toward outsourced data standardization services and AI-driven analytics for accelerated drug development.
Market forecast from 2027 to 2033
Driven by compounding adoption across biopharmaceutical pipelines, the Real World Data (RWD) Market industry trends point to a hyper-growth phase. The projected advance to $7.73 Billion by 2033 reflects accelerated commercial investments in real-world evidence to secure favorable market access, pricing reimbursement, and label expansions.
Segmentation analysis across datasets, end-users, services, and applications
The market is structured across core verticals: By Datasets (Claims Data, Pharmacy Data, Electronic Health Records, Patient-Generated Health Data, Laboratory And Diagnostic Data, Genomic Data); By End User (Pharmaceutical And Medical Device Companies, Healthcare Payers, Healthcare Providers, Government Agencies, Other End Users); By Services (Data Collection, Integration, Analytics, Validation, Regulatory Compliance); By Component (Services, Datasets); and By Application (Drug Development, Market Access, Post-Market Surveillance, Clinical Research).
Regional market analysis and geographic performance
Geographic distribution heavily favors North America, anchored by mature reimbursement frameworks and dense electronic health record adoption. Meanwhile, Europe demonstrates steady consumption governed by stringent GDPR mandates, whereas Asia-Pacific emerges as the fastest-growing frontier due to massive patient populations and rapidly modernizing hospital informatics infrastructure.
In-depth regional review of high-growth territories
North America dominates the valuation landscape, driven by concentrated biopharmaceutical R&D hubs in Boston and the San Francisco Bay Area. Concurrently, our analysis shows that European markets are prioritizing federated data networks to comply with cross-border health data transfer restrictions while fueling localized oncology registries.
Company profiles and strategic positioning
Leading entities exhibit distinct strategic moats. Oracle Corporation and Palantir Technologies Inc. provide enterprise-grade data orchestration architecture, whereas Aetion Inc. and Clarify Health Solutions Inc. specialize in transparent evidence generation platforms that appeal directly to cautious healthcare payers and medical device manufacturers.
Porter's Five Forces analysis of the competitive landscape
Competitive rivalry is intense among established clinical data brokers, though high capital requirements for proprietary data lake curation create a formidable barrier to entry. Buyer power remains moderate-to-high, as major pharmaceutical sponsors demand granular, disease-specific cohorts with proven regulatory lineage.
SWOT analysis of the Real World Data (RWD) Market
Strengths include vast longitudinal patient tracking; Weaknesses involve persistent data interoperability hurdles; Opportunities lie in AI-powered predictive biomarker discovery; and Threats center on tightening global privacy legislation and potential security breaches of sensitive health archives.
Value chain analysis from raw data capture to end-users
The value flow initiates at point-of-care facilities and pharmacy point-of-sale terminals, progressing through de-identification, data cleansing, and standardization layers managed by firms like HealthVerity. Downstream value is captured by analytics providers who package these assets for pharmaceutical commercialization teams.
Investment insights and high-potential areas
High-potential capital allocation targets include automated data validation services and privacy-enhancing technologies like synthetic data generation. Investors should prioritize platforms capable of bridging unstructured physician notes with genomic profiles to capture maximum value in precision medicine.
Conclusion and key takeaways
The Real World Data (RWD) Market represents an indispensable asset class for modern life sciences, scaling rapidly toward $7.73 Billion by 2033. Stakeholders must prioritize robust data governance, advanced AI integration, and cross-sector partnerships to maintain a competitive advantage in evidence-based healthcare.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing primary executive interviews with biopharmaceutical data officers, exhaustive secondary trade registry reviews, and macroeconomic healthcare expenditure models, validated through iterative econometric cross-checking.
Scope of the report and coverage parameters
This report evaluates the global Real World Data (RWD) Market across designated components, service tiers, and application use cases from 2026 through 2033. Excluded from this specific scope are primary clinical trial patient recruitment costs outside of retrospective database queries.
Recent developments, partnerships, and strategic moves
Recent industry momentum is defined by aggressive strategic acquisitions and cross-industry data-sharing pacts. Key innovators have formed alliances with major hospital systems to secure continuous real-time feed access, bypassing legacy intermediaries to accelerate oncology trial matching and regulatory safety reporting.