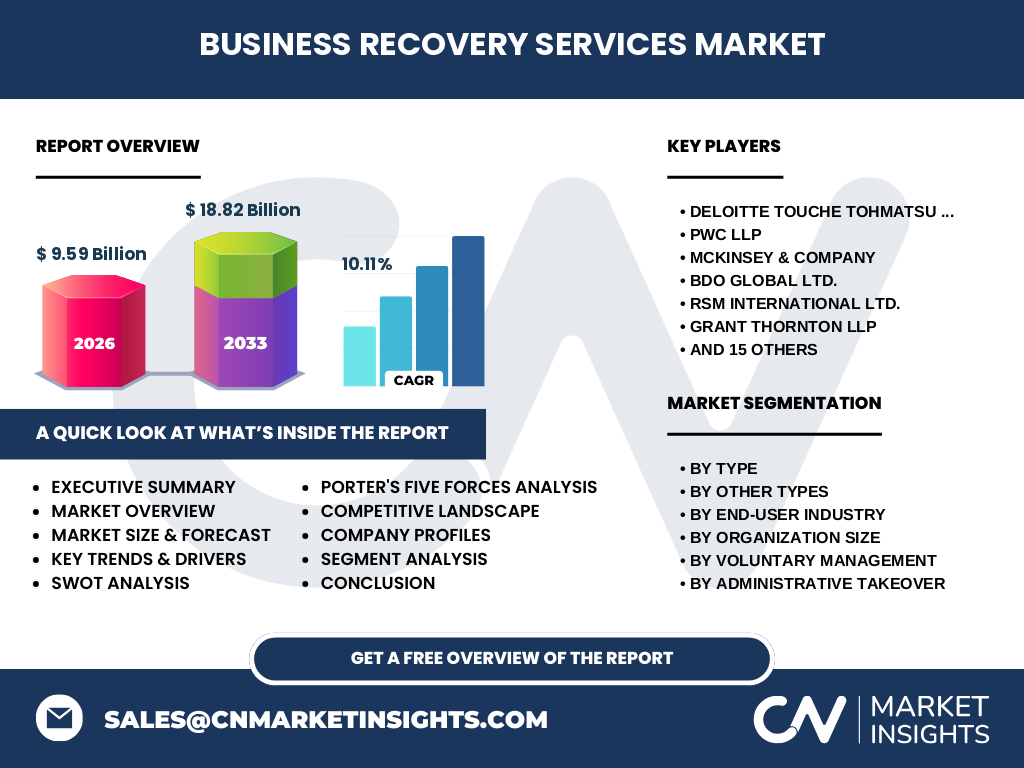
What is the Business Recovery Services Market overview and industry significance?
Our analysis indicates that the Business Recovery Services Market reaches a valuation of 9.59 Billion in 2026. This sector encompasses vital advisory, turnaround consulting, and insolvency practices regulated by bodies like the Insolvency Service, safeguarding corporate value across volatile economic cycles.
What are the core drivers, restraints, and opportunities shaping the Business Recovery Services Market?
The market is propelled by rising corporate insolvencies and stringent regulatory enforcement. However, high restructuring costs act as a restraint. Lucrative opportunities emerge in digital-first turnaround consulting and pre-pack administration, helping distressed firms mitigate supply chain disruptions.
Emerging trends and growth patterns in Business Recovery Services Market
Recent industry trends highlight a sharp pivot toward technology-enabled debt restructuring programs and informal workout arrangements. Firms are increasingly adopting AI-driven forensic accounting to streamline court-ordered liquidation and accelerate asset recovery for creditors.
How did the COVID-19 pandemic impact the Business Recovery Services Market and its recovery trajectory?
Pandemic-era fiscal stimulus artificially suppressed bankruptcies, but subsequent liquidity crunches accelerated demand for company voluntary arrangements (CVAs). Our research shows that post-pandemic recovery heavily relies on proactive receivership and regulatory enforcement actions.
Competitive Benchmarking and Industry Concentration
The competitive landscape features high market concentration among elite firms like Deloitte Touche Tohmatsu Limited, PwC LLP, and FTI Consulting Inc. These industry leaders leverage global footprints to dominate complex cross-border compulsory liquidations and creditor voluntary liquidations.
Executive summary of the Business Recovery Services Market
Our exhaustive research projects the Business Recovery Services Market to expand from 9.59 Billion in 2026 to 18.82 Billion by 2033, achieving a robust 10.11% CAGR. Strategic investments in administrative takeover capabilities remain paramount.
Market forecast and long-term valuation projections from 2027 to 2033
Driven by compounding macroeconomic headwinds, the market will scale aggressively at a 10.11% CAGR, culminating in a total valuation of 18.82 Billion by 2033. This trajectory underscores sustained demand for specialized insolvency practitioner services.
Segmentation analysis across types, end-users, and organization sizes
The market segments by type into Administrative Takeover, Compulsory Liquidation And Creditor Voluntary Liquidation, and Voluntary Management. End-user verticals span Healthcare, Financial Services, Manufacturing, Retail, Government, IT, and Telecommunications, serving Small, Medium, and Large Enterprises.
Regional market analysis and geographic performance distribution
Geographic performance indicates heavy concentration in mature economies with strict corporate governance frameworks. Regional disparities are driven by localized bankruptcy laws, distinct court-appointed administrator protocols, and varying degrees of regulatory enforcement.
In-depth regional review of key insolvency markets
North America and Europe currently anchor global demand due to rigorous regulatory frameworks governing corporate distress. Meanwhile, developing Asia-Pacific jurisdictions are rapidly formalizing their informal workout arrangements and pre-pack administration protocols.
Strategic company profiles of leading market participants
Industry titans such as McKinsey & Company, Alvarez & Marsal Holdings LLC, and Grant Thornton LLP offer specialized turnaround consulting. Meanwhile, mid-tier specialists like BDO Global Ltd. and RSM International Ltd. capture middle-market restructuring demands.
Porter's Five Forces analysis of competitive intensity
Bargaining power of creditors is high due to fiduciary obligations, while competitive rivalry among top-tier advisory firms remains fierce. Threat of new entrants is mitigated by high regulatory barriers and the necessity for established insolvency practitioner credentials.
SWOT analysis of the Business Recovery Services Market
Key strengths include robust proprietary restructuring methodologies and deep regulatory expertise. Weaknesses involve high advisory fees. Opportunities lie in digital workout tools, while threats stem from unpredictable macroeconomic policy shifts affecting corporate debt burdens.
Value chain analysis from raw advisory inputs to end-user execution
The value chain initiates with macroeconomic data collection and regulatory compliance auditing. It progresses through forensic analysis and turnaround strategy formulation, culminating in court-ordered liquidation or successful debt restructuring execution for distressed corporations.
Investment insights and high-potential strategic growth areas
Investors should target boutiques specializing in pre-pack administration and digital debt restructuring programs. High-potential areas include technology-driven turnaround consulting tailored for mid-market manufacturing and healthcare entities facing severe liquidity strains.
Conclusion and key takeaways for industry stakeholders
Surpassing 18.82 Billion by 2033, the market offers lucrative avenues for firms mastering digital transformation in insolvency. Stakeholders must align their service portfolios with complex regulatory demands and cross-border restructuring mandates.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are triangulated by combining national trade registry filings, primary qualitative stakeholder interviews with insolvency practitioners, and secondary macroeconomic indicators regarding corporate default rates and bankruptcy filings.
Scope of the report and coverage parameters
This report covers global advisory services related to corporate distress, liquidation, and turnaround management from 2026 through 2033. It excludes consumer personal bankruptcy filings, focusing strictly on B2B corporate recovery mechanisms and regulatory frameworks.
Recent developments, strategic partnerships, and product launches
Recent strategic moves feature prominent firms like FTI Consulting Inc. and PwC LLP launching proprietary AI-driven restructuring software. These innovations automate asset valuation during court-appointed administrator proceedings and expedite creditor committee communications.