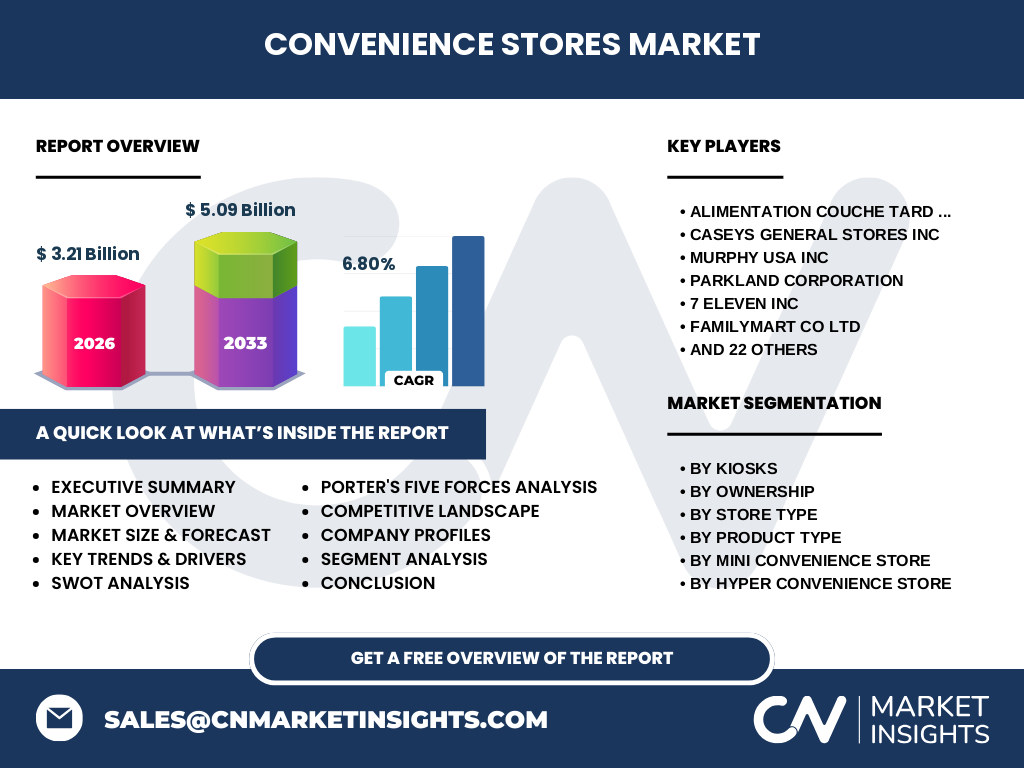
Market overview of the Convenience Stores Market
Our analysis indicates that the Convenience Stores Market reaches a valuation of $3.21 Billion. This sector encompasses vital retail ecosystems ranging from urban kiosks to expansive travel centers, fulfilling consumer demand for speed, accessibility, and high-margin foodservice items regulated by local zoning and trade authorities.
What are the primary factors shaping Convenience Stores Market growth dynamics?
Key market drivers include urban density and high-speed commuter habits, while severe labor shortages and fluctuating fuel distribution costs act as restraints. Industry players navigate regulatory hurdles enforced by agencies like the FDA and OSHA while capitalizing on the massive shift toward fresh foodservice offerings.
Emerging trends and growth patterns in the Convenience Stores Market
The data suggests a rapid evolution toward frictionless checkout technologies and expanded proprietary foodservice menus. Companies like Wawa Inc and Sheetz Inc lead this transformation by converting traditional fuel stops into sophisticated culinary destinations, capturing higher margins away from legacy packaged beverages.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically altered foot traffic patterns, forcing a pivot toward essential goods, contactless delivery, and drive-thru services. While commuter-dependent urban outlets faced severe contractions, roadside and neighborhood locations rebounded aggressively by emphasizing immediate-consumption grocery essentials and digital ordering integration.
Competitive Benchmarking and Strategic Dynamics
The market exhibits a consolidated yet highly competitive landscape dominated by global operators like 7 Eleven Inc and Alimentation Couche Tard Inc. Strategic positioning relies heavily on proprietary supply chains, strategic mergers, and loyalty program ecosystems that lock in high-frequency consumer visits.
Executive Summary of the Convenience Stores Market
Our research projects the Convenience Stores Market to expand from $3.21 Billion to $5.09 Billion by 2033, registering a robust CAGR of 6.80%. Success hinges on omnichannel integration, digital supply chain transparency, and advanced foodservice execution.
Market Forecast for the Convenience Stores Market (2027 to 2033)
Driven by rising urbanization and consumer demand for immediacy, the sector is set to scale steadily. The forecast period anticipates a valuation trajectory reaching $5.09 Billion by 2033, underpinned by a consistent 6.80% CAGR fueled by high-margin foodservice expansion.
Segmentation analysis breakdown
The market is categorized across multiple dimensions: By Kiosks (Mobile Kiosks, Stationary Kiosks); By Ownership (Retail Chain, Independent Retailer); By Store Type (Kiosks, Mini Convenience Store, Limited Selection Convenience Store, Traditional Convenience Store, Expanded Convenience Store, Hyper Convenience Store); By Product Type (Cigarettes And Tobacco, Foodservice, Packaged Beverages, Center Store, Low Alcoholic Beverages, Other Product Types); alongside specific sub-segments for store formats.
Regional market analysis and geographic distribution
Geographic performance varies significantly based on local transit infrastructure and demographic density. North America and Asia-Pacific dominate market consumption, driven by dense commuter networks and high adoption rates of automated retail formats by key regional players like Indomaret and Alfamart.
In-depth regional review of high-growth territories
Urban centers in North America and densely populated metropolitan zones in Asia exhibit the highest per-capita store visits. Regional growth is heavily accelerated by localized expansions from operators such as OXXO and BGF Retail Co Ltd, adapting footprints to local municipal real estate constraints.
Company profiles and strategic positioning
Industry leaders such as Murphy USA Inc, Parkland Corporation, Lawson Inc, and QuikTrip Corporation deploy distinct strategies ranging from fuel-centric volume plays to high-margin fresh food differentiation. These market participants continuously invest in supply chain agility to offset retail margin compression.
Porter's Five Forces analysis of competitive intensity
The industry experiences high competitive rivalry among established chains, while the threat of new entrants remains moderate due to high capital requirements for prime real estate. Bargaining power of buyers is mitigated by convenience, whereas supplier power fluctuates based on tobacco and beverage distributor consolidation.
SWOT analysis of the industry ecosystem
Strengths include ubiquitous real estate footprints and entrenched customer loyalty programs. Weaknesses involve high exposure to minimum wage fluctuations. Opportunities lie in fresh foodservice innovation and EV charging integrations, while threats stem from regulatory tobacco restrictions and digital grocery delivery disruptors.
Value chain analysis from raw materials to end-users
The value chain flows from agricultural and manufacturing suppliers of packaged goods and tobacco, through complex cold-chain logistics and distribution hubs operated by giants like Pilot Company, terminating at consumer-facing storefronts equipped with advanced point-of-sale inventory tracking.
Investment insights and high-potential growth areas
Investors should prioritize formats incorporating electric vehicle charging infrastructure and high-margin proprietary foodservice kitchens. Companies optimizing their supply logistics through predictive analytics offer superior risk-adjusted return profiles over the 2027 to 2033 forecast window.
Conclusion and key industry takeaways
The Convenience Stores Market represents a dynamic, high-growth retail segment projected to reach $5.09 Billion by 2033. Long-term viability depends on strategic shifts away from traditional tobacco reliance toward tech-enabled foodservice and hyper-localized product assortments.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with c-suite executives, exhaustive trade registry data, and secondary macroeconomic indicators from global retail federations to ensure maximum data fidelity.
Scope of the report and coverage parameters
This report covers global market sizing, segment-level breakdowns, and competitive benchmarking across specified store formats, ownership models, and product categories from 2027 to 2033, while excluding unregulated informal street vendors and traditional wet markets.
Recent developments, partnerships, and strategic moves
Recent market activities feature aggressive M&A execution by firms like Alimentation Couche Tard Inc and strategic delivery partnerships forged by regional leaders such as Sheetz Inc and Wawa Inc, enhancing digital ordering capabilities and expanding EV charging networks across major transit corridors.