What is the scope and industry significance of the Online Language Learning Market?
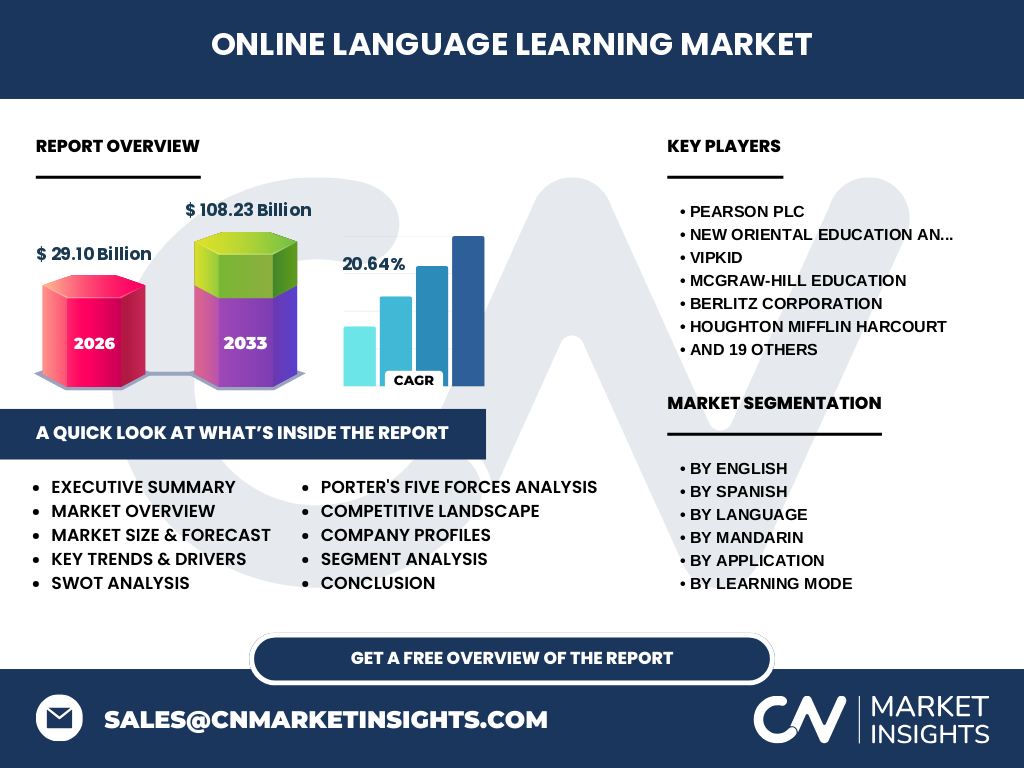
Our analysis indicates that the Online Language Learning Market represents a fundamental restructuring of global linguistic education, valued at $29.10 Billion in 2026. This industry encompasses digital delivery infrastructures—ranging from self-learning apps to live tutoring—governed by strict compliance frameworks such as GDPR and localized data localization mandates in key regions.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Online Language Learning Market?
Growth is heavily propelled by enterprise globalization and cross-border digital commerce. However, infrastructure deficits in emerging economies and regulatory hurdles regarding cross-border data transfer act as primary restraints. Opportunities thrive in specialized modules like IELTS or TOEFL Preparation and Business Spanish.
Emerging trends and growth patterns in the Online Language Learning Market
The data suggests a rapid pivot toward AI-driven conversational partners and micro-learning architectures. Users increasingly favor localized platforms supporting regional dialects like Mandarin and Korean, moving away from rigid desktop software toward hyper-mobile, bite-sized instructional applications.
How did COVID-19 impact the Online Language Learning Market and define its recovery trajectory?
The pandemic served as an unprecedented catalyst, forcing academic institutions and corporate training departments to adopt remote solutions overnight. Our research shows this accelerated digital adoption by nearly a decade, permanently embedding platforms like VIPKid and Duolingo Inc. into mainstream educational procurement.
Competitive landscape of the Online Language Learning Market
Market concentration is moderately fragmented, featuring a mix of hyper-scale application providers and specialized tutoring ecosystems. Industry heavyweights like Pearson plc and EF Education First Ltd. leverage extensive institutional channels, while innovators like Babbel and Busuu capture consumer segments through adaptive learning methodologies.
Executive Summary of the Online Language Learning Market
Driven by robust demand across institutional and individual segments, the market is poised to reach an impressive $108.23 Billion by 2033. Operating at a staggering CAGR of 20.64% from 2027 to 2033, this sector offers unprecedented ROI for strategic investors targeting EdTech innovation.
Online Language Learning Market forecast and trajectory from 2027 to 2033
Our forecasting models project sustained hyper-growth, expanding from the 2026 baseline of $29.10 Billion to $108.23 Billion by 2033. This expansion is sustained by a 20.64% CAGR, fueled by escalating enterprise demand for multilingual talent and standardized testing preparation.
Segmentation analysis across language categories and learning modes
The industry breaks down across several core verticals: By English (covering Beginners, Business, Academic, Conversational, Grammar, and IELTS/TOEFL); By Spanish (Beginners, Business, Conversational, Travel, Grammar, and DELE); By Mandarin (Beginners, Business, Travel, Conversational, HSK, and Grammar); By Other Languages (French, German, Arabic, Italian, Japanese, Portuguese, Korean, Russian, and regional dialects); By Application (Individual and Institutional Learners); By Learning Mode (Self-Learning Apps and Tutoring); and By Language Proficiency Level (Beginner, Intermediate, and Advanced).
Regional market analysis and geographic performance distribution
Geographic performance varies significantly, with North America leading in corporate adoption and institutional spending. Meanwhile, the Asia-Pacific region demonstrates the highest volume growth, driven by massive demand for English and Mandarin proficiency tests among young professionals navigating strict regional labor markets.
In-depth regional review of key markets in the Online Language Learning Market
Asia-Pacific dominates user acquisition metrics, heavily influenced by regulatory shifts in China affecting tutoring ecosystems, prompting companies like New Oriental Education and Technology Group Inc. to pivot toward international markets. Europe maintains steady growth, anchored by multilingual workforce requirements governed by European Union labor mobility directives.
Strategic positioning of leading companies in the Online Language Learning Market
Industry leaders deploy diverse monetization and pedagogical models. Duolingo Inc. captures mass-market consumers via gamified self-learning apps, whereas Cambly Inc. and italki target intermediate-to-advanced users seeking live tutoring. Institutional mainstays like McGraw-Hill Education and Oxford University Press anchor their offerings in academic rigor and curriculum integration.
Porter's Five Forces analysis of the Online Language Learning Market
Competitive rivalry is intense due to low switching costs in consumer apps. Supplier power remains low given abundant freelance tutoring talent. Threat of substitution is moderate, countered only by immersive physical study-abroad programs. Buyer power is high among enterprise clients demanding custom analytics.
SWOT analysis highlighting strategic factors in the Online Language Learning Market
Strengths include scalable digital delivery and high gross margins. Weaknesses involve high customer acquisition costs for consumer apps. Opportunities lie in expanding Business Spanish and HSK Preparation modules for corporate clients. Threats stem from macroeconomic downturns impacting discretionary consumer spending on education.
Value chain analysis from educational content creation to end-users
The value chain originates with linguistic researchers and curriculum designers crafting pedagogical content. This flows through software developers and AI integration specialists who build self-learning apps and tutoring interfaces, ultimately reaching individual and institutional end-users via cloud infrastructure and app distribution networks.
Investment insights and high-potential areas within the Online Language Learning Market
High-potential capital allocation targets B2B SaaS integrations and specialized testing preparation platforms like DELE and IELTS or TOEFL Preparation. Investors should prioritize firms demonstrating high retention rates in institutional segments rather than purely relying on consumer app downloads.
Conclusion and key takeaways for stakeholders
The Online Language Learning Market offers extraordinary growth potential, scaling to $108.23 Billion by 2033. Success in this landscape requires balancing engaging self-learning applications with targeted tutoring solutions tailored to both individual career advancement and rigorous institutional accreditation standards.
Research methodology utilized for Online Language Learning Market analysis
Our baseline estimates are rigorously triangulated by combining trade registry data from major EdTech consortiums, primary stakeholder interviews with chief executive officers of leading platforms like Rosetta Stone Inc. and Babbel, and secondary macroeconomic indicators regarding global internet penetration and corporate training budgets.
Scope of the report and analytical limitations
This report covers global revenue streams generated through digital language instruction, segmented by language, proficiency, application, and learning mode from 2026 through 2033. Limitations exclude informal peer-to-peer exchanges occurring outside monetized platforms and unstructured social media interactions lacking formal curricula.
Recent developments, corporate partnerships, and strategic moves
Recent industry activity highlights aggressive M&A strategies and AI integrations. Platforms like Tandem and HelloTalk have expanded their conversational ecosystems, while enterprises such as Pearson plc forge strategic partnerships with universities to embed automated language proficiency assessment directly into admissions pipelines.