What is the market overview and industry significance of the Offshore Drilling Market?
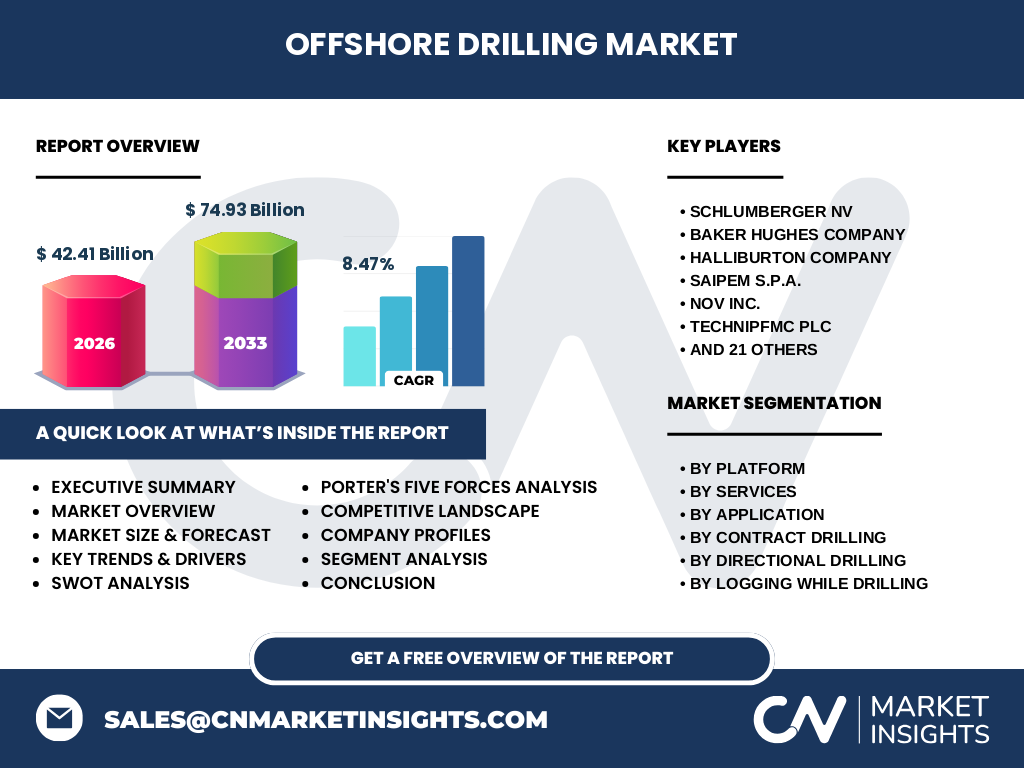
Our analysis indicates that the Offshore Drilling Market valued at 42.41 Billion in 2026 plays a critical role in global energy security. Operating under strict regulatory oversight from bodies like the BSEE and IMO, this sector extracts vital hydrocarbon raw materials from complex marine environments using advanced assets like drillships and semisubmersibles.
Structural Growth Drivers and Restraints Shaping the Offshore Drilling Market
The market faces a dynamic interplay of forces. High global energy demand drives expansion, while stringent environmental mandates from agencies such as the EPA create compliance hurdles. Volatile steel and alloy pricing for heavy tubulars further constrains capital expenditure among operators.
Emerging Trends and Growth Patterns in Offshore Drilling
Technology adoption is accelerating across the sector. Operators increasingly leverage real-time data logging and automated geosteering to optimize well placement. Major service providers like Schlumberger NV and Baker Hughes Company are spearheading these digital transformations to reduce non-productive time offshore.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains and delayed deepwater projects globally. However, our research shows a robust recovery trajectory driven by post-pandemic energy normalization, leading directly to the projected 74.93 Billion valuation by 2033 at a CAGR of 8.47%.
Competitive Benchmarking and Market Concentration
The landscape features intense competition among elite contractors like Transocean Ltd., Valaris Limited, and Noble Corporation plc. Market concentration remains moderate-to-high in ultra-deepwater segments, where high barriers to entry favor firms possessing advanced dynamically positioned drillships.
Executive Summary: Key Findings in the Offshore Drilling Market
Our comprehensive report reveals a robust expansion phase. Driven by deepwater discoveries and technological innovations from firms like TechnipFMC plc and NOV Inc., the market is set for sustained growth, advancing from 42.41 Billion in 2026 to 74.93 Billion by 2033.
Market Forecast and Long-Term Projections (2027 to 2033)
The data suggests sustained acceleration throughout the forecast window. Expanding at a compound annual growth rate of 8.47%, the sector will scale from its 2026 baseline of 42.41 Billion to reach 74.93 Billion by 2033, heavily influenced by ultra-deepwater campaigns.
Segmentation Analysis by Platform, Services, and Application
Market architecture spans diverse operational categories. By Platform: Jack-Up Rigs, Floating, Semisubmersibles, Drillships, and Other Platforms. By Services: Contract Drilling, Directional Drilling, Logging While Drilling, and Measurement While Drilling. By Application: Ultra-Deep Water Drilling, Shallow Water Drilling, and Deep Water Drilling.
Regional Market Analysis and Geographic Performance
Geographic performance varies significantly due to localized maritime regulations and basin maturity. The Golden Triangle—encompassing the Gulf of Mexico, Brazil, and West Africa—dominates capital allocation, while regions like the North Sea face mature asset decline offset by energy transition investments.
In-Depth Regional Review of High-Yield Offshore Basins
Latin America emerges as a prime growth engine, led by pre-salt developments off Brazil supported by entities like Petrobras and service partners. Meanwhile, the Asia-Pacific shallow water market exhibits steady activity driven by national energy security mandates in Southeast Asia.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic advantages. Transocean Ltd. and Seadrill focus heavily on ultra-deepwater floaters, while Shelf Drilling Holdings Ltd. and Borr Drilling dominate shallow-water jack-up deployments. Subsea 7 S.A. and Saipem S.p.A. anchor subsea engineering excellence.
Porter's Five Forces Analysis of the Offshore Industry
Bargaining power of buyers is moderate due to specialized rig scarcity. Threat of substitutes remains low given hydrocarbon dependency. Rivalry among established rig owners is intense, while high capital expenditure requirements successfully suppress the threat of new entrants.
SWOT Analysis of the Offshore Drilling Market
Strengths include unmatched technological capabilities in extreme depths. Weaknesses involve high exposure to commodity price shocks. Opportunities lie in digital automation and frontier basin exploration. Threats stem from aggressive regulatory decarbonization policies and geopolitical supply chain bottlenecks.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw steel and alloy sourcing, progressing through specialized shipyard construction by builders like CIMC Raffles and Keppel Corporation. It flows through equipment manufacturing by NOV Inc., operational deployment by drillers, and final crude delivery to refiners.
Investment Insights and High-Potential Areas
Investors should prioritize technological innovators offering real-time data logging and mud motor monitoring solutions. High-potential opportunities concentrate in ultra-deepwater drillship contracts and digitalization plays that enhance operational safety and minimize carbon footprints.
Conclusion and Strategic Takeaways
The Offshore Drilling Market demonstrates undeniable resilience and growth potential. With a projected expansion to 74.93 Billion by 2033 at an 8.47% CAGR, stakeholders must align strategies with advanced deepwater technologies and stringent environmental compliance.
Research Methodology and Triangulation Techniques
Baseline estimates are meticulously triangulated. Our methodology merges trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from agencies like the EIA and OPEC to ensure absolute analytical rigor.
Scope of the Report and Coverage Parameters
This report evaluates the global Offshore Drilling Market across specified platforms, service types, and applications from 2026 to 2033. Limitations include unforeseen geopolitical disruptions and sudden macroeconomic policy shifts affecting global rig dayrates.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum highlights extensive fleet reactivations and strategic M&A activity. Companies like Noble Corporation plc and Valaris Limited have secured multi-million dollar contract backlogs, while Halliburton Company and Weatherford International plc launch advanced geosteering tools to boost drilling efficiency.