What is the scope and industry significance of the Stones Market?
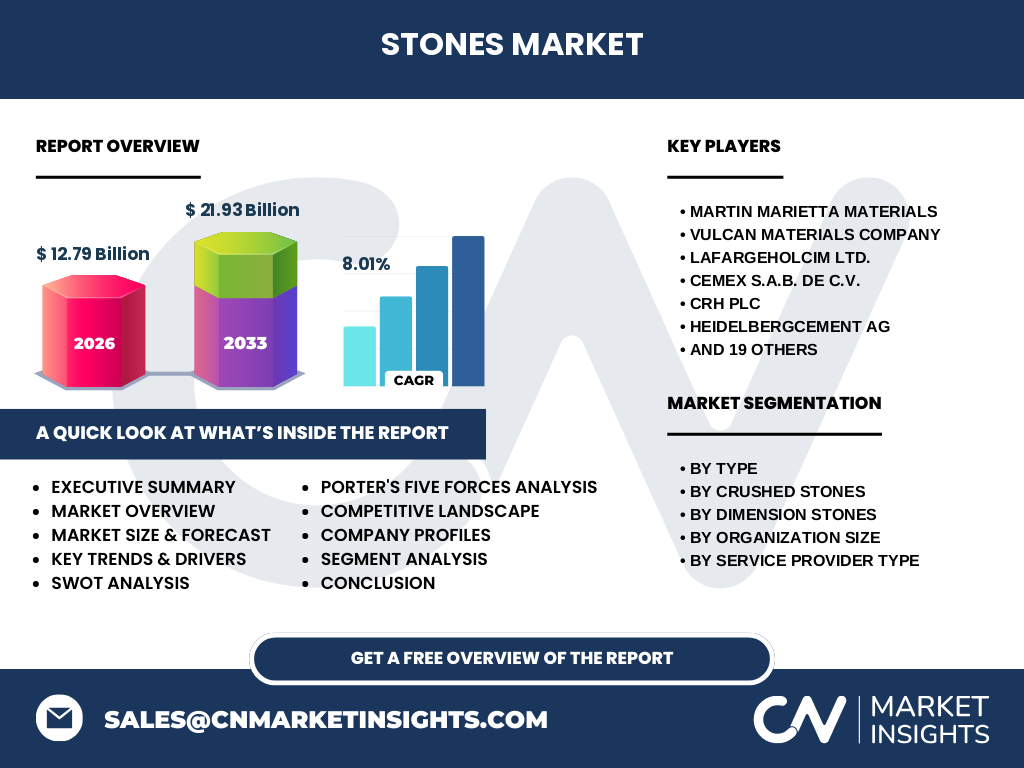
Our analysis indicates that the Stones Market market size is valued at 12.79 Billion in 2026, forming the foundational bedrock of global construction and infrastructure. The industry encompasses both architectural dimension stones and high-volume crushed aggregates, driving urban development, highway construction, and commercial real estate buildouts worldwide.
Structural Growth Drivers and Restraints Shaping the Industry
The primary catalyst is surging global urbanization, which demands robust aggregates from heavyweights like Martin Marietta Materials and Vulcan Materials Company. However, the sector faces severe regulatory headwinds from environmental protection agencies regarding quarry emissions, alongside rising logistics costs tied to heavy freight transport.
The Shift Toward Sustainable Quarrying and Emerging Trends
Industry trends reveal a rapid pivot toward circular economy models, highlighted by the integration of recycled crushed stone. Forward-thinking enterprises are adopting low-carbon extraction techniques and advanced digital dispatch systems to optimize quarry yields, reducing ecological disruption while maintaining high structural integrity standards.
Post-Pandemic Recovery and COVID-19 Impact Analysis
The pandemic severely disrupted global supply chains, halting quarry operations and delaying major infrastructure projects in 2020. Yet, our research shows a resilient V-shaped recovery driven by government-backed stimulus packages targeting public works, which propelled demand back to pre-crisis levels and accelerated automated site operations.
Competitive Benchmarking and Market Concentration
The landscape features high concentration among multinationals such as LafargeHolcim Ltd., CEMEX S.A.B. de C.V., and CRH plc, who dominate through vertically integrated supply chains. Smaller independent contractors compete effectively by serving niche regional markets with specialized architectural limestone and slate products.
Executive Summary of the Stones Market Industry Trends
Our comprehensive Stones Market analysis forecasts a robust trajectory, surging from 12.79 Billion in 2026 to 21.93 Billion by 2033 at a CAGR of 8.01%. Strategic consolidation and heavy investments in sustainable crushing technologies remain the defining imperatives for sustained market dominance.
Long-Term Market Forecast from 2027 to 2033
Driven by aggressive infrastructure spending across emerging economies, the sector is projected to maintain strong momentum, achieving a stellar CAGR of 8.01%. This growth will expand the valuation from its 2026 baseline to 21.93 Billion by 2033, rewarding firms with agile supply networks.
Segmentation Analysis of Dimension and Crushed Stones
The market bifurcates into Dimension Stones (granite, marble, limestone, sandstone, slate) for aesthetics and Crushed Stones (granite, limestone, basalt, gravel, recycled) for structural foundations. Crushed stones dominate volume demand for asphalt and concrete, while dimension stones capture high-value architectural cladding contracts.
Geographic Distribution and Regional Market Performance
Regional performance is heavily skewed toward Asia-Pacific due to aggressive megacity expansions, followed by North America's highway modernization initiatives. European markets exhibit steady demand focused primarily on historical restoration and strict environmental compliance for local quarrying operations governed by regional authorities.
In-Depth Regional Review and Localized Market Constraints
North American operations, anchored by players like Luck Stone Corporation and Granite Construction Inc., face stringent zoning laws and EPA regulations. Conversely, developing markets in Latin America and APAC prioritize volume output over carbon caps, fostering rapid capacity expansion among local producers.
Strategic Positioning of Leading Companies
Industry leaders utilize distinct strategies: HeidelbergCement AG and Boral Limited focus on portfolio decarbonization, while regional specialists like Indiana Limestone Company and Swenson Granite Works leverage heritage branding and exclusive quarry access to command premium pricing in architectural segments.
Porter's Five Forces Assessment of Competitive Dynamics
Bargaining power of buyers is moderate due to standardized aggregate specifications, while supplier power remains low given abundant geological reserves. However, the threat of substitutes like synthetic building materials and high capital barriers for new quarry permits heavily influence industry rivalry.
SWOT Analysis of the Global Stones Market
Strengths include essential utility and vast natural reserves; weaknesses involve high carbon footprints and intense logistical expenses. Opportunities lie in recycled aggregate adoption and green building certifications, while threats stem from tightening environmental legislation and fluctuating heavy construction demand.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with geological prospecting and blast-extraction at quarries operated by firms like Braen Stone and Salado Quarry. Materials undergo crushing, grading, and rail freight transport before reaching commercial contractors, civil engineers, and residential landscapers.
Strategic Investment Insights and High-Potential Areas
Investors should target greenfield recycling facilities and automated quarry management software providers. Companies investing in electrification of heavy mining fleet vehicles and low-emission rotary kilns present the highest potential for long-term valuation appreciation under strict ESG mandates.
Conclusion and Key Takeaways for Stakeholders
The Stones Market industry trends highlight an essential transition toward sustainable, high-volume production. Reaching 21.93 Billion by 2033 requires firms to balance aggressive infrastructure demand with stringent environmental compliance and technological modernization across all operational tiers.
Research Methodology and Baseline Estimation Techniques
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with quarry executives, and secondary macroeconomic indicators from global construction indices. This multi-tiered approach ensures high fidelity in market sizing and growth projections.
Scope of the Report and Coverage Parameters
This report covers global production, consumption, and trade dynamics of dimension and crushed stones from 2026 to 2033. Excluded from this scope are precious gemstone mining and ornamental precious minerals, focusing strictly on construction-grade geological aggregates and architectural slabs.
Recent Industry Developments, Partnerships, and Strategic Moves
Recent milestones include Polycor Inc. expanding its eco-friendly quarry acquisitions and United States Lime & Minerals Inc. investing in automated kiln technologies. These moves underscore a sector-wide push toward operational efficiency, reduced carbon emissions, and expanded geographic footprint.