What is the Paid Membership Supermarket Market overview and industry significance?
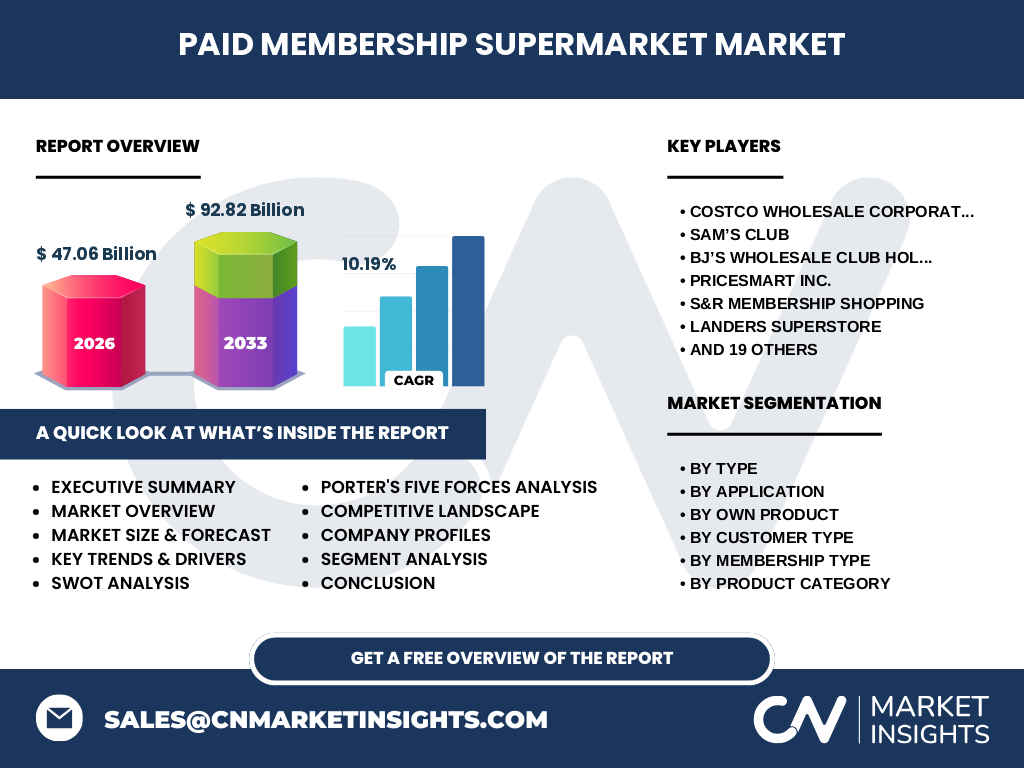
Our analysis indicates that the Paid Membership Supermarket Market represents a high-margin retail model anchored by recurring subscription fees. Valued at 47.06 Billion in 2026, this sector bypasses traditional retail markups by monetizing customer loyalty directly, forcing structural shifts in global supply chain logistics and cold-chain inventory management.
What are the key market drivers, restraints, challenges, and opportunities shaping the Paid Membership Supermarket Market?
The primary growth catalyst is consumer demand for bulk-buying value, offset by supply chain bottlenecks in cross-border freight. Opportunities abound in proprietary logistics integration, enabling players like Costco Wholesale Corporation to optimize freight routing and mitigate rising fuel costs.
Emerging trends and growth patterns in Paid Membership Supermarket Market
The data suggests an aggressive pivot toward digital-first fulfillment models. Members increasingly expect omnichannel integration, pushing warehouse operators to upgrade their regional distribution hubs to handle parallel streams of Online Sales and high-volume Offline Sales seamlessly.
COVID-19 impact analysis and recovery trajectory
The pandemic accelerated consolidation within the sector as consumers sought out trusted bulk suppliers during supply disruptions. Recovery has been defined by rapid digital infrastructure scaling, with market participants leveraging contactless fulfillment and enhanced inventory forecasting to lock in member retention.
Competitive benchmarking and strategic dynamics
Market concentration remains high, dominated by global giants. Sam’s Club and BJ’s Wholesale Club Holdings Inc. utilize sophisticated data analytics on purchasing behavior to negotiate aggressive volume discounts with fast-moving consumer goods manufacturers, widening their competitive moat against traditional grocery models.
Executive summary of the Paid Membership Supermarket Market analysis
This comprehensive research reveals that the Paid Membership Supermarket Market is poised for explosive expansion, driven by subscription-based retail loyalty. Strategic investments in private label development and automated warehousing are critical for capturing high-margin growth through 2033.
Market forecast from 2027 to 2033
Our projections show the market expanding from 2027 to 2033 to reach 92.82 Billion by the end of the forecast period. This trajectory represents a robust 10.19% CAGR, fueled by escalating urbanization and rising disposable incomes across emerging economies.
Segmentation analysis across product and customer categories
Segmentation reveals distinct revenue streams across diverse categories.
- By Type: Own Product and Purchased Product.
- By Application: Online Sales and Offline Sales.
- By Customer Type: Individual, Family, and Corporate accounts driving recurring revenue.
Regional market analysis and geographic performance
Geographic performance highlights North America as the legacy revenue powerhouse, while Asia-Pacific and Latin America demonstrate the fastest adoption rates. Regional constraints, such as real estate scarcity for massive warehouse footprints, are forcing operators in dense urban zones to adopt localized micro-fulfillment strategies.
In-depth regional review of high-potential markets
In developing markets, players like PriceSmart Inc. and S&R Membership Shopping navigate complex import tariffs and localized regulatory hurdles. Their success relies heavily on forging direct relationships with regional agricultural cooperatives to secure stable supply lines.
Company profiles and strategic positioning of leading enterprises
Industry leaders maintain distinct market moats through specialized positioning. Landers Superstore and Makro South Africa leverage localized product assortments and tiered membership structures, ranging from Basic to Very Important Person (VIP) tiers, to maximize customer lifetime value.
Porter's Five Forces analysis of the retail warehouse sector
Bargaining power of buyers is moderate due to membership switching costs, while supplier power is suppressed by the massive purchase volumes commanded by club operators. Threat of new entrants remains low due to high capital expenditure requirements for large-format real estate and distribution networks.
SWOT analysis of the Paid Membership Supermarket Market
Strengths include high customer retention and guaranteed recurring subscription revenue. Weaknesses involve vulnerability to macroeconomic inflation impacting discretionary spending. Opportunities lie in expanding Private Label Groceries, while threats include aggressive discounting by non-membership discount grocers.
Value chain analysis from raw sourcing to end-user fulfillment
The value chain bypasses traditional distribution middlemen, connecting agricultural and manufacturing producers directly to massive warehouse hubs. Companies like Selgros Cash & Carry and Wholesale Club Canada optimize this flow by utilizing proprietary inventory management systems to reduce holding costs.
Investment insights and strategic recommendations
Investors should target operators enhancing their high-margin private label portfolios, particularly in Store-Brand Clothing and Proprietary Home Goods. Furthermore, funding digital infrastructure upgrades will separate market leaders from regional laggards in customer acquisition.
Conclusion and key takeaways for stakeholders
The data confirms that recurring membership models offer superior financial resilience compared to traditional retail. Stakeholders must prioritize data-driven personalization and supply chain resilience to capture maximum value in this expanding landscape.
Research methodology and baseline triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with retail executives, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of both Groceries and Electronics segments.
Scope of the report and analytical boundaries
This report covers global market dynamics across Basic, Premium, and VIP membership tiers from 2026 to 2033. Excluded from this scope are traditional open-market grocery retailers operating without a paid subscription or wholesale club membership requirement.
Recent developments, corporate partnerships, and strategic expansions
Recent strategic moves feature aggressive international expansion by regional heavyweights like City Club and Metro AG Warehouse Club. Investments in automated pick-and-pack robotics within fulfillment centers highlight the industry's continuous drive to optimize labor efficiencies.