What is the scope and industry significance of the Metal-Organic Framework Market?
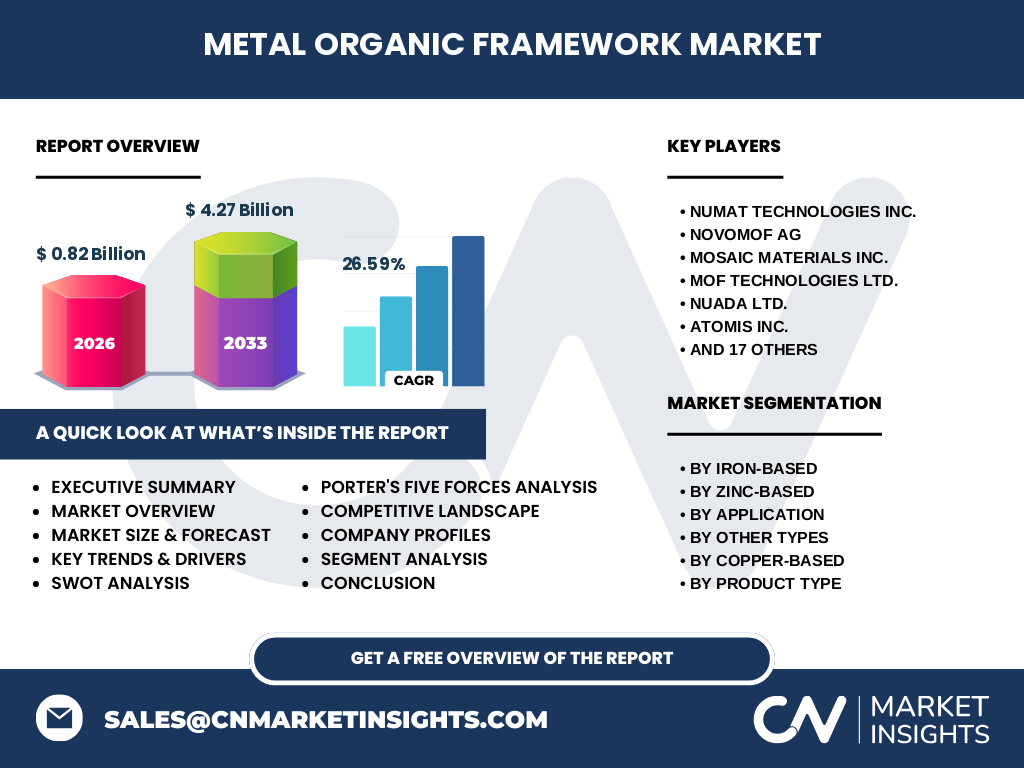
Our analysis indicates that the Metal-Organic Framework Market is valued at 0.82 Billion in 2026. These crystalline porous materials are revolutionizing high-surface-area applications across the chemical and petrochemical sectors, driven by advanced coordination chemistry involving metal ions and organic ligands.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand for hydrogen storage and carbon capture technologies. However, commercialization faces acute hurdles regarding moisture stability and high synthesis costs, directly impacting scalability for industrial-scale deployment by tier-one chemical manufacturers.
Emerging Trends in Advanced Porous Materials
The industry is witnessing a profound shift toward green synthesis pathways and continuous-flow production methods. Innovators like Promethean Particles Ltd. are leading the charge in scalable nanoparticle manufacturing, replacing batch processes to lower per-kilogram production expenses.
Pandemic Recovery and Resilience
Supply chain disruptions during the COVID-19 pandemic severely restricted precursor chemical availability, yet the sector rebounded robustly as national decarbonization mandates prioritized clean energy storage infrastructure, accelerating pilot-plant investments globally.
Competitive Benchmarking and Industry Consolidation
The competitive landscape features a mix of agile startups and chemical giants like BASF SE. Firms such as NuMat Technologies Inc. and MOF Technologies Ltd. leverage proprietary intellectual property to secure dominant positioning in hazardous gas containment.
Executive Summary of Strategic Market Findings
Our research forecasts the Metal-Organic Framework Market to expand from 0.82 Billion in 2026 to 4.27 Billion by 2033, achieving a stellar 26.59% CAGR. This trajectory underscores unprecedented commercial adoption in gas storage and industrial catalysis.
Market Forecast and Valuation Trajectory (2027-2033)
Driven by stringent environmental regulations from bodies like the EPA and European Union, market valuation will scale dramatically to 4.27 Billion by 2033. This exponential growth curve reflects widespread commercial maturation across energy and semiconductor applications.
Segmentation Analysis Across Chemical Classes and End-Uses
The market is segmented by product types including Zinc-Based, Copper-Based, Iron-Based, Aluminum-Based, and Magnesium-Based architectures. End-user verticals span energy, pharmaceuticals, and water treatment, with gas storage leading commercial deployment.
Geographic Distribution and Regional Performance
North America dominates current consumption due to heavy venture capital backing and advanced research clusters, while the Asia-Pacific region exhibits the fastest growth, fueled by massive chemical manufacturing expansions in China, Japan, and South Korea.
In-Depth Regional Review of Industrial Hubs
European markets benefit from strict European Commission carbon pricing mechanisms, spurring localized adoption of carbon capture MOFs. Meanwhile, North American growth is anchored by strategic Department of Energy grants awarded to specialized developers like Mosaic Materials Inc.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic moats. NovoMOF AG specializes in tailored powder synthesis, whereas Atomis Inc. and SyncMOF focus on electronic-grade applications, supplying high-purity crystalline structures to semiconductor fabrication facilities.
Porter's Five Forces Analysis
Bargaining power of raw material suppliers remains moderate, constrained by specialized ligand requirements such as terephthalic or fumaric acids. Threat of substitution is low given the unique pore tunability unmatched by zeolites or activated carbon.
SWOT Analysis of the Global Industry
Key strengths lie in ultra-high surface areas and tunable porosity. Weaknesses involve hydrothermal instability. Opportunities abound in direct air capture, whereas threats stem from intellectual property litigation and scaling bottlenecks.
Value Chain Analysis from Precursors to End-Users
The value chain initiates with petrochemical-derived organic linkers and metal salts, progressing through specialized synthesis, pelletization, and final integration into adsorption systems by specialized engineering firms for end-user deployment.
High-Potential Investment Insights
Investors should target early-stage innovators focusing on water-stable structures and shaped-form MOF pellets. Companies solving structural degradation issues during cyclic pressure swing adsorption represent prime acquisition targets.
Conclusion and Strategic Takeaways
With a projected 26.59% CAGR reaching 4.27 Billion by 2033, the sector offers lucrative opportunities. Success hinges on overcoming stability constraints and scaling continuous manufacturing paradigms to meet industrial demand.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing global customs trade registries, conducting primary interviews with Chief Technology Officers, and analyzing secondary macroeconomic indicators from international chemical associations.
Scope of the Report and Analytical Parameters
This comprehensive report evaluates the global market across chemical types, applications, and geographic regions. Limitations include proprietary pricing confidentiality among private synthesis vendors and shifting regional environmental mandates.
Recent Industry Developments and Commercial Partnerships
Recent milestones include strategic joint ventures between energy conglomerates and pure-play MOF developers to pilot industrial-scale carbon scrubbers at natural gas processing plants, signaling a definitive transition from laboratory discovery to commercial reality.