What is the structural scope and industry significance of the Metal Market?
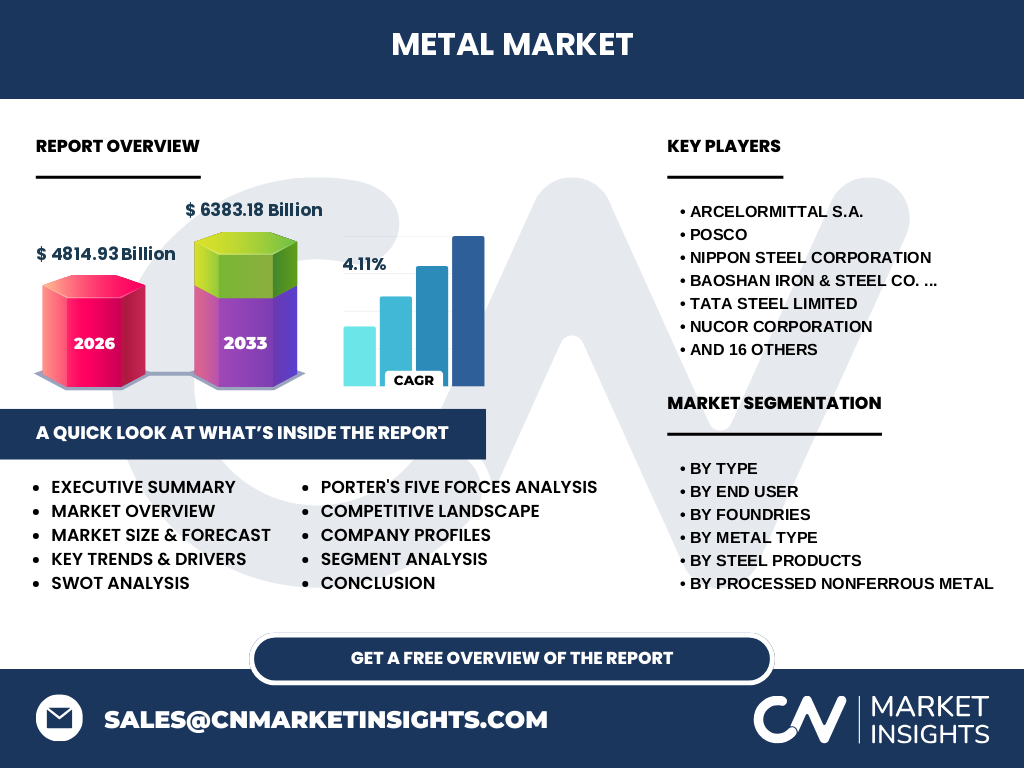
Our analysis indicates that the Metal Market market size stands at 4814.93 Billion in 2026. This foundational sector underpins global manufacturing, energy, and infrastructure through vital materials like iron, steel, and processed nonferrous metals.
Structural Growth Drivers and Restraints
Urbanization and green energy transitions act as primary catalysts for the industry. However, strict environmental mandates and carbon taxation from bodies like the European Union constrain traditional blast furnace operations, forcing producers toward low-emission electric arc furnaces.
The Shift Toward Decarbonized Production in Metal Market Industry Trends
Green steel and circular aluminum production are redefining industry benchmarks. Producers are aggressively investing in hydrogen-based direct reduction and secondary recycling infrastructure to meet stringent ESG targets mandated by global regulatory frameworks.
How did COVID-19 impact the Metal Market recovery trajectory?
The pandemic triggered severe supply chain bottlenecks and temporary smelter shutdowns. Post-pandemic recovery has been propelled by aggressive fiscal stimulus packages directed at infrastructure, driving robust demand across construction and automotive segments.
Competitive Benchmarking and Market Concentration
The landscape features intense competition among global giants like ArcelorMittal S.A., POSCO, and Rio Tinto Group. Market concentration remains moderate-to-high, with top-tier players leveraging vertical integration to hedge against volatile raw material costs.
Executive Summary of Metal Market Analysis
The data suggests the sector is poised for steady expansion, fueled by technological upgrades and surging renewable energy requirements. Strategic consolidation and green technology adoption will dictate market leadership through the next decade.
Metal Market Forecast (2027 to 2033)
Based on our research, the market is projected to expand from 2027 to 2033, reaching 6383.18 Billion by 2033 at a steady CAGR of 4.11%, driven by sustained industrialization across developing economies.
Comprehensive Segmentation Analysis
The sector breaks down by type into Iron and Steel Mills and Ferroalloy, Processed Nonferrous Metal, Processed Alumina and Aluminum, Foundries, and Steel Products. End-user demand is heavily anchored by construction, manufacturing, and electrical applications.
Regional Market Distribution and Performance
Asia-Pacific dominates consumption, driven by massive manufacturing output in China and India. Meanwhile, North America and Europe focus on high-value specialty steel and secondary aluminum processing to comply with strict regional carbon regulations.
In-Depth Regional Review of Key Markets
China remains the epicenter of primary production and consumption, though capacity caps are restraining output growth. North American markets exhibit strong resilience, supported by domestic infrastructure spending and localized supply chain reshoring initiatives.
Strategic Positioning of Leading Companies
Industry leaders such as BHP Group and Glencore plc focus on securing high-grade copper and iron ore assets essential for electrification. Downstream players like Nucor Corporation capitalize on scrap-fed mini-mill agility.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate due to consolidated mining ownership. Threat of substitutes remains low in heavy structural applications, while competitive rivalry is fierce among major integrated mills and low-cost regional producers.
SWOT Analysis of the Metal Sector
Strengths include vast asset footprints and deep supply chain integration. Weaknesses involve high carbon intensity. Opportunities lie in electric vehicle lightweighting metals, while threats stem from geopolitical trade tariffs and energy price volatility.
Value Chain Analysis from Raw Materials to End-Users
Value flows from upstream extraction by firms like Vale S.A. through midstream refining and casting, culminating in downstream fabrication for automotive, aerospace, and construction sectors demanding precise alloy specifications.
High-Potential Investment Insights
Investment capital is shifting toward green hydrogen steel initiatives, copper exploration assets managed by companies like Freeport-McMoRan Inc., and advanced recycling technologies that offer high return potential amid tightening environmental standards.
Conclusion and Strategic Takeaways
Navigating the future requires balancing traditional output volume with aggressive decarbonization. Stakeholders must prioritize technological agility and sustainable sourcing to capture high-margin opportunities through 2033.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing trade registry data, primary stakeholder interviews with executives from firms like Tata Steel Limited, and secondary macroeconomic indicators from global trade bodies.
Scope of the Report and Coverage Parameters
This report covers global metal production, processing, and consumption across specified ferrous and nonferrous categories. Limitations include unforeseen geopolitical trade disruptions and rapid regulatory shifts impacting baseline projections.
Recent Developments and Strategic Industry Moves
Recent activity highlights strategic joint ventures in low-carbon iron production and substantial capital expenditures by companies like Alcoa Corporation toward renewable-powered smelting facilities to future-proof operations against carbon border adjustments.