What is the scope and industry significance of the Front End Reinforcement Bars Market?
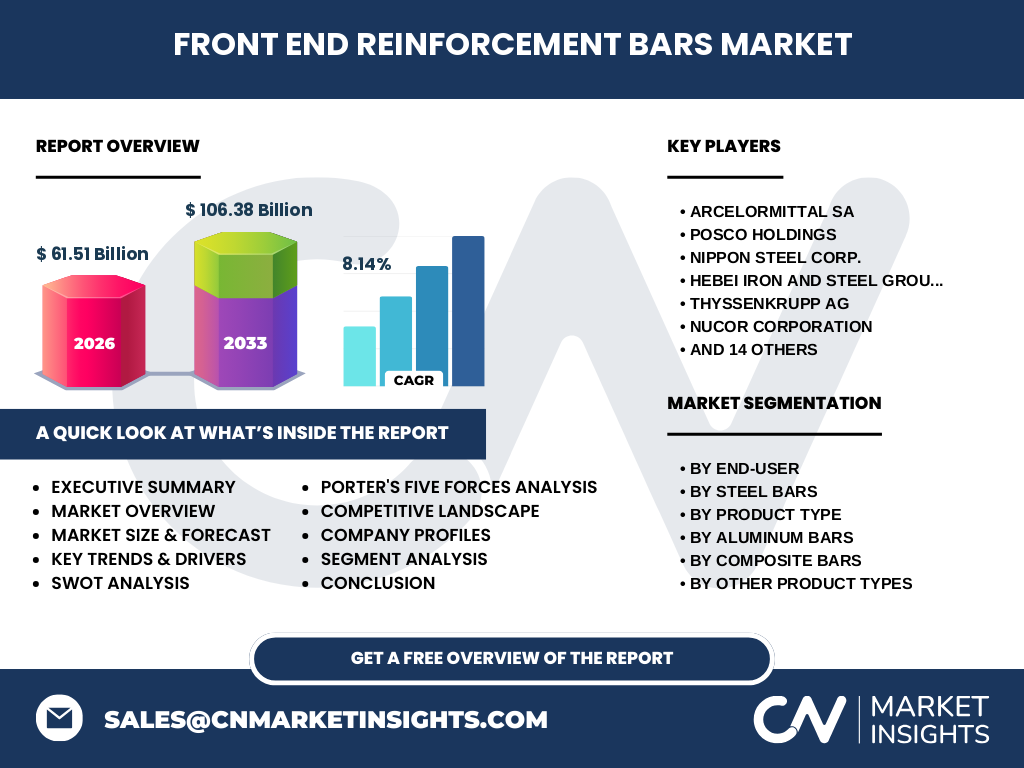
Our analysis indicates that the Front End Reinforcement Bars Market is a vital automotive sub-sector dedicated to structural crash management components. Valued at $61.51 Billion in 2026, these high-integrity crash management systems protect vehicle occupants and critical powertrain elements during frontal impacts, adhering to stringent NHTSA and Euro NCAP crash-test standards.
Structural Growth Drivers and Market Restraints
The market is propelled by strict government safety mandates and consumer demand for lightweight structural profiles. However, raw material volatility in iron ore and coking coal, alongside stringent carbon-neutral targets imposed by the European Union on steelmakers like ArcelorMittal SA, act as notable restraints on short-term margin expansion.
Emerging Trends and Growth Patterns in Front End Reinforcement Bars
The shift toward electrification has ignited a surge in Aluminum Bars and Composite Bars to offset heavy lithium-ion battery packs. Industry leaders like POSCO Holdings and Nippon Steel Corp. are heavily investing in ultra-formable High-Strength Low-Alloy (HSLA) variants to satisfy modern EV chassis requirements.
How did the COVID-19 pandemic impact the Front End Reinforcement Bars Market and its recovery?
Pandemic-era supply chain bottlenecks and semiconductor shortages temporarily destabilized OEM production lines. Our research shows that aggressive post-pandemic fiscal stimuli and rebounding vehicle demand have steered the sector toward a robust recovery, setting the stage for long-term expansion through 2033.
Competitive Benchmarking and Market Concentration
The competitive landscape is consolidated among tier-one metallurgical giants. Companies such as Thyssenkrupp AG, Nucor Corporation, and Tata Steel Limited leverage integrated supply chains and localized service centers to secure long-term OEM supply contracts, creating high entry barriers for independent fabricators.
Executive Summary: Front End Reinforcement Bars Market Synthesis
Driven by accelerating EV adoption and lightweighting initiatives, the Front End Reinforcement Bars Market is projected to reach $106.38 Billion by 2033, expanding at a robust CAGR of 8.14% from 2027. Strategic positioning around advanced metallurgy remains critical for outperforming market benchmarks.
Market Forecast and Valuation Trajectory (2027 to 2033)
The data suggests exponential acceleration as global automotive volumes stabilize. Scaling from $61.51 Billion in 2026 to $106.38 Billion by 2033 at an 8.14% CAGR, growth will be concentrated in high-performance Electric Vehicles (EVs) and lightweight SUV architectures demanding specialized crash structures.
Comprehensive Segmentation Analysis
Segmentation spans multiple critical axes: By End-User (Automobile OEMs, Component Suppliers, Aftermarket), By Steel Bars (HSLA, Stainless, Galvanized), By Product Type (Steel, Aluminum, Composite), and By Application (Passenger Cars, SUVs, LCVs, HCVs, EVs). Each segment dictates specific manufacturing tolerances and metallurgical grades.
Regional Market Performance and Geographic Distribution
Geographic performance mirrors regional automotive manufacturing hubs. Asia-Pacific dominates volume consumption driven by high-output assembly plants in China, South Korea, and India, while North America and Europe focus on advanced Carbon Fiber Reinforced Bars and high-strength aluminum crash structures for premium vehicle segments.
In-Depth Regional Review of Production and Consumption
Regional dynamics are heavily influenced by local environmental regulations and OEM clustering. Proximity to major ports like Shanghai, Rotterdam, and Los Angeles dictates supply chain efficiency for raw inputs utilized by key regional players such as JSW Steel Limited and Hyundai Steel Company.
Strategic Company Profiles and Market Positioning
Industry stalwarts deploy distinct competitive strategies. ArcelorMittal SA and Nippon Steel Corp. focus on proprietary low-carbon steel grades, while Gerdau and Nucor Corporation leverage scrap-based electric arc furnace (EAF) routes to capture sustainability-focused OEM procurement mandates across the Americas.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to consolidated raw material mining, while buyer power is high given the consolidated nature of global automotive OEMs. The threat of substitutes is growing via advanced polymer composites, though high tooling costs preserve steel and aluminum dominance.
SWOT Analysis: Strategic Outlook
Strengths include established metallurgical supply chains and high crash-safety reliability. Weaknesses involve vulnerability to steel price fluctuations. Opportunities lie in EV lightweighting partnerships, whereas Threats stem from macroeconomic slowdowns impacting discretionary vehicle purchases.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw iron ore and bauxite extraction, passing through primary smelting by entities like Kobe Steel Limited and Voestalpine Group, followed by specialized rolling and stamping, before final tier-one assembly and integration into passenger cars and commercial vehicles.
Investment Insights and High-Potential Growth Areas
Investors should target manufacturers specializing in Extruded Aluminum Bars and Basalt Fiber Reinforced Bars. Companies capable of supplying multi-material crash management systems tailored for next-generation electric vehicle platforms present the highest valuation upside over the forecast period.
Conclusion and Strategic Takeaways
The Front End Reinforcement Bars Market is undergoing a structural renaissance. With a projected valuation of $106.38 Billion by 2033, success depends on proactive alignment with lightweighting trends, decarbonization mandates, and strategic tier-one supplier relationships across core automotive corridors.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing international trade registry data, primary stakeholder interviews with automotive procurement executives, and secondary macroeconomic indicators from organizations like the International Organization of Motor Vehicle Manufacturers (OICA).
Scope of the Report and Coverage Parameters
This report evaluates the global Front End Reinforcement Bars Market across specified product types, distribution channels (Direct Sales, Distributors, Online Retail), and vehicle applications from 2026 to 2033. Macroeconomic disruptions outside the automotive domain are excluded to maintain pinpoint sector accuracy.
Recent Industry Developments and Strategic Moves
Recent market activity highlights aggressive green-steel joint ventures and capacity expansions. Market participants like SSAB AB and Shagang Group Company Limited have announced strategic plant upgrades to produce fossil-free steel reinforcement bars, directly catering to tightening ESG requirements from global automotive brands.