What is the market overview and industry significance of the Offshore Support Vessel Market?
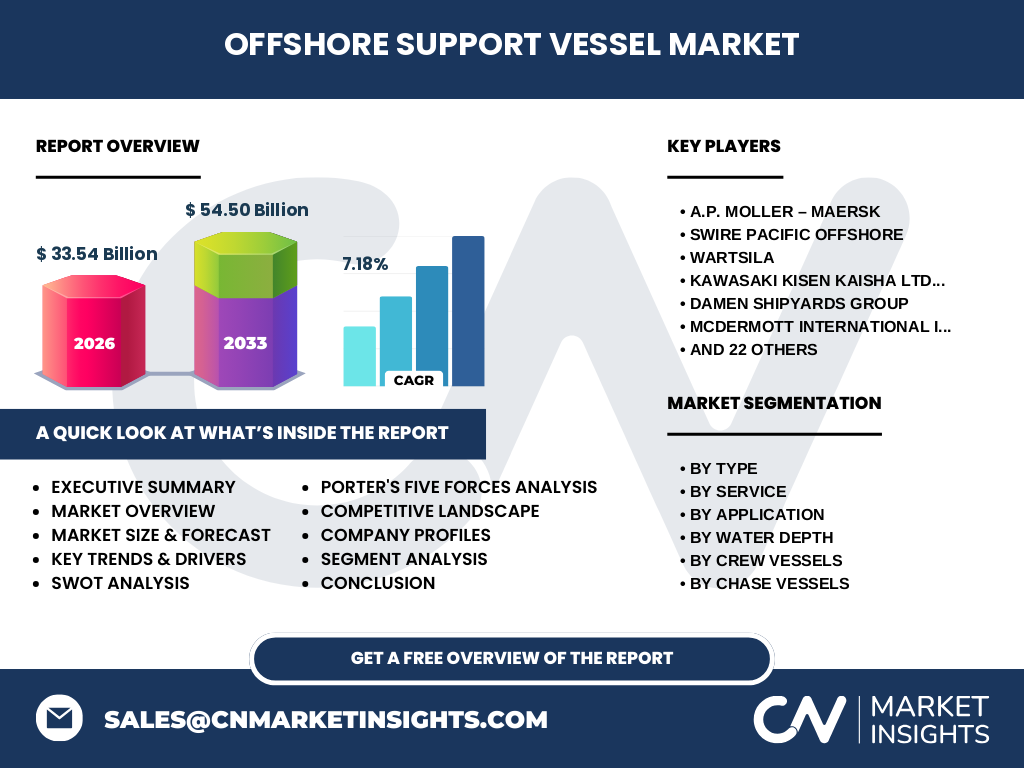
Our analysis indicates the Offshore Support Vessel Market is valued at 33.54 Billion in 2026. It underpins global offshore oil, gas, and renewable energy extraction by supplying essential logistical, marine, and engineering support across hazardous marine environments.
Key market drivers, restraints, challenges, and opportunities shaping the Offshore Support Vessel Market
Growth is propelled by rising deepwater exploration demands, countered by high vessel retrofitting costs and stringent IMO decarbonization mandates. Major opportunities lie in upgrading fleets with DP2/DP3 dynamic positioning systems for ultra-deepwater projects.
Emerging trends and growth patterns in the Offshore Support Vessel Market
The industry is shifting toward hybrid-electric propulsion and digitalized asset tracking. Innovators like Wartsila are leading fuel-efficiency retrofits, directly reducing emissions for operators navigating tightening environmental constraints.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and delayed offshore drilling campaigns globally. Post-COVID recovery has accelerated vessel utilization rates as energy security concerns supersede previous capital expenditure freezes.
Competitive landscape, major players, market concentration, and strategic dynamics
The market features fragmented competition consolidated by major players like Tidewater Inc., Bourbon Corporation SA, and Solstad Offshore ASA. Strategic dynamics center on fleet modernization, M&A activity, and long-term charter contracts with supermajors.
Executive summary of key findings about the Offshore Support Vessel Market
The Offshore Support Vessel Market will expand from 33.54 Billion in 2026 to 54.50 Billion by 2033 at a 7.18% CAGR. Fleet rationalization and green technology adoption remain primary value creators.
Market forecast and projected growth from 2027 to 2033
Driven by subsea developments, the market is projected to reach 54.50 Billion by 2033, expanding at a robust 7.18% CAGR from 2027 onward, supported by sustained capital allocation toward offshore energy.
Segmentation analysis of vessel types, services, and water depths
Segmentation spans Anchor-Handling Tug Supply, Platform Support, and Multipurpose Support Vessels. Technical and survey services dominate service segments, while deepwater and ultra-deepwater applications dictate advanced vessel specifications.
Regional market analysis and geographic performance
Geographic performance is led by offshore-heavy zones in the North Sea, Gulf of Mexico, and Asia-Pacific. Regional variances depend on local regulatory frameworks, mature versus frontier basin status, and proximity to major fabrication hubs.
In-depth regional review of key operational geographies
North America and Europe dominate through stringent safety standards and deepwater developments, while Asia-Pacific presents high-growth opportunities driven by expanding shallow and deepwater E&P activities in Southeast Asian basins.
Company profiles and strategic positioning of leading market participants
Industry leaders like Maersk Supply Service A/S and Damen Shipyards Group leverage specialized engineering and global footprints. Their positioning emphasizes sustainable fleet operations, advanced towing capabilities, and turnkey offshore construction support.
Porter's Five Forces analysis of the industry
Bargaining power of buyers remains moderate-to-high due to vessel oversupply in past cycles. Supplier power is constrained by specialized shipyard capacity, while high capital requirements effectively limit new market entrants.
SWOT analysis of the Offshore Support Vessel Market
Key strengths include advanced dynamic positioning tech; weaknesses involve aging legacy fleets. Opportunities exist in offshore wind logistics, whereas threats stem from macro commodity price volatility and strict carbon taxes.
Value chain analysis from raw materials to end-users
The value chain flows from steel and marine equipment raw materials through shipbuilders like Keppel Corporation, vessel operators, to oil majors and renewable developers utilizing the tonnage for field maintenance.
Investment insights and high-potential areas for stakeholders
High-potential areas include green-fueled Platform Support Vessels and digital maintenance platforms. Investors should target operators with low debt-to-equity ratios and active exposure to deepwater and offshore wind segments.
Conclusion and key takeaways for industry decision-makers
Reaching 54.50 Billion by 2033 proves the sector is transitioning into a high-tech, capital-disciplined growth phase. Decarbonization capability will separate market leaders from distressed operators.
Research methodology for baseline estimates and data triangulation
Our analysis triangulates trade registry data, primary executive interviews across major operators, and macroeconomic indicators from agencies like the EIA to establish reliable baseline estimates and forecast trajectories.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment trends across all major vessel categories, water depths, and end-user applications from 2026 to 2033, excluding localized inland waterway transport fleets and unflagged artisanal vessels.
Recent developments, company announcements, and strategic partnerships
Recent milestones feature Harvey Gulf International Marine LLC expanding LNG-powered fleets and strategic shipyard alliances focused on hybrid retrofit packages designed to meet forthcoming greenhouse gas reduction targets.