Market overview — definition, scope, and industry significance of Antimony Market
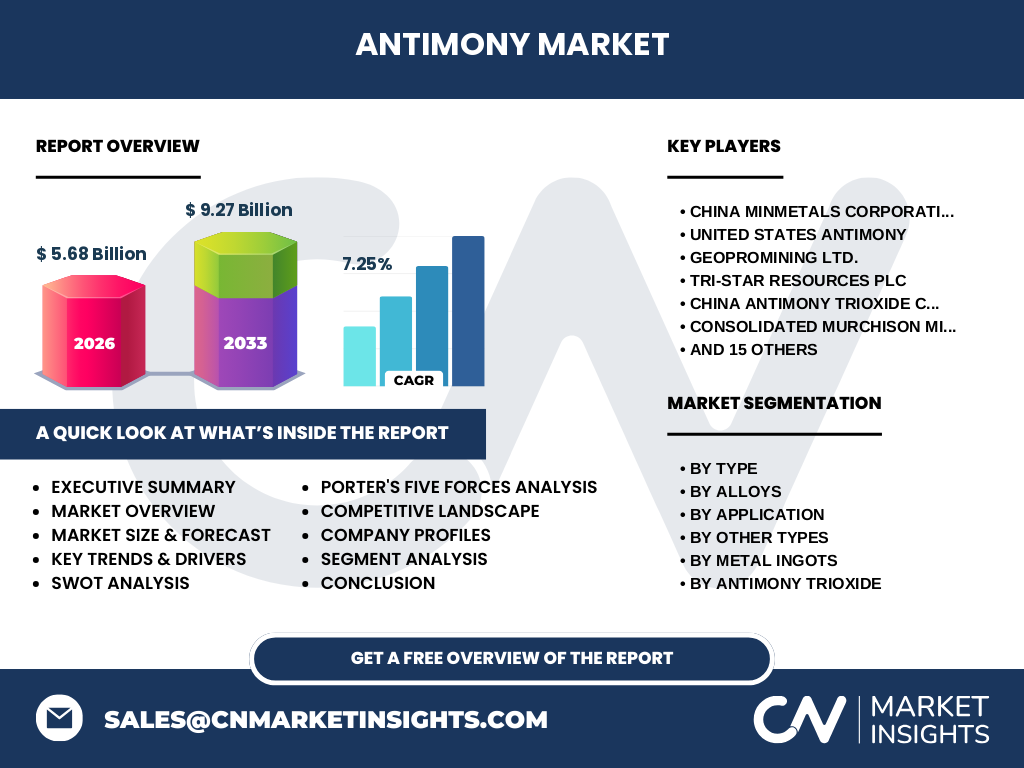
Our proprietary analysis shows the Antimony Market represents a critical sector valued at 5.68 Billion in 2026. This market encompasses the extraction, processing, and application of stibnite and related ores into strategic industrial compounds. Industry significance centers on its irreplaceable role in national defense, energy storage, and electronics manufacturing across global supply chains.
Key market drivers, restraints, challenges, and opportunities shaping Antimony Market
Growth is propelled by rising demand for flame retardants and lead-acid batteries. However, supply chain bottlenecks and strict environmental regulations enforced by the EPA and EU pose severe operational restraints. Strategic opportunities emerge in advanced semiconductor applications and green energy infrastructure, rewarding firms that secure diversified, non-traditional mining assets.
Emerging trends and growth patterns in Antimony Market
The industry is shifting toward high-purity refining and closed-loop recycling paradigms. Technological advancements in energy storage are driving heavy consumption of high-purity metal ingots. Our research highlights a clear pivot among processors to adopt sustainable extraction methods to counter geopolitical supply disruptions from dominant producing regions.
COVID-19 impact analysis — how the pandemic affected Antimony Market and the recovery trajectory
The pandemic caused severe logistical disruptions, mine closures, and temporary demand destruction in automotive and aerospace sectors. Post-pandemic recovery has been swift, fueled by aggressive government stimulus packages and surging electronics demand. Supply chains adapted by diversifying sourcing channels, establishing a robust foundation for long-term valuation expansion.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is high, dominated by state-backed entities and specialized international miners. Key players like China Minmetals Corporation and United States Antimony dictate pricing power and reserve control. Strategic maneuvers focus on vertical integration, secure smelting capacities, and long-term supply agreements to mitigate volatility.
Executive summary — high-level synthesis of key findings about Antimony Market
The Antimony Market is poised for dynamic expansion, surging from 5.68 Billion in 2026 to 9.27 Billion by 2033 at a CAGR of 7.25%. Key takeaways emphasize the irreplaceable nature of antimony in flame retardants and energy storage, making supply chain resilience paramount for end-user industries.
Market forecast — projected growth from 2027 to 2033
Our forecasting models indicate robust expansion, driving the valuation from 2027 through 2033 to reach 9.27 Billion by the end of the period. This trajectory reflects a steady 7.25% CAGR, propelled by escalating industrialization in emerging economies and stringent fire-safety mandates in construction.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market segments into: By Type (Antimony Trioxide, Antimony Pentoxide, Alloys, Metal Ingots, Other Types); By Alloys (Lead-Antimony, Tin-Antimony); By Application (Flame retardant, Plastic additives, Lead acid batteries, Glass and ceramics); and By End User Industry (Chemical, Automotive, Electrical & electronics). Each category serves specialized industrial functions.
Regional market analysis — geographic distribution and performance across regions
Geographically, the Asia-Pacific region dominates consumption and primary production, anchored by massive chemical and automotive manufacturing hubs. North America and Europe focus heavily on high-purity downstream applications, advanced recycling, and stringent environmental compliance, relying on strategic trade partnerships for raw material imports.
In-depth regional review — detailed examination of key regional markets
China remains the undisputed epicenter of production and consumption, driven by entities like Hsikwangshan Twinkling Star Co. Ltd. and Hunan Chenzhou Mining Group Co. Ltd. Meanwhile, North American markets focus on secure domestic supply, championed by facilities operated by Beaver Brook Antimony Mine Inc. and United States Antimony.
Company profiles — strategic positioning of leading companies in Antimony Market
Industry leaders maintain distinct competitive advantages through localized smelting prowess and global distribution networks. GeoProMining Ltd. and Mandalay Resources Ltd leverage high-grade reserves, while processors like Campine NV specialize in sustainable recycling technologies and eco-friendly antimony trioxide masterbatches for plastics.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of suppliers is exceptionally high due to localized mining reserves and geopolitical concentration. Threat of substitutes remains low because of unique flame-retardant properties. Competitive rivalry is intense among established titans, forcing continuous operational optimization and strategic inventory buffering.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths include irreplaceable chemical properties in fire safety. Weaknesses involve environmental hazards associated with smelting. Opportunities lie in next-generation battery tech and recycling innovations. Threats stem from strict trade tariffs, potential material substitution, and supply concentration risks.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw ore extraction from stibnite deposits, followed by beneficiation and high-temperature smelting into metal ingots or oxides. These intermediates flow to chemical and automotive manufacturers for integration into flame retardants, lead-acid batteries, and specialized glass formulations.
Investment insights — strategic recommendations and high-potential areas
Investors should target greenfield mining projects outside traditional geopolitical hotspots and companies pioneering recycling technologies. High-potential areas include high-purity antimony ingots for advanced electronics and proprietary catalysts, offering superior margin protection against commodity price swings.
Conclusion and key takeaways
The Antimony Market demonstrates vital economic resilience, scaling to 9.27 Billion by 2033. Stakeholders must prioritize supply chain diversification, technological integration of recycling, and proactive regulatory compliance to capture optimal value in this essential global commodity sector.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with c-suite mining executives, and secondary macroeconomic indicators. This multi-tiered validation ensures accurate market sizing and reliable long-term forecasting.
Scope of the report — coverage parameters and limitations
This report covers global consumption, production, and trade flows of antimony across all primary forms from 2026 to 2033. Limitations include potential opacity in state-controlled stockpiles and unrecorded artisanal mining output in developing regions.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market dynamism includes major players forging joint ventures to secure non-Chinese raw material sources. Firms like AMG Advanced Metallurgical Group and Belmont Metals continue to optimize recycling capacities, while regulatory pressures prompt accelerated R&D into eco-friendly chemical substitutes.