Market overview and structural scope of the Ice Hockey Equipment Market
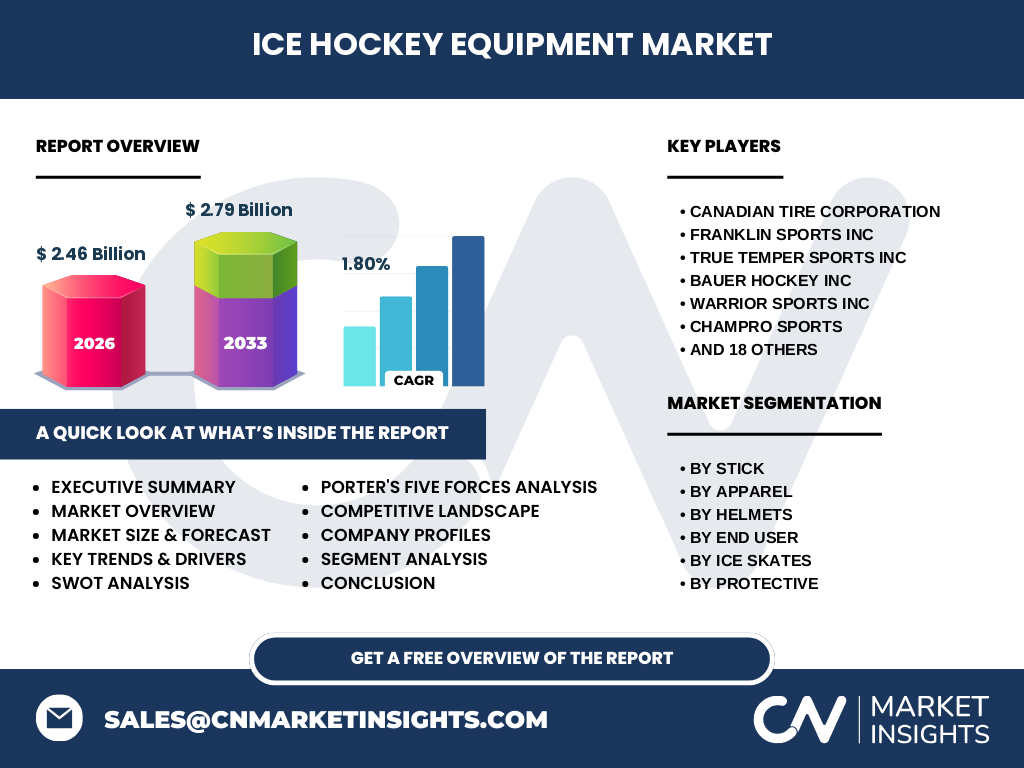
Our analysis indicates the Ice Hockey Equipment Market is valued at 2.46 Billion in 2026, encompassing sticks, skates, protective gear, and apparel governed by strict ASTM and HECC safety standards. This dynamic ecosystem supports B2B procurement for institutional leagues and specialized retailers navigating complex supply chain nodes across North America and Europe.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising youth participation and technological advancements in carbon-fiber layup processes, though constrained by high raw material costs for aerospace-grade resins and stringent safety certification overheads imposed by regulatory bodies like USA Hockey.
Emerging Trends Shaping Industry Trajectories
The shift toward 3D-printed custom skates and lightweight composite sticks is redefining performance metrics. Brands are prioritizing sustainability by integrating bio-resins, directly addressing the growing demand from eco-conscious institutional buyers and professional franchises.
COVID-19 Impact Analysis and Recovery Dynamics
Pandemic-era rink closures severely disrupted inventory turnover across the Ice Hockey Equipment Market. Post-pandemic recovery has been robust, driven by a surge in recreational league registrations and a localized reshoring of manufacturing hubs to mitigate trans-Pacific freight bottlenecks.
Competitive Benchmarking and Market Concentration
The landscape features intense rivalry among category leaders like Bauer Hockey Inc and CCM Hockey AB, who dominate pro-player endorsements. Meanwhile, specialized innovators like True Temper Sports Inc and Warrior Sports Inc leverage advanced materials science to challenge market share.
Executive Summary of Key Industry Findings
Driven by steady consumer demand, the Ice Hockey Equipment Market will expand from 2.46 Billion in 2026 to reach 2.79 Billion by 2033 at a 1.80% CAGR. Strategic consolidation and digital-first fitting solutions represent the primary pathways for margin expansion.
Long-Term Market Forecast from 2027 to 2033
Our forecasting models project steady expansion through 2033, culminating in a market valuation of 2.79 Billion at a steady 1.80% CAGR. This trajectory reflects stable demographic interest in cold-weather sports and sustained institutional investments in municipal arena infrastructure.
Granular Segmentation Analysis by Product and End User
The market is segmented by Ice Skates, Helmets, Sticks (Composite, Wooden, Flex), Protective Gear, Apparel, and Other Equipment Types (Pucks, Training Aids, Equipment Bags). End users span Individual, Institutional, and Promotional channels, each requiring tailored distribution strategies.
Geographic Distribution and Regional Performance
North America remains the undisputed revenue powerhouse, supported by deep-rooted cultural engagement in Canada and the northern United States. Meanwhile, Western Europe exhibits high growth potential, fueled by expanding professional leagues in Scandinavia, Germany, and Switzerland.
In-Depth Regional Review of Core Markets
Regional performance highlights high equipment replacement cycles in traditional hockey strongholds. Logistics hubs near major ports in Vancouver and Hamburg facilitate efficient inventory flow for key distributors servicing localized retail networks and elite training academies.
Strategic Positioning of Leading Industry Players
Key market participants deploy distinct strategies: Bauer Hockey Inc and CCM Hockey AB focus on elite performance gear, while Canadian Tire Corporation commands broad retail reach. Niche innovators like Superfeet Worldwide Inc and Shock Doctor Inc capture high-margin accessories segments.
Porter's Five Forces Assessment of Competitive Pressures
Supplier power remains moderate due to specialized carbon fiber dependencies, whereas buyer power is high among large institutional leagues demanding volume discounts. Threat of substitutes is low given the technical precision required for regulation-compliant protective equipment.
SWOT Analysis of the Ice Hockey Equipment Ecosystem
Strengths lie in strong brand loyalty and patented impact-absorption technologies. Weaknesses involve high tooling costs for custom molds. Opportunities emerge in e-commerce personalization platforms, while threats stem from inflationary pressures on petrochemical raw materials.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with raw resin and carbon fiber sourcing, passing through precision molding and safety testing by bodies like HECC. Finished goods move via multimodal freight to regional distribution centers before reaching online or offline retail storefronts.
Strategic Investment Insights and High-Potential Areas
Investors should target direct-to-consumer digital fitting technologies and sustainable material innovations. Companies incorporating advanced analytics into training aids—such as offerings from Snipers Edge Hockey LLC—are well-positioned for outsized valuation multiples.
Conclusion and Strategic Industry Takeaways
Navigating the Ice Hockey Equipment Market requires balancing premium performance innovation with cost-optimized manufacturing. With a projected valuation of 2.79 Billion by 2033, firms must embrace digital customization and agile supply chains to capture market share.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary executive interviews with C-suite stakeholders across Bauer Hockey and CCM Hockey, and secondary macroeconomic indicators from sports federation participation databases.
Scope of the Report and Coverage Parameters
This report covers global revenue performance for the Ice Hockey Equipment Market from 2026 through 2033. It excludes adjacent ice sports like figure skating apparel and curling accessories, focusing strictly on regulation-grade hockey gear and associated training tools.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic acquisitions and digital fitting rollouts. Companies like Franklin Sports Inc and True Temper Sports Inc have expanded their retail footprints through exclusive league partnerships and direct-to-consumer e-commerce enhancements.