What is the scope and industry significance of the Medical Ceramics Market?
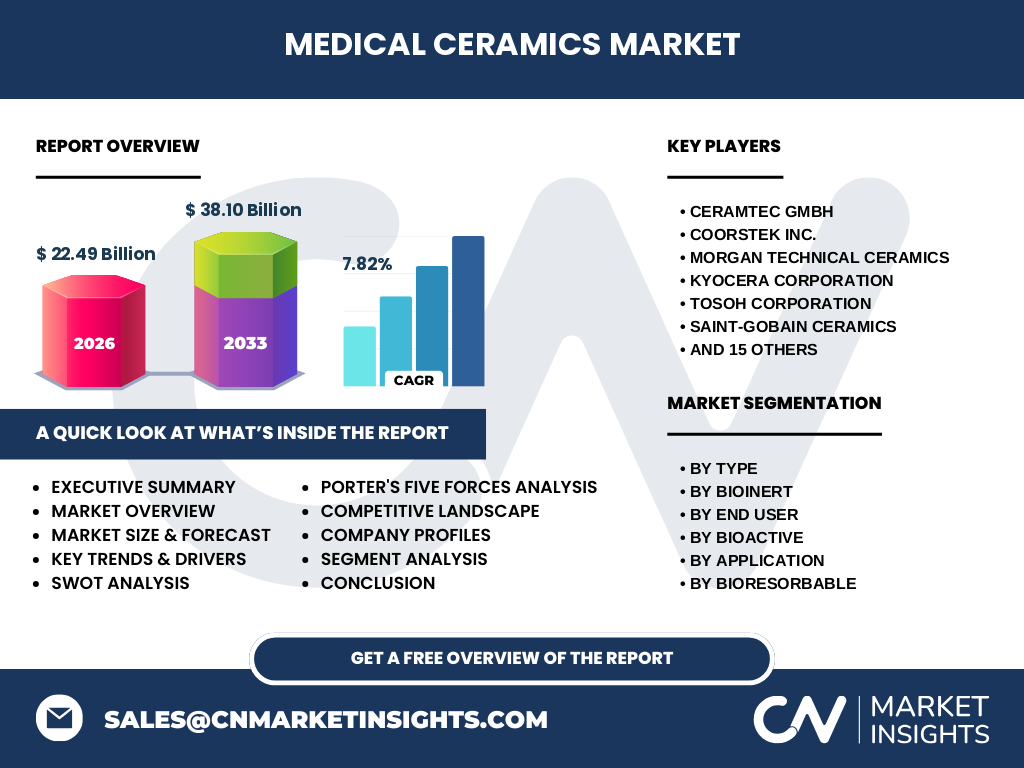
Our analysis indicates that the Medical Ceramics Market encompasses advanced biomaterials utilized in critical clinical interventions. Valued at 22.49 Billion in 2026, this sector drives innovation in biocompatible implants, significantly outperforming traditional metallic counterparts by minimizing wear debris and chronic inflammatory responses.
Structural Growth Drivers and Market Restraints
Growth is propelled by an aging global demographic requiring permanent joint replacements. However, stringent FDA and CE Mark regulatory hurdles alongside brittle fracture risks act as primary restraints, limiting rapid adoption in high-impact structural load-bearing applications.
Emerging industry trends in the Medical Ceramics Market
The market is witnessing a profound shift toward additive manufacturing and 3D-printed bioceramics. This technology allows Admatec BV and peers to produce patient-specific porous scaffolds that dramatically enhance osseointegration compared to traditional subtractive milling methods.
How did COVID-19 impact the Medical Ceramics Market and shape recovery?
Pandemic-era elective surgery cancellations temporarily depressed demand. Yet, robust recovery materialized as hospitals cleared backlogs, validating the long-term resilience of orthopedic and dental supply chains managed by key players like Zimmer Biomet Holdings Inc.
Competitive Benchmarking and Market Concentration
The landscape features high market concentration led by advanced material specialists. CeramTec GmbH and Kyocera Corporation dominate through proprietary powder processing techniques, creating high barriers to entry for emerging competitors lacking extensive sintering infrastructure.
Executive summary of the Medical Ceramics Market
Our research confirms the Medical Ceramics Market is poised for accelerated expansion, reaching 38.10 Billion by 2033 at a robust CAGR of 7.82%. Advanced bioceramics are increasingly replacing metals due to superior corrosion resistance and aesthetic dental integration.
Market forecast from 2027 to 2033
The data projects consistent expansion from 2027 through 2033, scaling up to the 38.10 Billion milestone. This trajectory is underpinned by rising disposable incomes in emerging Asian economies and increasing demand for permanent, hypoallergenic medical implants.
Segmentation analysis across product types and applications
The market divides into Bioinert (Alumina and Zirconia Ceramics), Bioactive (Hydroxyapatite and Bioglass), and Bioresorbable (TCP, BCP, and Calcium Sulfate Ceramics). End users span Hospitals And Clinics and Specialty Centers for dental and orthopedic applications.
Geographic distribution and regional performance
North America maintains revenue dominance due to advanced healthcare infrastructure and early adoption of ceramic femoral heads. Meanwhile, the Asia-Pacific region demonstrates the fastest growth, driven by expanding hospital networks in Japan, South Korea, and China.
In-depth regional review of high-potential markets
European markets exhibit steady demand anchored by strict regulatory harmonization and established medical device manufacturers in Germany and Switzerland. North American growth relies heavily on outpatient joint replacement centers driving high-volume dental and orthopedic ceramic consumption.
Strategic positioning of leading companies in the Medical Ceramics Market
Industry titans like Stryker Corporation and Johnson & Johnson integrate advanced bioceramics into proprietary joint reconstruction systems. Simultaneously, raw material suppliers such as Tosoh Corporation provide high-purity zirconia powders essential for downstream manufacturing precision.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized powder requirements, while buyer power is low given the critical clinical need for approved implants. Threat of substitutes is minimal, restricted by rigorous biocompatibility standards enforced by regulatory bodies.
SWOT analysis of the Medical Ceramics Market
Strengths include exceptional wear resistance and biocompatibility. Weaknesses involve high manufacturing costs. Opportunities lie in bioresorbable scaffolds for bone regeneration, while threats center on raw material price volatility and stringent approval timelines.
Value chain analysis from raw materials to end-users
The value flow originates with chemical synthesis of high-purity powders by firms like Stanford Advanced Materials, progressing through precision shaping and sintering, and culminating in sterile packaging for deployment across hospitals and specialized clinics.
Investment insights and high-potential areas
Investors should target companies specializing in additive manufacturing of bioresorbable ceramics like Tricalcium Phosphate. These segments offer superior margins and align directly with the shift toward personalized, regenerative orthopedic solutions.
Conclusion and key takeaways for stakeholders
The Medical Ceramics Market represents a high-conviction sector characterized by steady secular growth. With the market reaching 38.10 Billion by 2033, early investments in advanced bioactive formulations will yield substantial competitive advantages.
Research methodology and baseline estimation techniques
Our analysis triangulates data by combining exhaustive trade registry records, primary stakeholder interviews with R&D executives across Morgan Technical Ceramics and CoorsTek Inc., and secondary macroeconomic indicators regarding healthcare expenditure.
Scope of the report and coverage parameters
This report covers global consumption of medical ceramics across bioinert, bioactive, and bioresorbable categories from 2026 to 2033. Limitations include localized reimbursement policy shifts and unpredicted regulatory policy changes by international health authorities.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic joint ventures focused on 3D-printable ceramic pastes. Companies like Institut Straumann AG continue to expand their ceramic dental implant portfolios, capitalizing on patient demand for metal-free restorative solutions.