What is the scope and industry significance of the Mobile Commerce Solution Market?
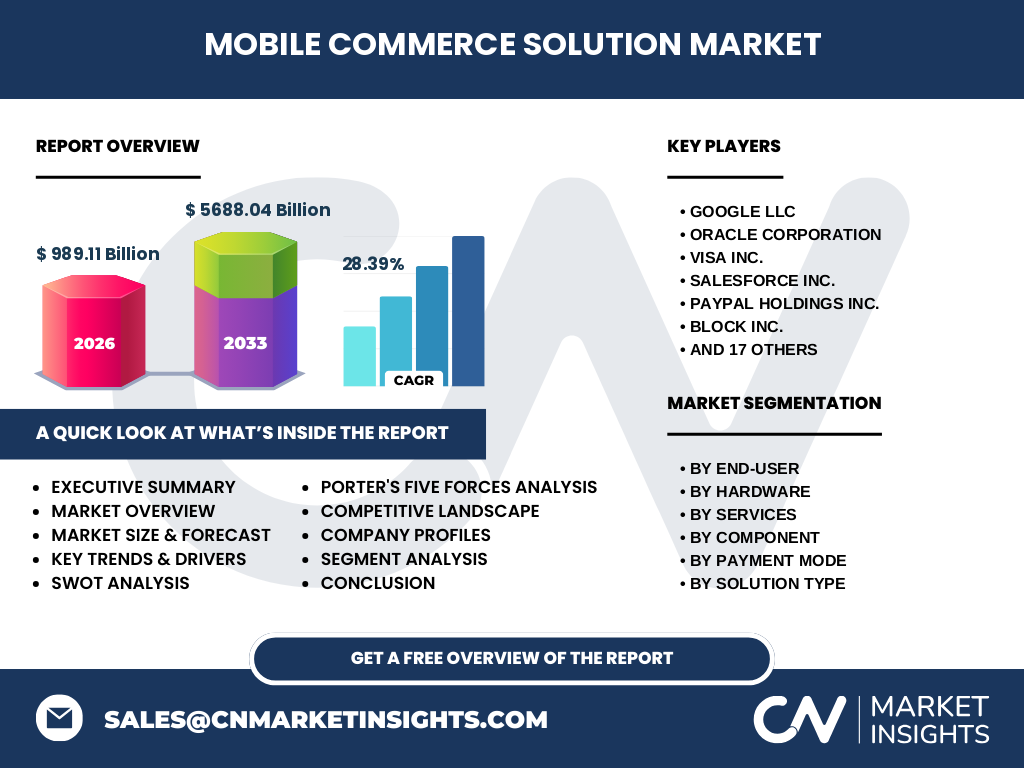
Our analysis indicates that the Mobile Commerce Solution Market size is valued at $989.11 Billion in 2026. This ecosystem encompasses platforms, hardware like Point Of Sale Terminals, and services enabling transactions via smartphones, driven by shifts in consumer digital behavior and regulatory pushes like PSD2 in Europe.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by widespread smartphone adoption and Near Field Communication (NFC) advancements. However, stringent data privacy laws from regulatory bodies like the FTC and GDPR act as restraints. Merchants face integration challenges, yet lucrative opportunities emerge in emerging markets through Direct Carrier Billing.
The Shift Toward Omnichannel Integration and Embedded Finance
Emerging trends reveal a rapid pivot toward unified commerce where Mobile Wallet Solutions merge seamlessly with in-store Point Of Sale Terminals. Innovators like Shopify Inc. and Stripe Inc. are leading this shift by embedding financial services directly into merchant platforms, boosting retention and transaction throughput.
How did the COVID-19 pandemic permanently alter the Mobile Commerce Solution Market trajectory?
The pandemic acted as a massive catalyst, accelerating digital transformation across Retail And E-commerce. Lockdowns forced a permanent behavioral shift toward contactless payment kiosks and mobile shopping applications. The recovery trajectory shows sustained upward momentum, far surpassing pre-2020 baseline projections.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, featuring heavyweights like Google LLC, Visa Inc., and PayPal Holdings Inc. Strategic dynamics involve aggressive M&A activity and ecosystem lock-in. Competitors differentiate through advanced Security And Compliance Consulting and robust Mobile Payment Platforms And Gateways.
Executive Summary of the Mobile Commerce Solution Market
Our comprehensive research underscores a robust CAGR of 28.39% from 2027 to 2033. Total market valuation is projected to skyrocket to $5688.04 Billion by 2033. Stakeholders must prioritize frictionless user experiences and API-first architectures to capture surging demand in M-Retailing.
Market Forecast and Long-Term Projections (2027 to 2033)
The data suggests unprecedented expansion, scaling from the 2026 baseline to an astounding $5688.04 Billion by 2033. Fueled by a consistent 28.39% CAGR, growth will be heavily concentrated in Mobile Shopping Applications and platform implementation services across developing economies.
Segmentation Analysis: End-Users, Hardware, Services, Components, and Payment Modes
The market breaks down by End-User (Retail, Travel, Financial Services, Telecom, Media); Hardware (POS Terminals, Mobile Card Readers, Kiosks, Barcode Scanners); Services (Implementation, Support, Marketing, Security); Components (Platforms, Services, Hardware); Payment Mode (NFC, SMS, WAP, Carrier Billing); and Solution Type.
Geographic Distribution and Regional Market Performance
Regional performance varies due to localized infrastructure and regulatory maturity. North America leads in transaction volume backed by high smartphone penetration, while Asia-Pacific exhibits the fastest growth velocity, driven by rapid digitization in densely populated urban centers and mobile-first consumer bases.
In-Depth Regional Review and Localized Constraints
Examining regional markets reveals distinct hurdles. Europe navigates strict compliance frameworks like GDPR, favoring advanced Security And Compliance Consulting. Meanwhile, Latin America and Southeast Asia face logistical challenges in unbanked sectors, driving high adoption of Direct Carrier Billing and mobile wallet platforms.
Company Profiles and Strategic Positioning
Leading players occupy distinct strategic niches. Adyen N.V. and Stripe Inc. dominate developer-centric payment gateways, while Block Inc. and Toast Inc. bridge hardware and software for SMBs. Affirm Holdings Inc. and Klarna Bank AB capture surging demand for Buy Now, Pay Later (BNPL) integrations.
Porter's Five Forces Analysis of Competitive Intensity
Competitive rivalry is intense among established fintech giants. Bargaining power of buyers is moderate to high due to low switching costs among payment gateways. The threat of substitutes remains low, but new fintech entrants continuously test industry barriers through localized mobile wallet innovations.
SWOT Analysis: Internal Capabilities and External Realities
Strengths lie in ubiquitous smartphone access and advanced API ecosystems. Weaknesses involve vulnerability to sophisticated cyber threats. Opportunities abound in emerging cross-border M-Commerce, while threats include shifting global tax regulations and aggressive antitrust scrutiny by international trade authorities.
Value Chain Analysis from Infrastructure Providers to End-Users
The value chain flows from foundational software developers and hardware manufacturers (producing Barcode And QR Scanners and POS terminals) through payment gateway providers and platform builders, ultimately delivering seamless checkout experiences to end-users in M-Retailing and M-Ticketing.
Investment Insights and High-Potential Growth Pockets
Investors should target niche areas exhibiting high margins, particularly System Maintenance and Support services, and specialized In-App Purchasing Systems. Companies integrating AI-driven Digital Marketing And Analytics within Mobile Commerce Website Builders present exceptional capital appreciation potential.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Mobile Commerce Solution Market represents a transformative commercial frontier. Achieving market leadership requires aligning product roadmaps with the 28.39% CAGR trajectory, investing heavily in robust security frameworks, and capitalizing on the rapid expansion of specialized mobile wallet ecosystems.
Research Methodology and Data Triangulation
Our findings are synthesized using rigorous triangulation. Baseline estimates combine trade registry data from financial authorities, primary stakeholder interviews with C-level executives across Adyen, Stripe, and PayPal, and secondary macroeconomic indicators cross-referenced with regional digital transaction audits.
Scope of the Report and Analytical Parameters
This report covers global market sizing, granular segment breakdowns, and regional forecasts from 2026 through 2033. Limitations include potential unforeseen macroeconomic disruptions, volatile currency exchange fluctuations, and rapidly evolving regional legislative frameworks governing cross-border mobile data transfers.
Recent Developments: Strategic Partnerships, Product Launches, and M&A Activity
Recent industry moves highlight aggressive expansion. Major players like Shopify Inc. and Salesforce Inc. have forged strategic partnerships to enhance omnichannel capabilities. Meanwhile, innovators continue launching advanced mobile-optimized e-commerce platforms to capture shifting consumer preferences toward mobile-first transactions.