Market overview of the Biopharmaceuticals Contract Manufacturing Market
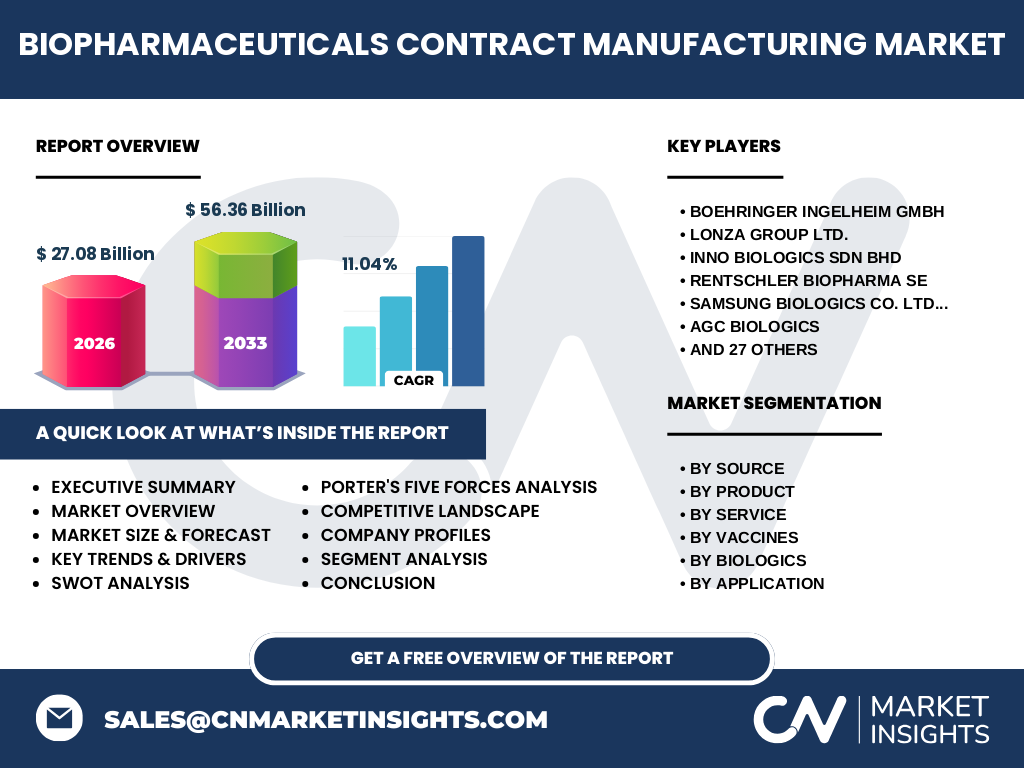
Our analysis indicates that the Biopharmaceuticals Contract Manufacturing Market is valued at 27.08 Billion in 2026. This sector encompasses outsourced manufacturing for mammalian and non-mammalian systems, critical for pharmaceutical innovators navigating complex regulatory frameworks enforced by the US FDA and EMA.
Key market drivers, restraints, challenges, and opportunities
Growth is accelerated by rising demand for biologics and monoclonal antibodies, while high capital expenditures for sterile fill and finish facilities serve as key market restraints. Cold-chain logistics failures remain a primary operational challenge across global shipping corridors.
Emerging trends and growth patterns in Biopharmaceuticals Contract Manufacturing
The shift toward continuous bioprocessing and single-use bioreactors is revolutionizing production efficiency. Industry leaders like Lonza Group Ltd. and WuXi Biologics are heavily investing in modular facilities to drastically reduce batch turnaround times for complex RNAi and gene therapies.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated vaccine manufacturing capacities, reshaping supply chain resilience. Post-pandemic recovery highlights a permanent structural shift toward localized contract development and manufacturing organization (CDMO) partnerships to mitigate future trade disruptions.
Competitive landscape and strategic market dynamics
Market concentration remains moderately fragmented, featuring tier-one innovators such as Boehringer Ingelheim GmbH, Samsung Biologics Co. Ltd., and Catalent Inc. These players leverage strategic site expansions and cutting-edge analytical testing services to secure long-term clinical and commercial supply agreements.
Executive summary of the Biopharmaceuticals Contract Manufacturing Market
Driven by robust pipelines in recombinant proteins and biosimilars, our research projects the market to reach 56.36 Billion by 2033 at an impressive CAGR of 11.04%. CDMOs offering integrated analytical and QC studies are best positioned to capture market share.
Market forecast from 2027 to 2033
Between 2027 and 2033, the market will experience unprecedented expansion from its 2026 baseline of 27.08 Billion up to 56.36 Billion. This trajectory is underpinned by surging outsourcing penetration rates among emerging biotech firms lacking internal GMP manufacturing infrastructure.
Segmentation analysis across product, service, and source categories
The market segments by source (mammalian, non-mammalian), product (biologics, monoclonal antibodies, vaccines, antisense, RNAI, molecular therapy, biosimilars), and service (process development, fill and finish, analytical QC, packaging). Mammalian expression systems continue to dominate due to complex human protein folding requirements.
Regional market analysis and geographic performance
North America and Europe currently dominate revenue generation, supported by established biotech hubs and stringent compliance standards set by the EMA and FDA. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by state-of-the-art facilities in South Korea and China.
In-depth regional review of key manufacturing hubs
South Korea has emerged as a global biomanufacturing powerhouse through aggressive capacity investments by firms like Samsung Biologics. Concurrently, European hubs anchored by Rentschler Biopharma SE and FUJIFILM Diosynth Biotechnologies specialize in high-value clinical trial supply and advanced cell and gene therapies.
Company profiles and strategic positioning of leading players
Industry giants like Thermo Fisher Scientific Inc., Merck KGaA, and Pfizer Inc. dominate through end-to-end service offerings spanning from early-stage cell line development to commercial bulk drug substance manufacturing and specialized fill-finish operations.
Porter's Five Forces analysis of the biopharma CDMO sector
Supplier power remains moderate due to specialized single-use bioreactor component needs, whereas buyer power is high given the multitude of established CDMO options. The threat of new entrants is low owing to prohibitive GMP facility validation costs and stringent regulatory oversight.
SWOT analysis of the Biopharmaceuticals Contract Manufacturing Market
Strengths include highly specialized technical expertise and scalable production capacities. Weaknesses involve complex technology transfers. Opportunities lie in emerging biosimilar markets, while threats include shifting intellectual property regulations and geopolitical trade tensions impacting raw material sourcing.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream raw material suppliers providing specialized media and cell lines, progressing through CDMO-executed fermentation and purification stages, and culminating in downstream fill-finish operations managed by packaging experts like JRS Pharma GmbH & Co. KG.
Investment insights and high-potential growth areas
Investors should prioritize CDMOs offering integrated mRNA, cell therapy, and viral vector manufacturing capabilities. Companies possessing proprietary continuous processing technologies and robust analytical QC frameworks offer superior long-term valuation growth potential.
Conclusion and key takeaways for industry stakeholders
The Biopharmaceuticals Contract Manufacturing Market is entering a golden age of robust 11.04% CAGR growth. Strategic outsourcing is no longer merely a cost-saving measure but a vital technological necessity for navigating modern biopharmaceutical development complexities.
Research methodology and baseline estimation techniques
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-level biopharma executives, and secondary macroeconomic indicators sourced from global health authorities and regulatory filing databases.
Scope of the report and coverage parameters
This report covers global revenue estimations and volume forecasts from 2027 through 2033, analyzing mammalian and non-mammalian expression systems, therapeutic product classes, and outsourced service models across North America, Europe, Asia-Pacific, and Rest of World.
Recent developments, partnerships, and strategic expansions
Recent market activity is highlighted by aggressive facility expansions and strategic acquisitions among top-tier CDMOs. Companies are aggressively scaling up single-use manufacturing lines to address surging demand for complex monoclonal antibodies and personalized molecular therapies.