Market overview of the Optical Goods Stores Market
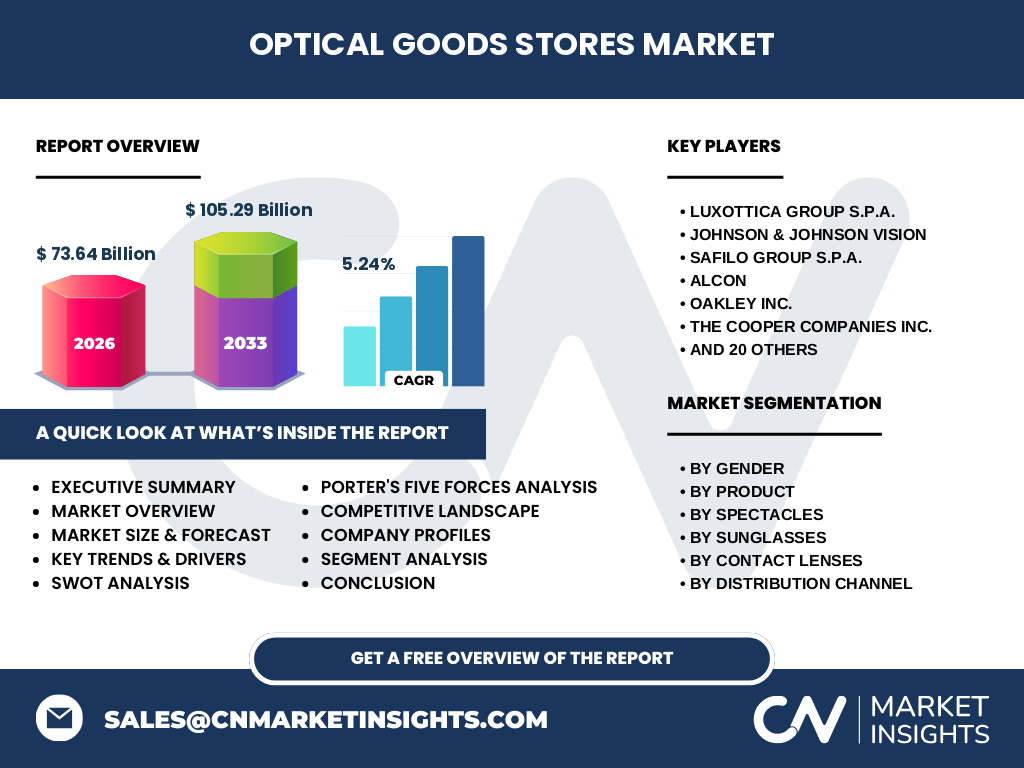
Our analysis indicates the Optical Goods Stores Market encompasses retail and clinical distribution of corrective and protective eyewear. Valued at 73.64 Billion in 2026, the industry significantly impacts global healthcare by addressing visual impairments through specialized storefronts and digital channels.
What are the key market drivers, restraints, challenges, and opportunities shaping the Optical Goods Stores Market?
Growth is driven by aging demographics increasing presbyopia rates, while stringent medical device regulations by bodies like the FDA act as a restraint. Digital eye strain from screens presents a major opportunity for blue light blocking products, though supply chain bottlenecks for raw optical polymers remain a primary challenge.
Emerging trends and growth patterns in Optical Goods Stores Market
The shift toward direct-to-consumer digital integration is transforming the Optical Goods Stores Market industry trends. Innovators like Warby Parker and Zenni Optical leverage virtual try-on technology, while traditional clinics expand into customized multi-focal contact lens fittings to capture high-margin recurring revenue.
COVID-19 impact analysis on the Optical Goods Stores Market and recovery trajectory
The pandemic severely disrupted brick-and-mortar storefront traffic, forcing rapid digital pivots. Our research confirms the recovery trajectory accelerated past pre-pandemic levels as tele-optometry gained regulatory acceptance and consumers redirected discretionary income toward premium blue light blocking glasses and daily disposable contact lenses.
Competitive benchmarking and strategic dynamics in the Optical Goods Stores Market
Market concentration is high, anchored by conglomerates like Luxottica Group S.p.A. and Essilor International SAS integrating frame manufacturing with retail chains like MyEyeDr. Independent stores compete through localized service, while giants leverage massive supply chain economies of scale and proprietary lens technologies from Hoya Corporation.
Executive summary of the Optical Goods Stores Market research findings
The Optical Goods Stores Market market size stands at 73.64 Billion in 2026, projected to expand to 105.29 Billion by 2033 at a 5.24% CAGR. Strategic investments in e-commerce omnichannel infrastructure and personalized clinical care represent the core pathways for outperforming the broader retail sector.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the sector will scale from 2027 through 2033 to reach 105.29 Billion, driven by a steady 5.24% CAGR. This expansion is underpinned by rising disposable incomes in emerging Asian economies and surging demand for premium polarized sunglasses and toric lenses.
Segmentation analysis across gender, product, spectacles, sunglasses, contact lenses, and distribution channels
Segmentation spans multiple vectors: Gender (Men, Women, Unisex); Product (Spectacles, Sunglasses, Contact Lenses); Spectacles (Prescription, Reading, Blue Light, Safety); Sunglasses (Prescription, Polarized, Fashion, Sports); Contact Lenses (Soft, Rigid Gas Permeable, Toric, Multifocal); and Distribution Channel (E-Commerce, Brick and Mortar).
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America leading in value share due to high vision insurance penetration. Meanwhile, Asia-Pacific demonstrates the fastest growth velocity, propelled by escalating myopia rates among urban youth and expanding retail infrastructure by regional optical chains.
In-depth regional review of key international markets
North America benefits from established clinical networks like Vision Source, whereas Europe maintains strong demand for luxury frames produced by Italian houses such as Marcolin and Safilo Group S.p.A. Emerging markets in Latin America and APAC show accelerated adoption of affordable e-commerce distribution channels.
Company profiles and strategic positioning of leading optical enterprises
Industry leaders maintain distinct strategic positioning. Alcon and Johnson & Johnson Vision dominate advanced contact lenses, while Essilor International SAS and Carl Zeiss AG lead optical lens manufacturing. Retailers like National Vision Holdings Inc. and Fielmann AG capture mass-market volume through value-oriented pricing.
Porter's Five Forces analysis of the optical goods ecosystem
Supplier power is moderate, controlled by specialized polymer and lens coating chemical producers. Buyer power is high due to transparent online pricing. Threat of substitution remains low for prescription wearers, but rivalry is intense among branded frame designers and e-commerce disruptors.
SWOT analysis for stakeholders in the Optical Goods Stores Market
Strengths include high customer retention for eye exams; weaknesses involve high inventory holding costs for frames. Opportunities lie in telehealth optometry integration, while threats stem from direct-to-consumer counterfeit eyewear and shifting macroeconomic retail spending pressures.
Value chain analysis from raw materials to end-users
The value chain originates with raw optical glass and petroleum-based acetate resin suppliers. It flows through precision grinding laboratories operated by firms like Shamir Optical Industry Ltd., before reaching end-users via brick-and-mortar storefronts or automated e-commerce fulfillment centers.
Investment insights and high-potential areas for capital allocation
Investors should target omnichannel platforms combining physical eye exams with seamless digital ordering. High-margin product categories like custom multifocal contact lenses and sustainable eco-friendly spectacle frames offer superior yield potential over generic inventory.
Conclusion and key takeaways for industry decision-makers
Reaching 105.29 Billion by 2033, the market rewards adaptability. Companies that successfully bridge clinical eye care diagnostics with frictionless digital e-commerce experiences will capture disproportionate market share in this expanding landscape.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with optometrists and supply chain executives, and secondary macroeconomic indicators from global health organizations to ensure robust, verifiable market sizing.
Scope of the report and coverage parameters
This report covers global revenue streams for optical retail and wholesale sectors through 2033. Excluded from this specific scope are surgical ophthalmology equipment and pharmaceutical eye drops, focusing strictly on corrective and protective optical goods stores and channels.
Recent developments, company announcements, and strategic partnerships
Recent market activity features aggressive acquisitions of independent practices by private equity-backed groups like MyEyeDr., alongside major product launches in smart connected eyewear and sustainable biodegradable frame materials by innovators such as Silhouette Group and Marcolin.