What is the market overview and industry significance of the FCC Catalyst Market?
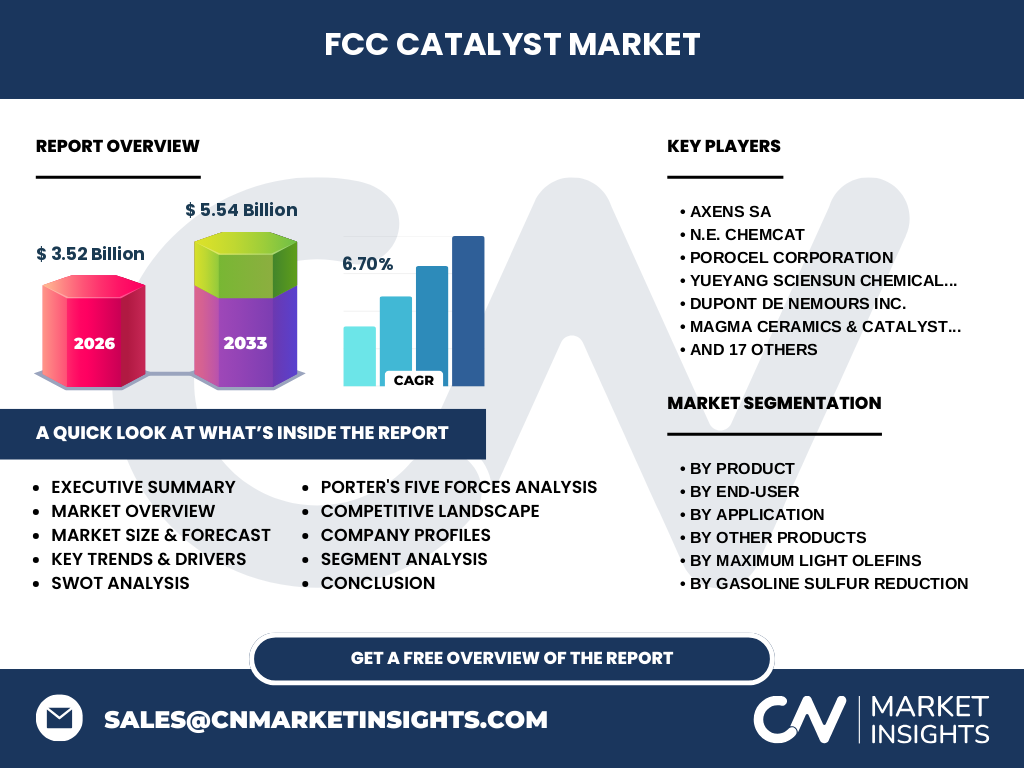
Our analysis indicates the FCC Catalyst Market reaches 3.52 Billion in 2026, serving as the backbone for modern fluid catalytic cracking units in petroleum refining. These specialized aluminosilicate materials and zeolites drive the conversion of heavy gas oils into high-octane gasoline, light olefins, and middle distillates, making them indispensable for optimizing refinery yield structures amidst shifting global fuel demands.
Structural Growth Drivers and Market Constraints Shaping the Sector
Stringent environmental regulations limiting gasoline sulfur content serve as a primary catalyst for technological upgrading. Refiners must adopt advanced hydrodesulfurization catalysts to meet Euro VI and Tier 3 standards. However, high capital expenditures for residue upgrading and feedstock volatility present persistent hurdles for operators in developing economies.
Emerging Trends and Zeolite Innovation Patterns
The shift toward petrochemical integration drives robust demand for maximum light olefins production via ZSM-5 additives and zeolite-based catalysts. Refiners increasingly prioritize specialized formulations that boost propylene and ethylene yields directly from vacuum gas oil, capturing higher margins away from traditional gasoline pools.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic induced a sharp contraction in jet fuel and gasoline consumption, forcing temporary FCC unit shutdowns worldwide. Recovery has been spearheaded by targeted debottlenecking and a rebound in mobility, steering refineries toward high-activity catalysts designed to maximize middle distillates and restore pre-crisis operational throughputs.
Competitive Landscape and Strategic Consolidation Dynamics
The market exhibits a consolidated structure dominated by global heavyweights like Albemarle Corporation, W.R. Grace Company, and BASF SE. These market leaders leverage extensive patent portfolios in specialty catalysts and additives to maintain pricing power, while regional players like PetroChina Catalyst Company capture domestic share.
Executive Summary: Key Findings and Market Projections
Our comprehensive research underscores a robust 6.70% CAGR from 2027 to 2033. The FCC Catalyst Market is projected to surge from 3.52 Billion in 2026 to 5.54 Billion by 2033. This expansion is underpinned by stringent fuel quality mandates and rising petrochemical co-production requirements across complex refineries.
Market Forecast and Revenue Trajectory Through 2033
Based on our econometric modeling, the valuation will expand systematically, driven by residue upgrading projects in the Middle East and Asia-Pacific. Reaching 5.54 Billion by the end of the forecast period, growth will accelerate as refiners process heavier, more contaminant-laden crude slates requiring advanced equilibrium catalyst management.
Segmentation Analysis: Products, End-Users, and Applications
Segmentation is categorized by product lines including Gasoline Sulfur Reduction, Maximum Bottoms Conversion, and Maximum Light Olefins. End-users span refineries and environmental facilities, processing residue and vacuum gas oil feedstocks. Specialty catalysts and ZSM-5 additives provide critical margin-enhancing capabilities for complex asset configurations.
Regional Market Analysis and Geographic Performance Distribution
Asia-Pacific dominates consumption, fueled by massive refining capacity additions in China and India. Meanwhile, North America and Europe focus on high-margin specialty catalysts for sulfur reduction and bottoms conversion, navigating mature yet highly regulated refining landscapes that demand superior product innovation.
In-Depth Regional Review of High-Growth Refining Hubs
The Middle East exhibits exceptional growth rates as national oil companies upgrade refining complexes into integrated petrochemical hubs. Access to heavy sour crude necessitates specialized maximum bottoms conversion catalysts, positioning regional operators as primary targets for global technology licensors.
Company Profiles and Strategic Positioning of Industry Leaders
Market participants such as Axens SA, Haldor Topsoe, and Johnson Matthey differentiate through proprietary hydrocracking and isomerization technologies. Albemarle and W.R. Grace maintain leadership via customized technical services, ensuring refinery-specific yield optimization and superior attrition resistance under severe regenerator conditions.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate due to the high switching costs associated with changing FCC catalyst formulations. Threat of new entrants is low, guarded by intensive R&D requirements, strict environmental compliance, and established intellectual property moats held by incumbents like Universal Oil Products.
SWOT Analysis of the Global FCC Catalyst Sector
Strengths lie in high catalytic efficiency and customized formulations; weaknesses involve vulnerability to raw material price fluctuations like rare earth elements. Opportunities emerge in petrochemical integration, while threats stem from accelerating electric vehicle adoption reducing long-term transportation fuel demand.
Value Chain Analysis from Raw Materials to Refinery End-Users
The value chain flows from rare earth mining, silica, and alumina sourcing to precision chemical synthesis by manufacturers like Clariant AG and Arkema S.A. Final value is captured at the refinery scale, where technical support teams optimize equilibrium catalyst performance to maximize throughput.
Investment Insights and High-Potential Growth Pockets
Investors should target manufacturers specializing in maximum light olefin additives and low-emission residue cracking technologies. Strategic partnerships with regional refiners in developing markets offer defensive moats against tightening environmental regulations and shifting global mobility patterns.
Conclusion and Strategic Takeaways for Industry Stakeholders
The FCC Catalyst Market offers compelling growth, expanding to 5.54 Billion by 2033 at a 6.70% CAGR. Success requires continuous investment in specialty formulations that address both clean fuel standards and the profitable conversion of heavy refinery bottoms into high-value petrochemical intermediates.
Research Methodology and Baseline Triangulation Techniques
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with refinery managers, and secondary macroeconomic indicators. Bottom-up market sizing is cross-verified with top-down crude run capacities to ensure high fidelity across all regional forecasts.
Scope of the Report, Coverage Parameters, and Limitations
This report covers global revenue estimations from 2026 to 2033 across specified product segments, applications, and end-users. Limitations include unforeseen geopolitical disruptions to rare earth supply chains and sudden shifts in global petroleum product consumption patterns.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum features collaborative R&D agreements between catalyst developers and major refiners to commercialize next-generation attrition-resistant zeolites. Companies like Rive Technology and Zeolyst International continue to advance mesoporous material architectures to improve heavy oil accessibility and conversion efficiency.