What is the market overview and scope of the Baryte Market?
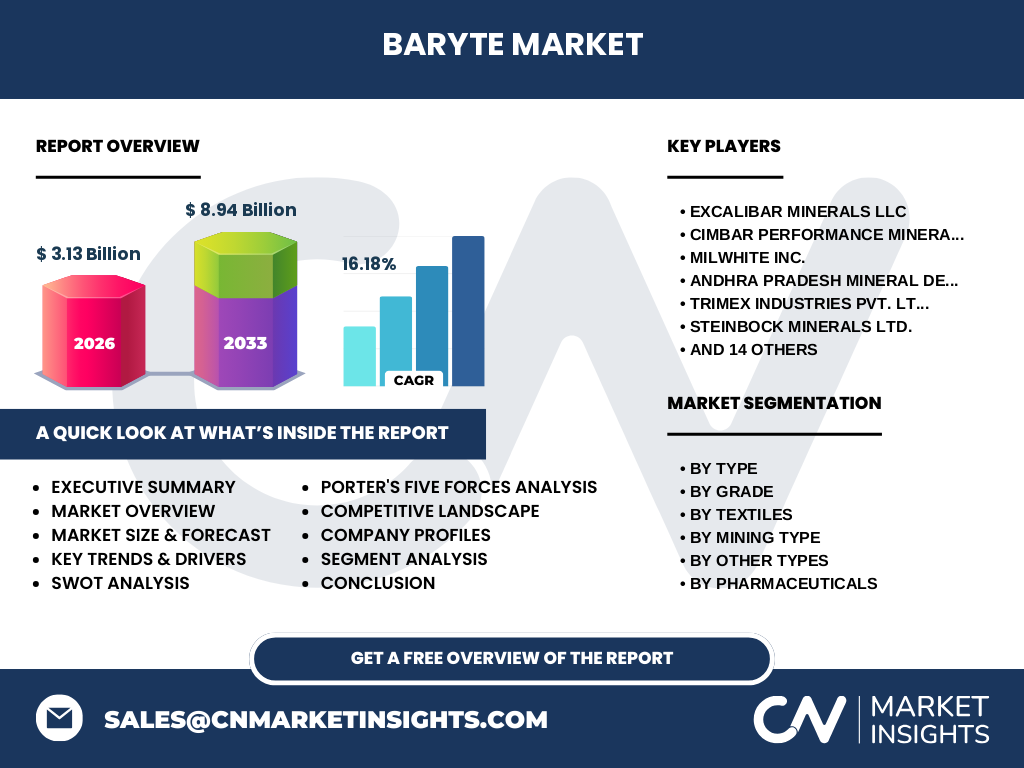
Our analysis indicates that the Baryte Market is valued at $3.13 Billion in 2026, driven by its indispensable high specific gravity. The industry scope spans multiple industrial applications, anchored heavily by oil and gas exploration and specialty chemical manufacturing.
What are the key market drivers, restraints, challenges, and opportunities shaping the Baryte Market?
Growth is heavily propelled by expanding offshore drilling activities. However, stringent environmental regulations regarding heavy metal toxicity act as primary restraints. Strategic opportunities lie in high-purity chemical processing and specialized radiation shielding materials.
Emerging trends and growth patterns in the Baryte Market
The industry is witnessing a distinct pivot toward eco-friendly surface mining practices and ultra-fine micronized grades. Companies are optimizing logistics near major ports to lower transport overheads for dense mineral shipments.
How did COVID-19 impact the Baryte Market and what does the recovery trajectory look like?
The pandemic severely disrupted global supply chains and halted rig counts temporarily. Post-crisis recovery has been exceptionally robust, fueled by aggressive energy sector re-investments and surging industrial demand across developing economies.
Competitive benchmarking and strategic dynamics in the Baryte Market
Market concentration is moderately fragmented, featuring dominant players like Excalibar Minerals LLC and CIMBAR Performance Minerals. Major firms focus on securing captive mine reserves and expanding processing footprints to maintain pricing power.
Executive summary of the Baryte Market
Our research projects the Baryte Market to surge from $3.13 Billion in 2026 to $8.94 Billion by 2033 at a CAGR of 16.18%. Demand is heavily anchored by API grade drilling fluids and advanced industrial applications.
Market forecast trajectory from 2027 to 2033
The data suggests sustained acceleration, pushing market valuation from $3.13 Billion in 2026 to reach $8.94 Billion by 2033. This expansion represents a powerful 16.18% CAGR, driven by broad-based industrialization.
Segmentation analysis across applications and grades
Segmentation includes Oil And Drilling, Paints and Coatings, Pharmaceuticals, Rubber And Plastics, Textiles, and Baryte-Adhesives. Grades are split into API Grade Baryte, Chemical Grade Baryte, and Industrial Grade Baryte, each serving distinct technical specifications.
Regional market analysis and geographic distribution
Geographic performance is heavily weighted toward regions with extensive oilfield operations and dense manufacturing hubs. North America and Asia-Pacific lead consumption, supported by extensive surface and underground mining output.
In-depth regional review of high-growth territories
Asia-Pacific dominates volume consumption due to rapid infrastructure development and active domestic mining by entities like Andhra Pradesh Mineral Development Corporation. Meanwhile, North America prioritizes high-purity API grades for shale basins.
Company profiles and strategic positioning of leading entities
Key market participants such as Milwhite Inc., Trimex Industries Pvt. Ltd., and Steinbock Minerals Ltd. leverage backward integration. They maintain competitive advantages through proprietary milling technologies and robust global distribution networks.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers remains moderate due to standardized API specifications, while supplier power is constrained by abundant global reserves. Threat of substitutes is low in drilling fluids due to baryte's unmatched density.
SWOT analysis of the Baryte Market
Strengths include high specific gravity and chemical inertness. Weaknesses involve high freight costs for a heavy bulk commodity. Opportunities reside in medical contrast agents, while threats stem from strict environmental compliance costs.
Value chain analysis from raw materials to end-users
The value chain initiates with surface and underground extraction, proceeds through crushing, washing, and fine-grinding beneficiation, and culminates in specialized logistics supplying oilfield service providers and coating manufacturers.
Investment insights and high-potential areas
High-potential capital allocation targets chemical-grade processing facilities and micronization plants. Investors should focus on companies scaling sustainable mining operations to mitigate tightening environmental regulations.
Conclusion and key takeaways for stakeholders
Achieving a projected valuation of $8.94 Billion by 2033 underlines the sector's robust health. Stakeholders must prioritize technological integration in milling and secure strategic supply agreements to capture value.
Research methodology for baseline estimations
Baseline figures are triangulated through rigorous primary stakeholder interviews with mining executives, cross-referenced with trade registry data, and calibrated against macroeconomic industrial production indicators.
Scope of the report and coverage parameters
This report covers global production, consumption trends, and pricing dynamics across all major grades and end-use segments from 2026 through 2033, explicitly excluding localized artisanal unrecorded mining outputs.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic joint ventures by firms like Guizhou Tianhong Mining Co. Ltd. and Oren Hydrocarbons Private Limited aimed at securing eco-friendly processing lines and expanding export logistics.