What is the market overview and industry significance of the Electrostatic Coalescer Market?
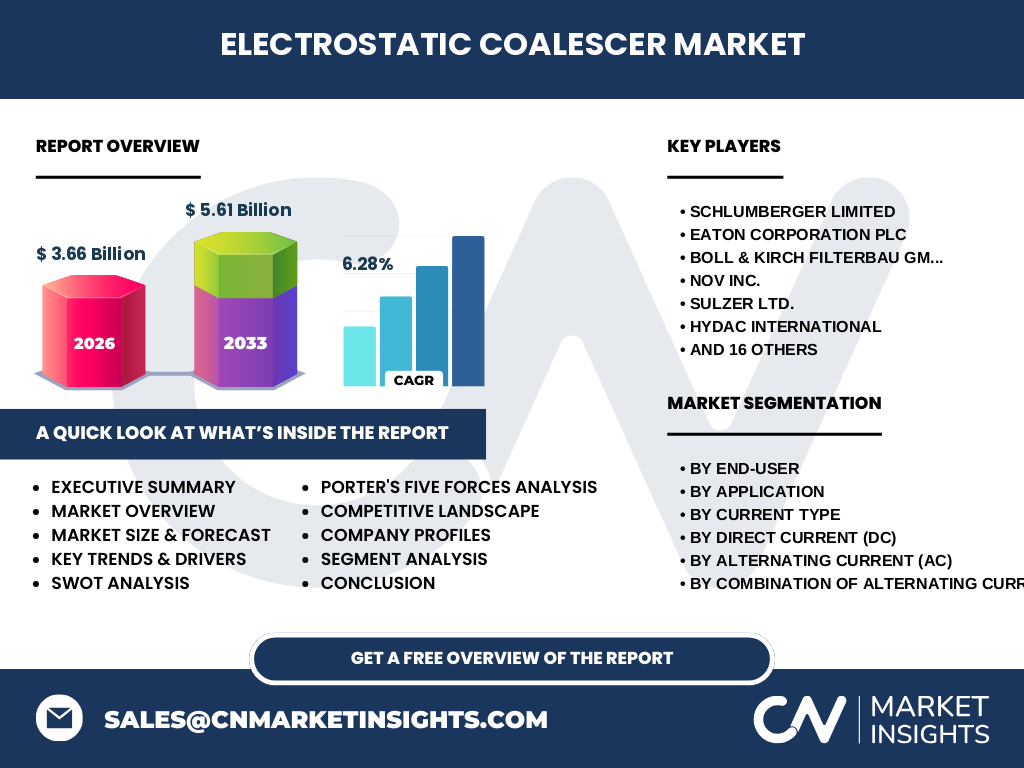
Our analysis indicates the Electrostatic Coalescer Market is valued at $3.66 Billion in 2026, driven by critical separation requirements in heavy industries. These systems utilize high-voltage electric fields to merge dispersed water droplets in continuous hydrocarbon phases, preventing equipment corrosion and meeting strict pipeline transport specifications mandated by bodies like the American Petroleum Institute.
Key market drivers, restraints, challenges, and opportunities shaping Electrostatic Coalescer Market
Growth is propelled by rising heavy crude extraction requiring advanced dehydration. However, high capital expenditure for specialized metallurgy remains a restraint. Opportunities abound in deploying smart coalescers featuring adaptive AC-DC switching to handle fluctuating water-cut levels in mature offshore platforms.
Emerging trends and growth patterns in Electrostatic Coalescer Market
The shift toward digital oilfields has accelerated adoption of automated dehydration units. Operators increasingly demand high-efficiency filtration solutions that minimize chemical demulsifier usage, aligning with stringent environmental discharge regulations enforced by regional authorities.
COVID-19 impact analysis — how the pandemic affected Electrostatic Coalescer Market and the recovery trajectory
The pandemic caused severe supply chain bottlenecks and delayed capital projects across upstream and downstream segments. Post-pandemic recovery has been robust, fueled by renewed global energy demand and accelerated brownfield optimization led by firms like Schlumberger Limited and NOV Inc.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features moderate consolidation, with established equipment manufacturers and specialized engineering houses dominating. Key players like Sulzer Ltd., Eaton Corporation PLC, and Boll & Kirch Filterbau GmbH compete through proprietary electrode designs and modular skid fabrication for expedited offshore installation.
Executive summary of key findings about Electrostatic Coalescer Market
This proprietary research projects the Electrostatic Coalescer Market to expand from $3.66 Billion in 2026 to $5.61 Billion by 2033 at a CAGR of 6.28%. Technological convergence of AC and DC systems into hybrid configurations represents the primary value creation frontier for equipment fabricators.
Market forecast — projected growth from 2027 to 2033
Driven by expanding petrochemical output and aging refinery infrastructure requiring upgraded desalter units, the market will achieve a steady 6.28% CAGR, reaching $5.61 Billion by 2033. Upstream applications will capture the largest share of this incremental revenue.
Segmentation analysis by End-User, Application, and Current Type
The market is segmented by end-user (Power Generation, Petrochemicals, Oil And Gas, Refining, Other End Users), application (Upstream, Downstream), and current type (AC, DC, Combination AC/DC). Oil And Gas and Upstream sectors dominate demand due to harsh water-heavy extraction conditions.
Regional market analysis and geographic performance
Geographic distribution heavily favors regions with extensive hydrocarbon processing infrastructure. The Middle East and North America lead consumption, supported by massive onshore fields and stringent downstream product quality standards enforced by environmental protection agencies.
In-depth regional review of key growth zones
North America exhibits high demand for replacement high-voltage DC units in mature shale plays, while the Middle East prioritizes massive greenfield multi-phase separation skids. Regulatory pressure regarding produced water reinjection further accelerates adoption in these key operational theaters.
Company profiles and strategic positioning of leading market participants
Industry leaders maintain distinct competitive moats. Cameron International Corporation and Frames Group excel in massive offshore separation modules, while HYDAC International and Graver Technologies LLC focus on specialized filtration media integration for enhanced fluid purity.
Porter's Five Forces analysis of the Electrostatic Coalescer Market
Supplier power remains moderate due to specialized high-voltage transformer requirements. Buyer power is counterbalanced by the critical nature of electrostatic dehydration; failure risks downstream catalyst poisoning, making proven reliability paramount over initial capital cost.
SWOT analysis highlighting strategic positioning
Strengths include high separation efficiency for heavy crudes. Weaknesses involve complex electrical safety certifications. Opportunities lie in water treatment applications, while threats stem from macroeconomic volatility impacting upstream capital expenditure budgets.
Value chain analysis from raw materials to end-users
The value chain spans specialty alloy sourcing (such as duplex stainless steel), high-voltage electrical component manufacturing, skid fabrication by firms like EN-FAB Inc. and Petro Techna, and final commissioning by upstream operators and downstream refiners.
Investment insights and high-potential growth areas
Investors should target developers of smart coalescers with adaptive AC-DC switching and firms offering modular retrofit kits. These technologies address brownfield debottlenecking needs without requiring complete platform overhauls.
Conclusion and key takeaways for industry stakeholders
With the market expanding to $5.61 Billion by 2033, sustained success requires integrating digital monitoring capabilities and hybrid current technologies to meet tightening environmental and operational standards across all energy sectors.
Research methodology detailing data triangulation and validation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with engineering procurement construction executives, and secondary macroeconomic indicators regarding global refining capacity utilization rates.
Scope of the report and coverage parameters
This report covers global revenue projections from 2027 to 2033, analyzing specific equipment configurations across upstream and downstream applications. It explicitly excludes non-electrostatic gravity and centrifugal separation technologies.
Recent developments, partnerships, and product launches
Recent strategic moves feature increased collaboration between equipment fabricators like Zeta-pdm Ltd. and digital automation providers. Companies are launching low-power footprint units designed specifically to reduce carbon intensity on remote offshore production platforms.