Automated Weather Station Market Overview and Industry Significance
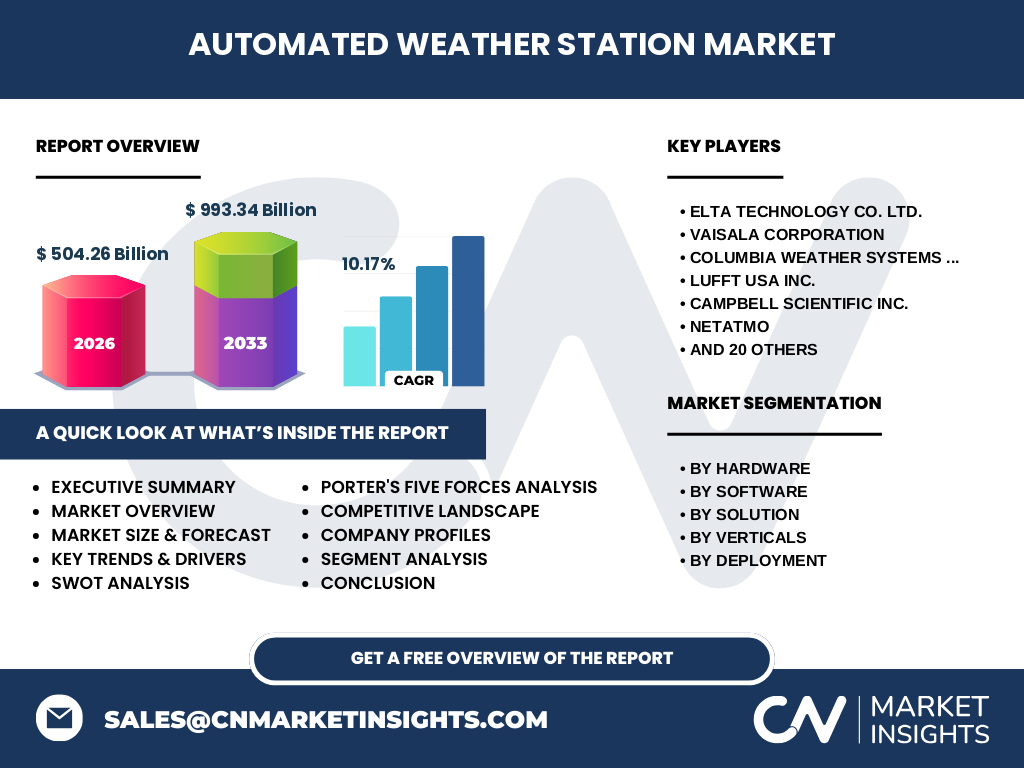
Our analysis indicates the Automated Weather Station Market stands at 504.26 Billion in 2026, serving as critical infrastructure for real-time environmental monitoring. Comprising sophisticated sensors, data loggers, and anemometers, this sector underpins operational safety across aviation, agriculture, and energy networks regulated by bodies like the WMO.
Structural Growth Drivers and Market Constraints
Growth is propelled by extreme weather events and precision agriculture demands, though high upfront capital expenditure for meteorological towers creates deployment bottlenecks. Regulatory mandates from civil aviation authorities compel facilities to upgrade legacy hardware with robust rain gauges and wind vanes.
Emerging Technological Trends in Environmental Intelligence
The shift toward cloud-based remote monitoring software is revolutionizing telemetry. Edge computing integration allows companies like Campbell Scientific and Vaisala to process raw sensor outputs locally, reducing satellite bandwidth latency and enhancing predictive modeling accuracy for severe meteorological anomalies.
COVID-19 Pandemic Impact and Post-Crisis Recovery
Supply chain disruptions for semiconductor components initially stalled hardware deployments. However, post-pandemic economic recovery accelerated infrastructure modernization, as governments prioritized resilient logistics networks and automated early-warning systems to mitigate climate-induced supply chain vulnerabilities.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of multinational conglomerates and specialized innovators. Industry leaders such as Vaisala, Campbell Scientific, and Gill Instruments dominate through proprietary sensor calibration technology, while niche players focus on localized agricultural data analysis and visualization software.
Executive Summary of Key Research Findings
This comprehensive report highlights a robust 10.17% CAGR, projecting market valuation to reach 993.34 Billion by 2033. Accelerated adoption of cloud analytics and renewable energy meteorological assessments are the primary catalysts for this unprecedented expansion.
Automated Weather Station Market Forecast (2027 to 2033)
Driven by sustained investments in smart city infrastructure and offshore wind farms, the market will scale rapidly from its 2026 baseline. Our forecasts indicate exponential revenue acceleration between 2029 and 2033 as developing nations upgrade national meteorological networks.
Segmentation Analysis Across Hardware, Software, and Verticals
Segmentation spans hardware (sensors, anemometers, rain gauges), software (forecasting, data visualization), deployment models (on-premise, cloud-based), and diverse verticals. Agriculture and renewable energy represent the fastest-growing end-user segments, requiring specialized wind and solar irradiance tracking.
Geographic Distribution and Regional Performance
Regional performance varies based on government climate funding and industrial density. North America and Europe lead in hardware density and cloud software adoption, while Asia-Pacific exhibits the highest growth velocity due to rapid agricultural automation and expanded aviation networks.
In-Depth Regional Review of High-Growth Territories
In the Asia-Pacific region, localized weather constraints and monsoonal volatility necessitate dense sensor deployments. Government initiatives supporting smart farming in developing economies ensure that regional procurement of automated weather stations outpaces mature Western markets.
Company Profiles and Strategic Positioning
Market participants like Kipp & Zonen and Hukseflux specialize in solar radiometry, whereas Davis Instruments and Ambient Weather capture prosumer and light commercial segments. Their strategic focus remains on ruggedized outdoor enclosures and low-power IoT connectivity.
Porter's Five Forces Analysis of the Industry
Bargaining power of suppliers is moderate due to specialized sensor component scarcity. Competitive rivalry is intense, forcing manufacturers like Vaisala and Campbell Scientific to continuously innovate in low-power firmware and automated calibration routines.
SWOT Analysis of the Automated Weather Station Sector
Strengths include high-precision sensor accuracy and proprietary data algorithms. Weaknesses involve complex field maintenance requirements. Opportunities lie in IoT-enabled remote deployments, while threats stem from macroeconomic inflation affecting municipal infrastructure budgets.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw silicon and semiconductor sourcing for data loggers, progressing through precision mechanical assembly of anemometers, and culminating in cloud-based API delivery to end-users in aviation, defense, and enterprise agriculture.
Strategic Investment Insights and High-Potential Areas
Investors should target software integration firms specializing in AI-driven weather data management. Companies offering modular, plug-and-play cloud platforms are poised to capture market share as industrial users demand rapid deployment capabilities.
Conclusion and Strategic Takeaways
The Automated Weather Station Market presents exceptional growth characteristics through 2033. Stakeholders must prioritize software-hardware integration and cloud scalability to capitalize on shifting enterprise demand for real-time climate intelligence.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining customs trade registries, primary stakeholder interviews with chief meteorologists, and secondary macroeconomic indicators. This rigorous multi-tier methodology ensures high fidelity in market sizing and growth projections.
Scope of the Report and Coverage Parameters
This report covers global deployment of automated weather stations across hardware, software, and solution tiers from 2026 to 2033. Limitations exclude consumer-grade weather toys lacking calibrated meteorological certification standards.
Recent Industry Developments and Strategic Moves
Recent developments feature strategic partnerships between sensor manufacturers and satellite IoT providers to eliminate cellular dead zones. Companies are heavily investing in edge AI capabilities to process meteorological data directly at the station level.