What is the market overview and industry significance of the Personalized Travel And Experiences Market?
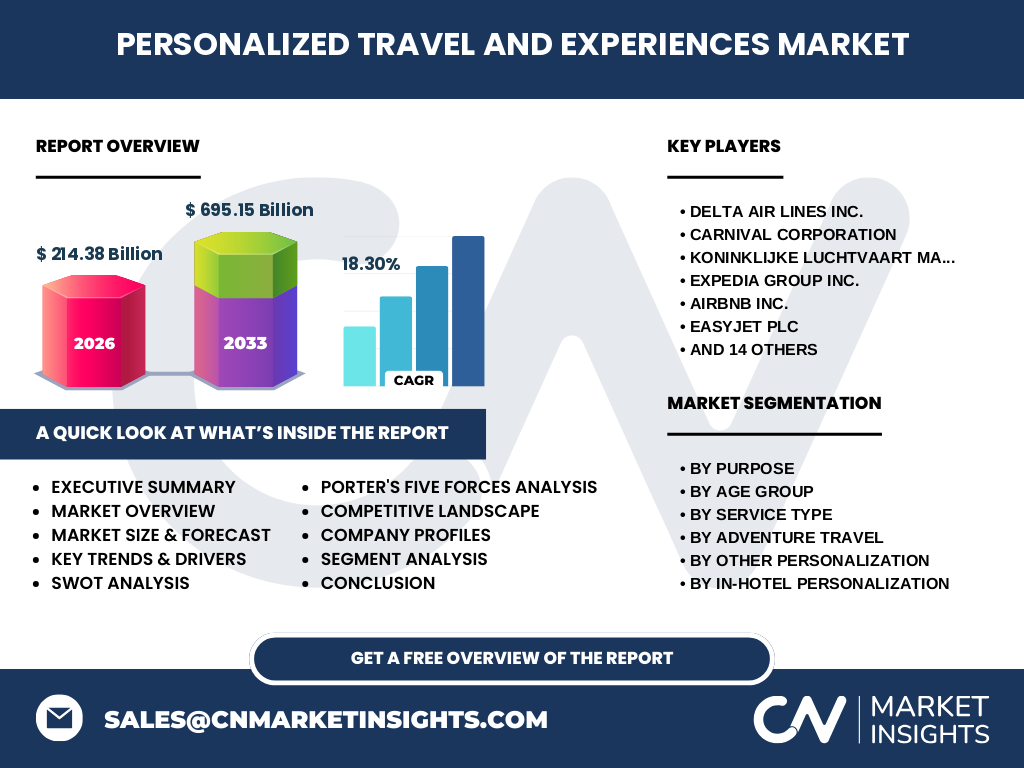
Our analysis indicates that the Personalized Travel And Experiences Market reached 214.38 Billion in 2026, driven by an accelerating consumer shift toward bespoke itineraries. This sector encompasses tailored leisure and corporate journeys, optimizing everything from in-flight personalizations to custom adventure packages. Industry significance lies in how advanced data analytics transforms standard logistics into deeply curated itineraries, setting new benchmarks for customer loyalty.
Structural Growth Drivers and Restraints Shaping the Landscape
The data suggests that robust demand for hyper-customized journeys acts as the primary catalyst, while strict international data privacy regulations impose notable operational hurdles. Key restraints involve fragmented legacy booking systems that struggle to integrate real-time preference data across multiple touchpoints, restricting seamless execution for global tour operators.
The Shift Toward Niche Customization: Emerging Trends and Growth Patterns
Industry trends demonstrate a massive pivot toward hyper-localized experiential offerings over mass-market tourism. Travelers increasingly demand tailormade activity planning and specialized in-hotel amenity preferences. This pattern favors agile innovators capable of deploying dynamic machine-learning models to update active itineraries on the fly.
How did the COVID-19 pandemic permanently alter the trajectory of the Personalized Travel And Experiences Market?
The pandemic forced a structural reset, accelerating touchless technology adoption and heightening demand for private, isolated excursions. As recovery took hold, our research shows travelers prioritizing health security alongside custom itineraries. This crisis acted as a digital catalyst, permanently embedding flexible booking frameworks into luxury and adventure travel ecosystems.
Competitive Benchmarking and Strategic Dynamics
Market concentration features a mix of agile specialists and massive OTA conglomerates vying for high-value demographics. Titans like Expedia Group Inc. and Airbnb Inc. leverage vast user data for scale, while bespoke specialists like Abercrombie & Kent Ltd. and Kensington Tours Ltd. dominate through high-touch concierge services and exclusive local access.
Executive Summary: High-Level Synthesis of Key Findings
Our comprehensive report reveals a dynamic valuation trajectory, with the Personalized Travel And Experiences Market projected to hit 695.15 Billion by 2033 at an impressive CAGR of 18.30%. The synthesis of leisure demand, millennial preference shifts, and advanced logistical software underpins this unprecedented expansion.
Long-Term Market Forecast and Financial Projections from 2027 to 2033
Based on our econometric modeling, the market is poised for explosive expansion, scaling rapidly from its 2026 baseline to reach 695.15 Billion by 2033. Achieving this trajectory requires a robust compound annual growth rate of 18.30%, fueled by rising disposable incomes and widespread adoption of predictive itinerary customization tools.
Comprehensive Segmentation Analysis of the Sector
Our analysis segments the landscape by purpose into Leisure and Business; by age group spanning Millennial, Generation X, Baby Boomers, and Other Age Groups; and by service type. Service types encompass In-Flight Personalization, Cruise Lines Personalization, Adventure Travel, and In-Hotel Personalization, each fulfilling distinct consumer expectations.
Regional Market Distribution and Geographic Performance
Geographic performance varies significantly, with North America and Europe currently capturing the lion's share of high-end bookings. However, Asia-Pacific emerges as the fastest-growing region, driven by an expanding middle class seeking tailored luxury vacations and sophisticated regional transport personalization.
In-Depth Regional Review and Localized Market Constraints
Regional reviews highlight that European markets face stringent consumer protection laws, whereas North American operations navigate complex airline ancillary fee structures. Despite regulatory hurdles, localized infrastructure investments in destination management systems continue to unlock high-margin growth across both territories.
Company Profiles and Strategic Positioning of Leading Market Participants
Industry leaders occupy distinct strategic niches. Delta Air Lines Inc. and Koninklijke Luchtvaart Maatschappij N.V. (KLM) pioneer cabin and meal customization, while cruise giants like Carnival Corporation excel in bespoke shore excursions. Concurrently, boutique operators such as Black Tomato Ltd., Jacada Travel Ltd., and Butterfield & Robinson Inc. master ultra-luxury tailored itineraries.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate to high due to abundant online booking alternatives, while supplier power stays constrained by diverse aviation and hotel inventories. Threat of substitution is low because standardized packages cannot replicate the deep emotional resonance of truly customized travel experiences.
SWOT Analysis of the Industry Ecosystem
Key strengths include advanced predictive analytics and rich customer data assets, offset by operational weaknesses such as high dependency on manual concierge coordination. Opportunities abound in emerging millennial adventure segments, while threats involve geopolitical instability and tightening cross-border data transfer regulations.
Value Chain Analysis from Raw Inputs to End-Users
The value chain initiates with raw travel inventory suppliers like airlines and hotels, flows through proprietary aggregation platforms, and terminates with end-user delivery via specialized planners like Exo Travel Co Ltd. and Artisans of Leisure. Margin capture heavily favors entities owning the direct client relationship and proprietary curation software.
Investment Insights and High-Potential Growth Areas
Strategic recommendations highlight artificial intelligence itinerary builders and niche multi-generational family adventure packages as prime targets. Investors should prioritize firms demonstrating seamless omnichannel integration, particularly those combining automated in-hotel preferences with human-led local experience curation.
Conclusion and Strategic Takeaways for Industry Stakeholders
In summary, capturing upside in this booming sector requires balancing technological automation with authentic human curation. Companies failing to adopt advanced personalization frameworks risk marginalization as consumer expectations permanently anchor to hyper-customized delivery models.
Research Methodology and Baseline Triangulation Techniques
Our rigorous methodology triangulates data across primary stakeholder interviews with travel executives, exhaustive secondary analysis of trade registry reports, and macroeconomic indicators. Baseline estimates for 2026 are cross-verified against corporate earnings disclosures and cross-border tourism volume databases to ensure absolute accuracy.
Scope of the Report and Analytical Parameters
This report covers global market dynamics from the baseline year through the forecast horizon, examining specific segments across leisure and business travel. Limitations include exclusion of unregistered peer-to-peer informal micro-operators and purely domestic budget excursions lacking digital personalization footprints.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum is defined by strategic airline-hotel collaborations and major investments in generative AI trip planners. Firms like Virgin Hotels Group Limited and Expedia Group Inc. continue to roll out enhanced mobile preference engines, validating the ongoing transition toward fully integrated digital travel ecosystems.