Market overview and structural scope of the Coal Market
The Coal Market encompasses the global extraction, processing, and distribution of carbon-rich sedimentary rocks utilized primarily for thermal power generation and metallurgical processes. Valued at 793.36 Billion in 2026, the sector underpins baseload electricity grids and steel manufacturing worldwide. Our analysis indicates that raw material categories like bituminous coal, sub-bituminous coal, lignite, and anthracite dictate global energy security frameworks, driving heavy industrial supply chains across major economies.
What are the primary drivers and restraints shaping the Coal Market industry trends?
Structural growth in the Coal Market is heavily propelled by emerging industrial electricity demands in developing economies, offset by aggressive decarbonization mandates from bodies like the European Union. Restraints include strict emissions caps and high financing costs for coal-fired plants, while opportunities lie in high-grade anthracite applications for specialized metallurgy. Major players like China Shenhua Energy and Peabody Energy are actively navigating these dual pressures through asset optimization.
Emerging trends and growth patterns in the Coal Market
The Coal Market industry trends reveal a distinct polarization between thermal power phase-outs and resilient demand for metallurgical bituminous coal in steel production. Technological innovations in surface mining and underground extraction automation are driving operational efficiencies. Furthermore, shifting trade flows toward Asian import hubs via ports like Newcastle highlight how regional energy deficits continue to override long-term green transition policies in the short to medium term.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain bottlenecks and temporary demand destruction across industrial end-users, depressing baseline valuations. However, our research shows a robust post-pandemic rebound driven by post-lockdown manufacturing surges and global energy crunches. Companies like Coal India Limited and Glencore leveraged logistical adjustments to capitalize on surging international thermal coal prices during the 2021-2023 recovery window, cementing a resilient structural bounce-back.
Competitive landscape and strategic market concentration
Market concentration in the Coal Market remains heavily consolidated among state-backed giants and multinational resource conglomerates. Strategic dynamics involve portfolio rebalancing, with firms like Yanzhou Coal Mining and Arch Resources optimizing asset bases between thermal and metallurgical grades. Competitive positioning increasingly relies on low-cost surface mining capabilities, long-term supply contracts with steel mills, and navigating stringent environmental compliance frameworks across key operating jurisdictions.
Executive summary of the global Coal Market
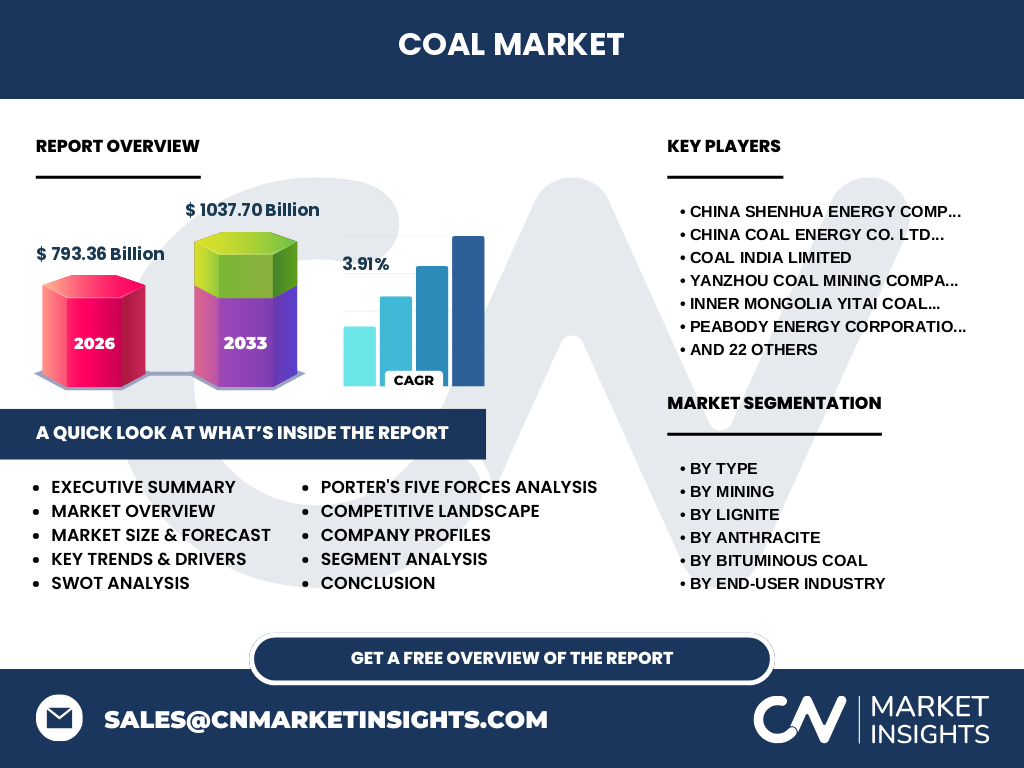
The global Coal Market is projected to expand steadily from 793.36 Billion in 2026 to reach 1037.70 Billion by 2033, exhibiting a CAGR of 3.91%. Our analysis indicates that while traditional thermal power faces structural headwinds, metallurgical coal demand for steelmaking remains a vital growth anchor. Industry leaders are focusing on operational efficiency and supply chain resilience to capture value across diverse end-user sectors.
Market forecast from 2027 to 2033
Driven by persistent industrial electricity needs and metallurgical demand, the Coal Market is forecasted to expand at a steady CAGR of 3.91%, growing from 793.36 Billion in 2026 to 1037.70 Billion by 2033. This trajectory underscores the continued reliance of developing manufacturing hubs on affordable fossil fuels, despite accelerated renewable energy integration in Western economies and stringent carbon taxation policies.
Segmentation analysis across types, mining methods, and end-user industries
The Coal Market is segmented by type into Bituminous Coal, Sub-Bituminous Coal, Lignite, and Anthracite, and by mining into Surface Mining and Underground Mining. End-user applications span electricity generation, steel production, and cement manufacturing. Bituminous coal dominates revenue shares due to its dual utility in thermal power plants and metallurgical coke ovens, while specialized sub-categories address specific regional energy and industrial needs.
Regional market analysis and geographic performance
Geographic performance in the Coal Market is heavily skewed toward Asia-Pacific, which commands the lion's share of consumption due to extensive reliance on coal-fired power plants in China and India. North American and European markets exhibit stable or declining thermal demand offset by metallurgical exports. Regulatory pressures in the West contrast sharply with capacity expansion in developing regional blocks, shaping divergent localized pricing and trade dynamics.
In-depth regional review of high-consumption territories
Asia-Pacific remains the undisputed engine of the Coal Market, anchored by domestic production from giants like China Coal Energy and Coal India Limited. Import dependencies in nations like Japan and South Korea drive robust maritime trade routes from Australian terminals. Conversely, North American basins managed by companies like Arch Resources focus on high-volatile and low-volatile bituminous grades for domestic steel mills and selective export markets.
Company profiles and strategic positioning of leading participants
Leading industry participants such as China Shenhua Energy Company Limited, Peabody Energy Corporation, and SUEK leverage massive scale and integrated logistics networks to maintain market leadership. Strategic positioning focuses on cost leadership in surface mining, long-term domestic utility supply agreements, and selective export diversification. These firms continuously adapt to regulatory shifts by investing in operational efficiencies and supply chain optimization.
Porter's Five Forces analysis of the Coal Market
Porter's Five Forces framework reveals moderate supplier power due to high capital requirements for new mines, countered by strong buyer power from large utility conglomerates and steelmakers. The threat of substitutes is intensifying via liquefied natural gas and renewables, while competitive rivalry remains high among established domestic producers. Barriers to entry are formidable, protected by massive upfront capex, complex permitting, and established logistical rail networks.
SWOT analysis of the global sector
Strengths include established global supply chains and high energy density, while weaknesses involve severe carbon footprints and regulatory vulnerability. Opportunities exist in high-grade anthracite industrial uses and gasification technologies. Threats stem from aggressive net-zero carbon pledges, stringent ESG financing constraints, and substitution risks from alternative energy sources. Companies must balance short-term cash generation with long-term transition strategies to mitigate systemic threats.
Value chain analysis from raw extraction to end-users
The value chain spans geological exploration, surface or underground extraction, beneficiation and washing, bulk rail or maritime logistics, and final combustion or processing by end-users. Value addition occurs heavily during coal washing and grading, where raw mined output is refined into metallurgical or thermal specifications. Logistical bottlenecks at major export terminals frequently dictate regional pricing spreads and supply reliability for international buyers.
Investment insights and high-potential areas
Investment opportunities in the Coal Market are increasingly concentrated in high-margin metallurgical coal assets required for blast-furnace steel production, where substitutes remain technologically challenging. Investors should prioritize low-cost producers with strong balance sheets, robust ESG compliance frameworks, and diversified export capabilities to insulate against localized regulatory shocks. M&A activity is expected to favor consolidation among mid-tier operators.
Conclusion and key strategic takeaways
In summary, the Coal Market demonstrates enduring structural resilience, projected to grow from 793.36 Billion in 2026 to 1037.70 Billion by 2033 at a 3.91% CAGR. While thermal coal faces long-term decarbonization headwinds, metallurgical segments and developing Asian energy needs will sustain baseline demand. Stakeholders must navigate ESG pressures while capitalizing on cash-generative core assets.
Research methodology and data triangulation
Our research methodology combines exhaustive bottom-up data aggregation with top-down macroeconomic modeling. Baseline estimates are triangulated using official trade registry statistics, customs data from major exporting ports, primary executive interviews with industry stakeholders, and secondary macroeconomic indicators. This rigorous multi-source validation ensures high fidelity in our market sizing and growth projections across all segments.
Scope of the report and coverage parameters
This report provides a comprehensive evaluation of the global Coal Market industry trends, covering historical data alongside forecasts through 2033. The analysis spans all primary coal types, mining methodologies, and key end-user verticals across major geographic regions. Limitations include potential unforeseen geopolitical shifts, rapid regulatory interventions, and sudden macroeconomic disruptions that could alter short-term trade flows.
Recent developments, corporate announcements, and strategic moves
Recent developments in the sector feature strategic asset swaps, divestments of thermal assets by Western miners, and capacity expansions among Asian producers to meet domestic energy baseload needs. Major operators are forming joint ventures to secure rail and port logistics, ensuring uninterrupted supply to key industrial hubs. These strategic maneuvers reflect an industry adapting to dual demands of immediate energy security and long-term rationalization.