What is the E-Waste Recycling and Reuse Services Market overview and industry significance?
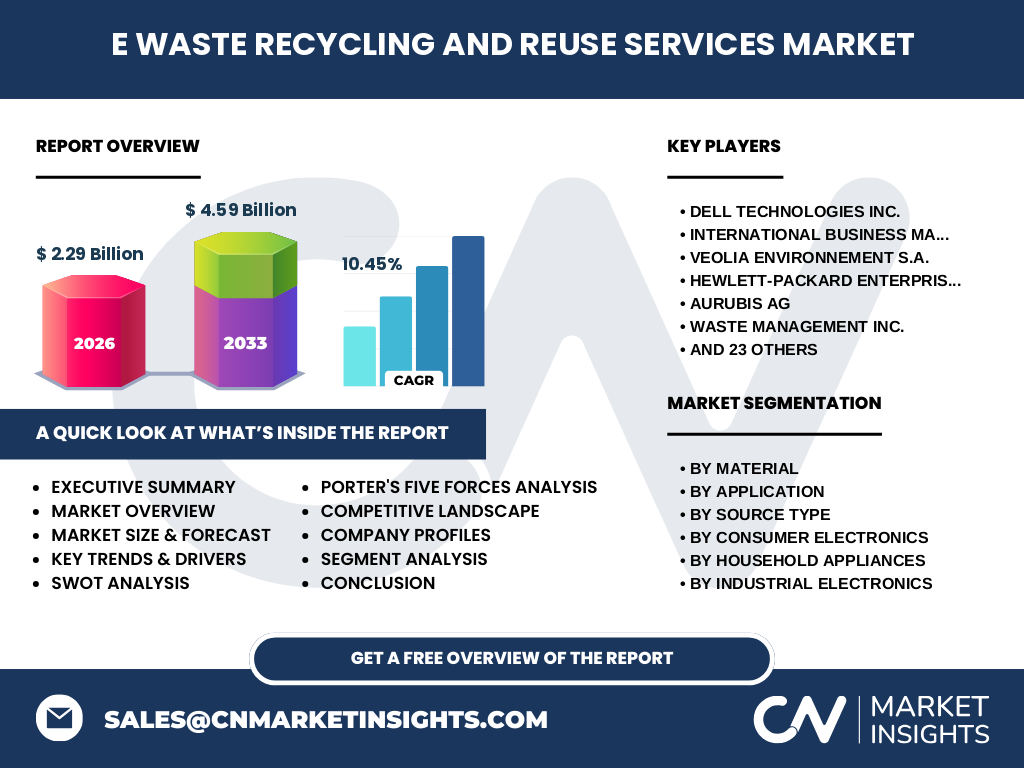
Our analysis indicates that the E-Waste Recycling and Reuse Services Market reached a baseline valuation of $2.29 Billion in 2026. This sector encompasses the recovery of critical raw materials like precious metals, rare earth elements, and specialized plastics from discarded apparatuses, mitigating severe environmental hazards governed by stringent directives like the EU WEEE Directive.
Structural Growth Drivers and Market Restraints
The market is propelled by a 10.45% CAGR driven by corporate sustainability mandates and escalating volumes of obsolete consumer electronics. However, logistical bottlenecks in cross-border hazardous waste transport under Basel Convention rules and high capital expenditures for advanced pyrometallurgical sorting facilities continue to restrain rapid margin expansion for independent processors.
Emerging Trends in E-Waste Circularity
Industry trends highlight a strategic pivot toward urban mining and closed-loop supply chains. Companies like Umicore N.V. and Aurubis AG are pioneering advanced hydrometallurgical refining techniques to extract high-purity copper and gold directly from circuit boards, minimizing reliance on virgin mining operations.
COVID-19 Impact Analysis and Market Recovery
The pandemic severely disrupted collection logistics and municipal e-waste drop-off programs during 2020 lockdowns. Nevertheless, accelerated digital transformation and remote work boosted laptop and monitor retirements, sparking a robust post-pandemic recovery trajectory championed by automated processors like Sims Lifecycle Services Inc. and Electronic Recyclers International Inc.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a blend of vertically integrated global giants and specialized asset recovery specialists. Market leaders such as Veolia Environnement S.A. and Waste Management Inc. leverage extensive municipal contracts, while tech-focused firms like TES Co. Ltd. dominate IT asset disposition (ITAD) for enterprise clients.
Executive Summary of Research Findings
Our comprehensive assessment of the E-Waste Recycling and Reuse Services Market reveals a high-growth sector projected to surge from $2.29 Billion in 2026 to $4.59 Billion by 2033. Stakeholders must prioritize automated dismantling technologies to navigate fluctuating commodity pricing and tightening regulatory enforcement.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the market will expand at a steady 10.45% CAGR throughout the 2027-2033 forecast window, doubling its aggregate valuation to reach $4.59 Billion by 2033. This expansion is underpinned by mandatory corporate ESG reporting and surging adoption of electric vehicle infrastructure components.
Segmentation Analysis Across Materials, Applications, and Sources
The market segments into Metal, Plastic, Glass, and Other Materials by material type; Trashed and Recycled by application; and Household Appliances, Consumer Electronics, and Industrial Electronics by source type. High-value categories like mobile phones and medical devices command dominant processing margins due to high precious metal yields.
Geographic Distribution and Regional Performance
Regional performance varies significantly due to regulatory maturity. Europe leads in formal recycling compliance driven by strict statutory targets, while Asia-Pacific represents a high-volume collection hub anchored by major manufacturing centers in Southeast Asia and rapid urbanization in East Asia.
In-Depth Regional Review and Localized Constraints
North American operations grapple with fragmented state-level recycling legislation rather than a unified federal mandate. Meanwhile, European markets enforce rigorous Extended Producer Responsibility (EPR) frameworks, forcing OEMs to partner directly with certified recyclers like Stena Technoworld AB and Boliden AB.
Company Profiles and Strategic Positioning
Leading entities exhibit distinct strategic focuses. Dell Technologies Inc. and Hewlett-Packard Enterprise Company champion OEM-led takeback initiatives. Meanwhile, specialized processors like Raw Materials Company Inc. and MBA Polymers Inc. focus intensely on high-efficiency alkaline battery recycling and high-grade engineering plastic compounding.
Porter's Five Forces Analysis of the E-Waste Sector
Supplier power remains moderate due to the commoditized nature of raw scrap feedstocks, whereas buyer power is high among enterprise ITAD clients demanding certified data destruction. Threat of new entrants is mitigated by steep environmental permitting costs and specialized shredding patent portfolios held by incumbents like Tetronics Ltd.
SWOT Analysis of Industry Participants
Key strengths include proprietary hydrometallurgical recovery rates exceeding 95%. Weaknesses involve exposure to volatile commodity spot prices for copper and aluminum. Opportunities lie in expanding medical device recycling, while major threats stem from illegal transboundary e-waste dumping into developing regions.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with reverse logistics and municipal collection points, routing through manual sorting and automated shredding facilities operated by firms like GreenChip Inc. and AER Worldwide. Recovered commodities are subsequently fed back into manufacturing supply chains for electronics and automotive production.
Investment Insights and High-Potential Areas
Investors should target automated artificial intelligence optical sorting startups and closed-loop plastic recyclers. Companies possessing certified data sanitization capabilities tailored for hyperscale data center decommissioning represent prime acquisition targets within this $4.59 Billion by 2033 growth trajectory.
Conclusion and Strategic Takeaways
The E-Waste Recycling and Reuse Services Market represents a vital pillar of the circular economy. With a forecasted valuation of $4.59 Billion by 2033, sustained success depends on technological innovation in metal extraction and strict adherence to international environmental compliance standards.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives at firms like Call2Recycle Inc. and Eco Recycling Ltd., and secondary macroeconomic indicators regarding global electronics consumption.
Scope of the Report and Coverage Parameters
This report evaluates the global E-Waste Recycling and Reuse Services Market market size across North America, Europe, Asia-Pacific, and Rest of World. Limitations include the exclusion of informal, unregistered backyard recycling operations operating outside formal municipal reporting frameworks.
Recent Industry Developments and Strategic Partnerships
Recent market dynamism is highlighted by aggressive joint ventures and facility expansions. For instance, Sembcorp Industries Ltd. and specialized regional operators have established advanced e-waste treatment plants to handle rising volumes of discarded communication equipment and automation control systems.