What is the market overview, scope, and industry significance of the Solar Encapsulation Market?
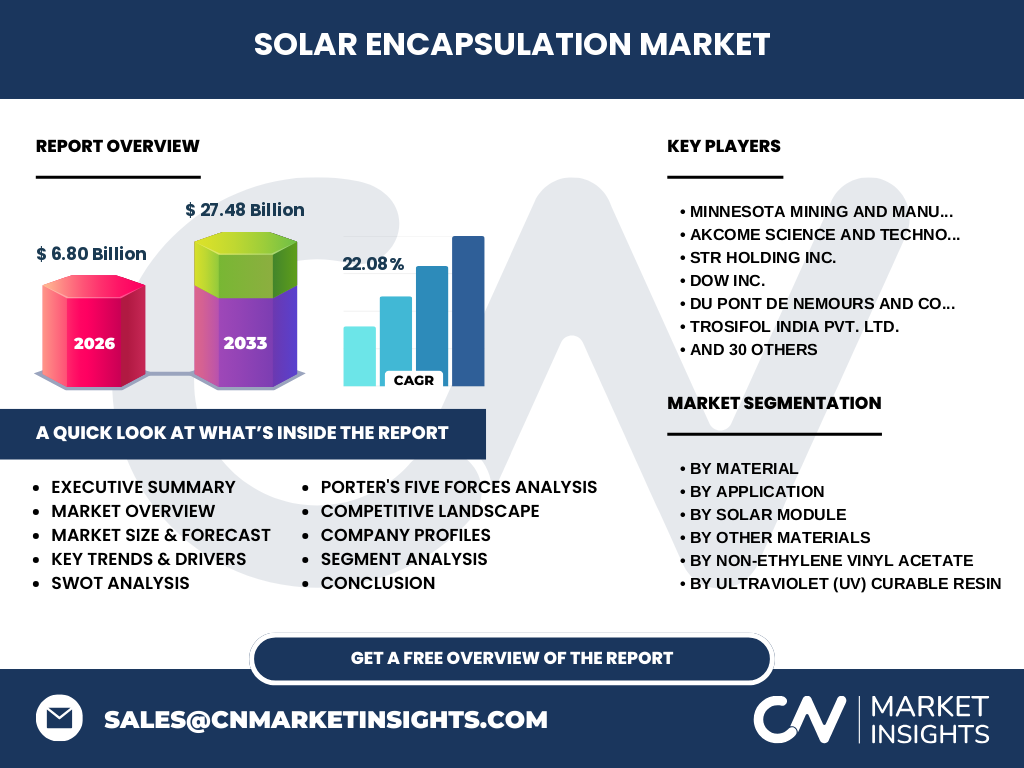
Our analysis indicates that the Solar Encapsulation Market is valued at 6.80 Billion in 2026. This sector encompasses critical protective film technologies safeguarding photovoltaic modules against environmental degradation, moisture ingress, and ultraviolet radiation. Industry significance lies in its direct correlation with solar asset longevity, ensuring sustained energy yield across utility-scale and distributed generation installations.
Key market drivers, restraints, challenges, and opportunities shaping the Solar Encapsulation Market
The market is propelled by aggressive global decarbonization targets and falling levelized cost of electricity (LCOE) for PV systems. However, supply chain bottlenecks for raw materials like polyolefin and fluctuating chemical feedstock costs act as persistent restraints. Strategic opportunities emerge in developing advanced non-EVA encapsulants that withstand harsh desert and marine environments, offering superior PID resistance.
Emerging trends and growth patterns in the Solar Encapsulation Market
A definitive shift toward Non-Ethylene Vinyl Acetate materials is reshaping the landscape, driven by the demand for higher efficiency n-type and bifacial solar modules. Our research highlights how manufacturers increasingly adopt polyolefin-based encapsulants to prevent potential-induced degradation and acetic acid formation, extending operational lifespans beyond standard 30-year warranties in extreme climates.
COVID-19 impact analysis and recovery trajectory for the Solar Encapsulation Market
The pandemic triggered severe supply chain disruptions, raw material shortages, and temporary manufacturing suspensions across key chemical hubs. Despite initial contraction, government-backed green stimulus packages accelerated post-crisis recovery. The market bounced back strongly as renewable energy investments resumed, proving the inherent resilience of utility-scale solar infrastructure development worldwide.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive ecosystem features established chemical giants and specialized film manufacturers, including Dow Inc., DuPont de Nemours and Company, and Hangzhou First PV Material Co. Ltd. Market concentration is moderately high among top-tier suppliers leveraging proprietary extrusion technologies and massive scale economies to secure long-term supply agreements with tier-1 module makers.
Executive summary of the Solar Encapsulation Market
Our comprehensive research projects the Solar Encapsulation Market to expand from 6.80 Billion in 2026 to reach 27.48 Billion by 2033, registering a robust CAGR of 22.08%. Growth is fundamentally underpinned by surging global demand for high-efficiency solar modules and stringent regulatory mandates prioritizing renewable energy generation and grid decarbonization.
Market forecast and projected growth trajectory from 2027 to 2033
Based on our econometric modeling, the market enters an exponential growth phase between 2027 and 2033, scaling rapidly to 27.48 Billion at a CAGR of 22.08%. This trajectory reflects accelerating solar installations across emerging economies and the rapid commercialization of next-generation encapsulation chemistries tailored for specialized architectural and utility applications.
Segmentation analysis of the Solar Encapsulation Market
Market segmentation is structured across material types, end-use applications, and solar module integration. By material, the market covers Non-Ethylene Vinyl Acetate, Ultraviolet (UV) Curable Resin, and other compounds. Application sectors span automotive, electronics, and specialized industrial deployments, while solar module categories feature polycrystalline silicon cells, cadmium telluride, and amorphous silicon variants.
Regional market analysis and geographic performance distribution
Geographic performance reveals pronounced leadership in Asia-Pacific, driven by massive manufacturing capacities in China and aggressive solar deployment targets across India. Meanwhile, North America and Europe demonstrate steady demand focused on technological innovation, high-efficiency bifacial modules, and stringent building-integrated photovoltaic (BIPV) regulatory compliance.
In-depth regional review of key geographic markets
The Asia-Pacific region dominates consumption volume, supported by localized supply chains and domestic PV manufacturing ecosystems led by companies like Akcome Science and Technology and Jolywood Sunwatt. Concurrently, North American markets prioritize premium encapsulation films that meet rigorous Underwriters Laboratories (UL) fire and durability certifications for commercial and utility deployments.
Company profiles and strategic positioning of leading market participants
Industry leaders such as Mitsui Chemicals Inc., Wacker Chemie AG, and Eastman Chemical Company maintain strong competitive positions through continuous R&D investment in specialized polymer formulations. Their strategic focus centers on expanding manufacturing footprints near emerging solar hubs and forging direct supply partnerships with global module assemblers.
Porter's Five Forces analysis of the Solar Encapsulation Market
Bargaining power of suppliers is moderate due to specialized chemical inputs, while buyer power remains high among major module assemblers demanding competitive pricing. Threat of substitutes is low given the technical indispensability of encapsulant films, whereas industry rivalry is intense, compelling firms to compete on proprietary moisture barrier properties.
SWOT analysis of the Solar Encapsulation Market
Key strengths include robust technological advancements and high product durability. Weaknesses involve high initial capital expenditure for advanced extrusion lines. Opportunities lie in emerging BIPV and automotive integration, while major threats encompass raw material price volatility and potential trade tariffs on polymer chemical imports.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream petrochemical and specialty chemical suppliers providing resins like thermoplastic polyurethane and polyolefin. Midstream involves film extrusion, compounding, and cross-linking optimization by specialized converters. Downstream distribution reaches module manufacturers who laminate these films into finished photovoltaic panels deployed by utility developers.
Investment insights and strategic recommendations for stakeholders
Our analysis advises investors to target advanced non-EVA and UV-curable resin manufacturers positioned to capture high-margin segments in bifacial and tandem solar technologies. Strategic acquisitions of regional extrusion specialists will enable incumbents to bypass localized supply chain friction and capitalize on expanding regional green energy mandates.
Conclusion and key takeaways for industry decision-makers
The Solar Encapsulation Market represents a high-growth frontier within the renewable energy ecosystem, scaling from 6.80 Billion to 27.48 Billion by 2033. Success requires aligning product portfolios with the industry migration toward non-EVA encapsulants, ensuring long-term yield reliability and superior degradation resistance for next-generation photovoltaic architectures.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-suite executives, customs trade registry data, and secondary macroeconomic indicators. Quantitative market sizing models validate historical shipment volumes against regional solar capacity additions to ensure absolute forecasting accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing, material segmentations, and regional forecasts from 2027 to 2033. Analytical limitations include unforeseen macroeconomic policy shifts, sudden trade tariff modifications on raw polymer feedstocks, and localized supply chain disruptions that could temporarily influence projected growth trajectories.
Recent developments, strategic partnerships, and product launches
Recent market activity is characterized by strategic joint ventures and capacity expansions aimed at meeting surging demand for polyolefin encapsulants. Major players including Henkel AG & Co. KGaA and Saint-Gobain SA have introduced advanced adhesive and barrier films optimized for high-voltage tandem solar cells, reinforcing their competitive advantage.