Market overview and structural significance of the Steel Rebar Market
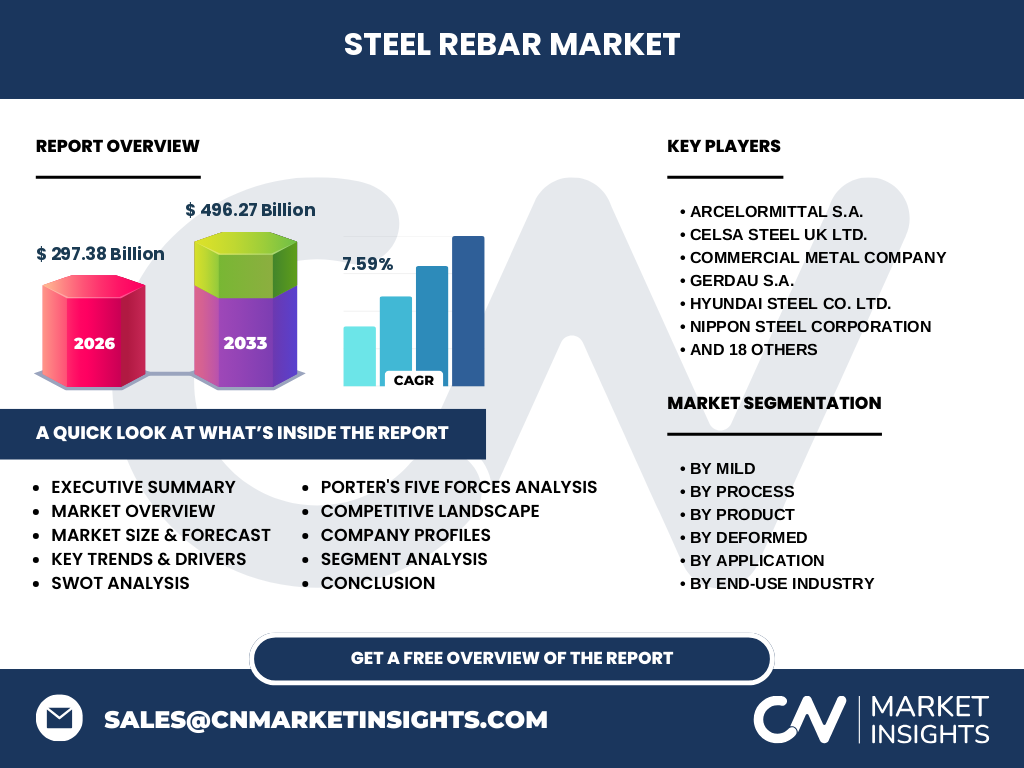
Our analysis indicates the Steel Rebar Market reached a valuation of 297.38 Billion in 2026, driven by intense urbanization and heavy industrial construction globally. This critical sector supplies essential tensile reinforcement for concrete structures, heavily relying on raw iron ore and scrap metal inputs processed through advanced rolling mills.
Structural Growth Drivers, Restraints, and Opportunities
The market is propelled by rapid infrastructure modernization in developing economies, though constrained by volatile coking coal prices and strict environmental regulations from bodies like the World Steel Association. High-growth opportunities lie in seismic-resistant retrofitting and public-private mega-projects requiring specialized deformed bars.
Emerging Industry Trends and Decarbonization Shifts
The shift toward green steel production via Electric Arc Furnace technology is revolutionizing the Steel Rebar Market industry trends. Producers are heavily investing in scrap-based melting to lower carbon footprints, meeting stringent mandates enforced by regional environmental protection agencies.
Pandemic Recovery and Supply Chain Resiliency
The COVID-19 pandemic severely disrupted global logistics, shutting down key maritime ports and stalling construction sites. However, post-pandemic recovery policies featuring aggressive fiscal stimulus packages for public infrastructure have propelled the sector toward a robust growth trajectory.
Competitive Benchmarking and Market Concentration
The landscape features a mix of consolidated multinationals like ArcelorMittal S.A. and regional powerhouses such as Emirates Steel Industries PJSC. Market concentration remains moderately fragmented, where top-tier players leverage scale economies and localized distribution networks to secure dominant market shares.
Executive Summary of Strategic Findings
Based on our research, the Steel Rebar Market market size is poised for exceptional expansion, escalating from 297.38 Billion in 2026 to an impressive 496.27 Billion by 2033, registering a solid CAGR of 7.59%.
Long-Term Market Forecast from 2027 to 2033
Projected growth from 2027 to 2033 indicates a steady climb fueled by relentless smart-city initiatives and energy transition projects. The data suggests sustained demand across emerging economies will comfortably bridge the gap toward the 496.27 Billion valuation milestone.
Comprehensive Segmentation Analysis
Our segmentation framework dissects the market into distinct categories:
- By Mild: Mild Steel (MS) Bars, Plain Mild Steel (MS) Bars, and Hot Rolled Mild Steel (MS) Bars.
- By Process: Basic Oxygen Steelmaking and Electric Arc Furnace.
- By Product: Deformed and Mild variants.
- By Deformed: Thermo-Mechanically Treated (TMT), Ribbed, Twisted, and Cold Worked Deformed Bars.
- By Application: Residential Buildings, Public Infrastructure, and Industrial sectors.
- By End-Use Industry: Construction And Infrastructure, Manufacturing, and Oil And Gas.
Geographic Distribution and Regional Performance
Geographic performance varies significantly, with Asia-Pacific dominating consumption due to aggressive urbanization in China and India. Meanwhile, North America and Europe prioritize advanced infrastructure updates and green-certified construction materials.
In-Depth Regional Review of Key Markets
Regional analysis highlights the Middle East—featuring players like Sohar Steel Group LLC and Qatar Steel Company—as a hotspot for massive real estate ventures. Conversely, North American markets focus on Highway Trust Fund allocations, driving heavy consumption of commercial grade rebars.
Strategic Positioning of Leading Companies
Industry leaders like Nucor Corporation and Gerdau S.A. leverage scrap-fed mini-mills for operational agility. Meanwhile, giants such as Tata Steel Limited and Nippon Steel Corporation focus on high-tensile metallurgical innovations to capture high-margin infrastructure contracts.
Porter's Five Forces Competitive Assessment
Threat of new entrants remains moderate due to high capital expenditure requirements for rolling mills. Bargaining power of raw material suppliers is high for iron ore miners, while buyer power fluctuates based on regional construction demand and project scale.
SWOT Analysis of the Global Sector
Strengths include high tensile strength and recyclability. Weaknesses involve carbon-intensive legacy production. Opportunities emerge from green hydrogen steelmaking, while threats stem from trade tariffs and substitute composite materials.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with iron ore extraction and scrap metal collection, transitioning through Basic Oxygen Steelmaking or Electric Arc Furnace smelting. Intermediate rolling transforms billets into rebar, which is then distributed via logistics hubs to construction sites.
Investment Insights and High-Potential Areas
Investors should target green-certified manufacturing facilities utilizing Electric Arc Furnaces to mitigate regulatory risks. High-potential areas also include emerging markets undergoing rapid structural urbanization and transportation corridor expansions.
Conclusion and Strategic Takeaways
The Steel Rebar Market analysis confirms a lucrative trajectory through 2033, underscored by technological shifts toward sustainability. Stakeholders must align investments with decarbonization mandates and regional infrastructure stimulus programs to capture outsized returns.
Proprietary Research Methodology
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with rolling mill executives, and secondary macroeconomic indicators from global trade bodies and national construction bureaus.
Scope of the Report and Coverage Parameters
This report covers global demand, production capacities, and pricing trends across major geographic zones through 2033. Limitations include unforeseen geopolitical trade restrictions and sudden raw material supply shocks outside modeled parameters.
Recent Corporate Developments and Strategic Moves
Recent industry announcements highlight aggressive capacity expansions by companies like Jindal Steel & Power Ltd. and technological joint ventures focused on low-emission reheating furnaces, signaling a proactive industry adaptation to global climate goals.