What is the scope and market size of the Motor Vehicle And Parts Dealers Market?
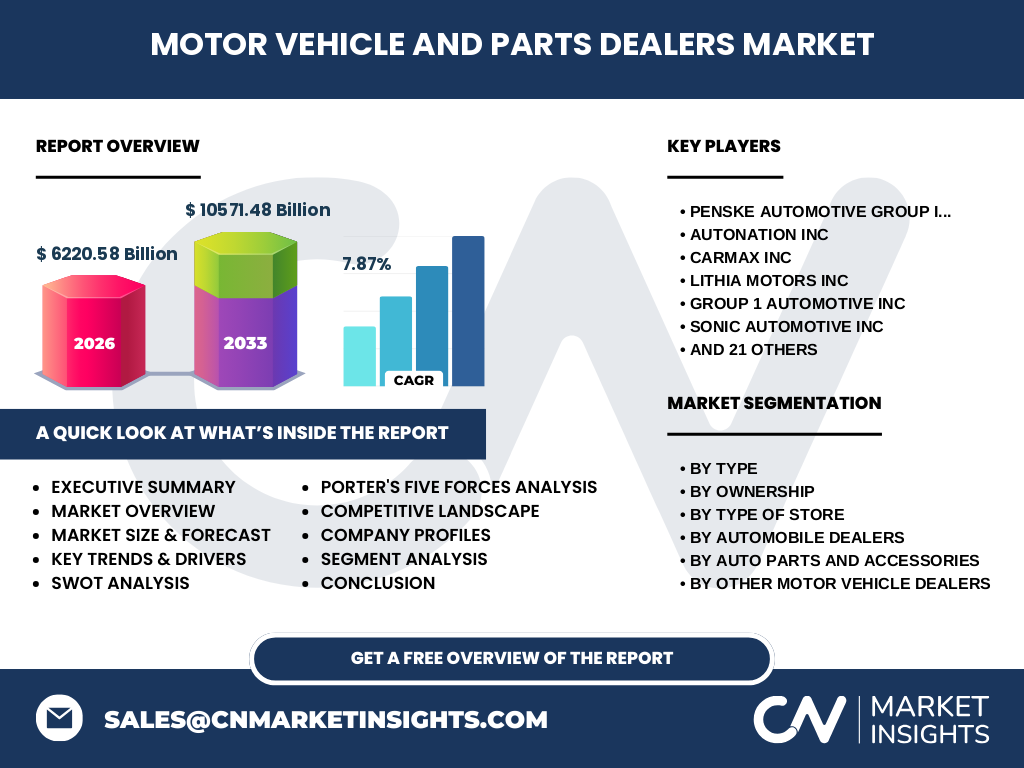
Our analysis indicates that the Motor Vehicle And Parts Dealers Market represents a critical backbone of global automotive commerce, valued at 6220.58 Billion in 2026. This comprehensive sector encompasses automotive retail networks, parts distributors, and specialized vehicle vendors navigating complex supply chains regulated by bodies like the EPA and NHTSA.
What are the primary market drivers, restraints, challenges, and opportunities shaping the industry?
Growth is propelled by surging demand for zero-emission tech, yet tempered by persistent semiconductor shortages and stringent environmental compliance mandates from agencies like the CARB. Market opportunities lie in digital omnichannel retailing, allowing forward-thinking dealers to capture higher margins despite volatile raw material costs for steel and battery minerals.
What are the emerging trends and growth patterns in the Motor Vehicle And Parts Dealers Market?
The data suggests a profound pivot toward digital-first transactions and subscription-based ownership models. Major dealership groups are investing heavily in proprietary e-commerce platforms to streamline trade-ins and financing, reducing lot-dependency and optimizing inventory turnover for both OEM and aftermarket components.
How did the COVID-19 pandemic impact the Motor Vehicle And Parts Dealers Market and its recovery trajectory?
The pandemic caused severe supply chain disruptions and inventory gridlock, but paradoxically triggered unprecedented used vehicle pricing power. Dealerships accelerated contactless delivery and digital F&I solutions, cementing a resilient recovery trajectory that modernized legacy retail frameworks and permanently altered consumer expectations.
How is the competitive landscape structured across major players and market concentration?
The Motor Vehicle And Parts Dealers Market industry trends reflect moderate fragmentation at the local level alongside aggressive consolidation by institutional giants. Industry leaders like Penske Automotive Group Inc, AutoNation Inc, and CarMax Inc leverage immense purchasing scale and proprietary digital platforms to outpace independent storefronts.
Executive Summary of the Motor Vehicle And Parts Dealers Market
Our proprietary research confirms that the market is poised for robust expansion, scaling from 6220.58 Billion in 2026 to 10571.48 Billion by 2033 at a CAGR of 7.87%. Strategic agility in EV integration and aftermarket supply chain management will separate market leaders from underperformers.
What is the market forecast for the Motor Vehicle And Parts Dealers Market from 2027 to 2033?
Based on our research, the market will achieve a stellar CAGR of 7.87%, expanding from the 2026 baseline to reach 10571.48 Billion by 2033. This trajectory is underpinned by accelerating fleet electrification and rising consumer expenditure on maintenance components and accessories.
How is the segmentation analysis structured for this market?
The sector breaks down by type into Auto Parts And Accessories, Automobile Dealers, and Other Motor Vehicle Dealers. Ownership structures divide into Retail Chain and Independent Retailer, while store formats encompass Exclusive Retailers Or Showroom and Inclusive Retailers Or Dealer Store.
What characterizes the regional market analysis and geographic performance?
Geographic performance highlights North America and Europe as mature profit centers driven by luxury and EV demand, while Asia-Pacific emerges as the fastest-growing arena. Logistical hubs near major maritime ports facilitate efficient import-export flows of critical auto parts and fully assembled units.
In-depth regional review of key markets
North America dominates through massive dealership networks and high vehicle-per-capita ratios, whereas Europe enforces strict emissions rules that accelerate EV dealer transitions. Meanwhile, Asia-Pacific thrives on rapid urbanization, boosting demand for both affordable passenger vehicles and commercial fleet options.
Strategic positioning of leading companies in the sector
Key participants such as Lithia Motors Inc, Group 1 Automotive Inc, and AutoZone Inc employ aggressive acquisition strategies and localized inventory optimization. O Reilly Automotive Inc and Advance Auto Parts Inc dominate the aftermarket segment through dense distribution networks and sophisticated B2B parts cataloging.
Porter's Five Forces analysis of the competitive environment
Supplier power remains moderate due to OEM reliance, while buyer power is high given transparent digital pricing models. The threat of new entrants is mitigated by steep capital requirements for physical showrooms, whereas substitute threats are low outside of urban public transit expansions.
SWOT analysis of the Motor Vehicle And Parts Dealers Market
Key strengths include entrenched customer loyalty and established financing channels, offset by weaknesses in inventory carrying costs. Opportunities abound in used EV certification and digital aftermarket sales, while macroeconomic inflation and stringent regulatory compliance represent persistent threats.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material sourcing for steel, rubber, and lithium, flowing through OEM manufacturing, centralized logistics, and regional distribution hubs. It culminates in dealership delivery, consumer financing, and post-sale maintenance services supported by aftermarket parts suppliers.
Investment insights and strategic recommendations
Investors should target dealerships and aftermarket platforms heavily investing in EV infrastructure and digital CRM tools. Companies like Sonic Automotive Inc and Asbury Automotive Group Inc present compelling value as they scale omnichannel capabilities to capture high-margin service revenue.
Conclusion and key takeaways for industry stakeholders
Reaching 10571.48 Billion by 2033 underscores the sector's long-term viability. Stakeholders must embrace digital transformation and adapt to shifting powertrain dynamics—particularly electric and luxury segments—to maintain competitive advantage in a consolidating global marketplace.
Research methodology for baseline estimations
Our estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with dealership executives, and secondary macroeconomic indicators. We cross-reference customs data from major logistics ports with quarterly financial disclosures from publicly traded industry participants.
Scope of the report and coverage parameters
This report covers global revenue performance for the Motor Vehicle And Parts Dealers Market from 2026 to 2033. Analysis is segmented by vehicle types, parts categories, ownership models, and store formats, excluding unverified private peer-to-peer transactions and unrecorded grey-market vehicle imports.
Recent developments in the automotive retail ecosystem
Recent strategic moves include major dealership acquisitions by Penske Automotive Group Inc and aggressive retail expansion by aftermarket giants like AutoZone Inc. Partnerships between traditional auto groups and EV startups are reshaping showroom floors to accommodate direct-to-consumer delivery models.