What is the market overview and industry significance of the K-12 Makerspace Materials Market?
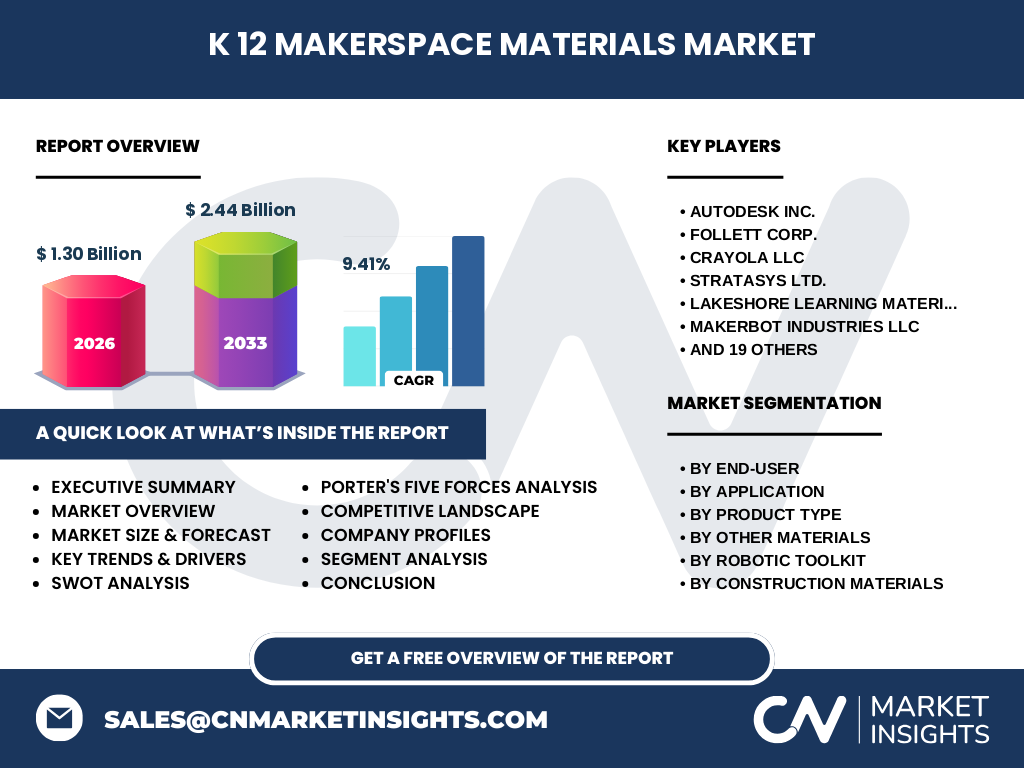
Our analysis indicates that the K-12 Makerspace Materials Market represents a pivotal sector valued at $1.30 Billion in 2026, driving hands-on STEM and STEAM education. Educational institutions increasingly rely on specialized raw materials and technical kits to foster early engineering competencies, transforming traditional classrooms into dynamic innovation hubs.
Key market drivers, restraints, challenges, and opportunities shaping K-12 Makerspace Materials Market
Growth is propelled by expanding government grants for experiential learning, though strict safety compliance for materials like 3D printer filament and wood sheets acts as a budgetary restraint. Opportunities abound for suppliers addressing supply chain bottlenecks at major logistics ports.
The Shift Toward Immersive STEM Curricula
The market is witnessing a profound shift toward cross-disciplinary project-based learning. Educational software and apps combined with tangible Robotic Toolkits are replacing rote memorization, heavily favored by institutions procuring advanced STEM Kits.
How did the pandemic affect K-12 Makerspace Materials Market and the recovery trajectory?
COVID-19 caused severe distribution halts and school closures, but federal stimulus funds catalyzed a robust post-pandemic rebound. Institutions rapidly invested in individual-use Art and Craft Materials and portable electronics to support hybrid learning models.
Competitive Benchmarking and Market Concentration
The K-12 Makerspace Materials Market industry trends reveal a fragmented landscape dominated by specialized innovators. Firms like Sphero Inc. and Makeblock Co. Ltd. lead in robotics, while legacy players maintain strong holds on traditional construction supplies.
Executive Summary of the K-12 Makerspace Materials Market
Driven by robust demand for experiential learning, the K-12 Makerspace Materials Market market size is projected to surge from $1.30 Billion in 2026 to $2.44 Billion by 2033, expanding at a notable CAGR of 9.41%.
Market Forecast and Revenue Projections from 2027 to 2033
Our proprietary financial models project steady expansion through 2033, achieving the forecasted 9.41% CAGR. This trajectory is underpinned by sustained capital expenditure in school infrastructure upgrades and mandatory technology integration policies.
Segmentation Analysis by End-User, Application, and Product Type
The market segments by end-user into Classroom, Library, Cafeteria, Office, and Other End-Users. Applications span Pr?-?r?m?r? S?h??l, Pr?m?r? S?h??l, Middle S?h??l, and High S?h??l, while products range from Robotic Toolkits to Construction and Art materials.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on local educational budgets and federal tech mandates. North America retains the largest revenue share due to early adoption of maker-centered curricula, closely followed by rapidly modernizing districts across Europe and Asia-Pacific.
In-Depth Regional Review of Educational Infrastructure
North American school districts prioritize versatile Building Blocks (LEGO, K'NEX) and advanced Arduino and Raspberry Pi Kits. Meanwhile, European markets focus heavily on sustainable Textiles and Sewing Kits and localized safety-certified crafting supplies.
Strategic Positioning of Leading Companies
Key market participants leverage distinct product portfolios to capture institutional budgets. Autodesk Inc. and Stratasys Ltd. dominate digital design and fabrication, whereas Lakeshore Learning Materials and Crayola LLC excel in foundational art and craft supplies.
Porter's Five Forces Analysis of Competitive Dynamics
Supplier power remains moderate due to specialized raw material requirements for Microcontrollers and Circuit Boards. Conversely, buyer power is high as school districts leverage centralized competitive bidding processes to procure STEM Kits.
SWOT Analysis of the Makerspace Materials Sector
Key strengths lie in high product engagement and proven educational outcomes. Weaknesses involve high initial setup costs for complex Robotics Kits, while threats include shifting regulatory compliance standards for classroom chemical and thermal tools.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction for Wood, Plastics, and Metal Sheets, progressing through precision manufacturing of Motors and Sensors, and culminating in direct-to-school distribution networks managed by specialized educational vendors.
Investment Insights and High-Potential Areas
Investors should target emerging niches within Educational Software and Apps and modular STEM Kits. These segments offer high gross margins and scalable software-as-a-service or recurring material-refill revenue models.
Conclusion and Strategic Takeaways
The K-12 Makerspace Materials Market analysis confirms a lucrative, fast-growing ecosystem. Stakeholders must align product roadmaps with institutional demands for safety, durability, and seamless curriculum integration to capture long-term market share.
Research Methodology for Baseline Estimates
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary qualitative interviews with school procurement directors, and secondary macroeconomic indicators tracking global educational spending.
Scope of the Report and Coverage Parameters
This report covers global revenue performance, volume shipments, and strategic vendor profiling from 2026 to 2033. Limitations include localized procurement policy variances and private funding data opacity within specific rural school districts.
Recent Developments and Strategic Industry Moves
Recent market dynamism is highlighted by aggressive product launches from Ozobot and Sphero Inc., alongside strategic distribution partnerships between major educational publishers and hardware manufacturers to streamline school procurement cycles.