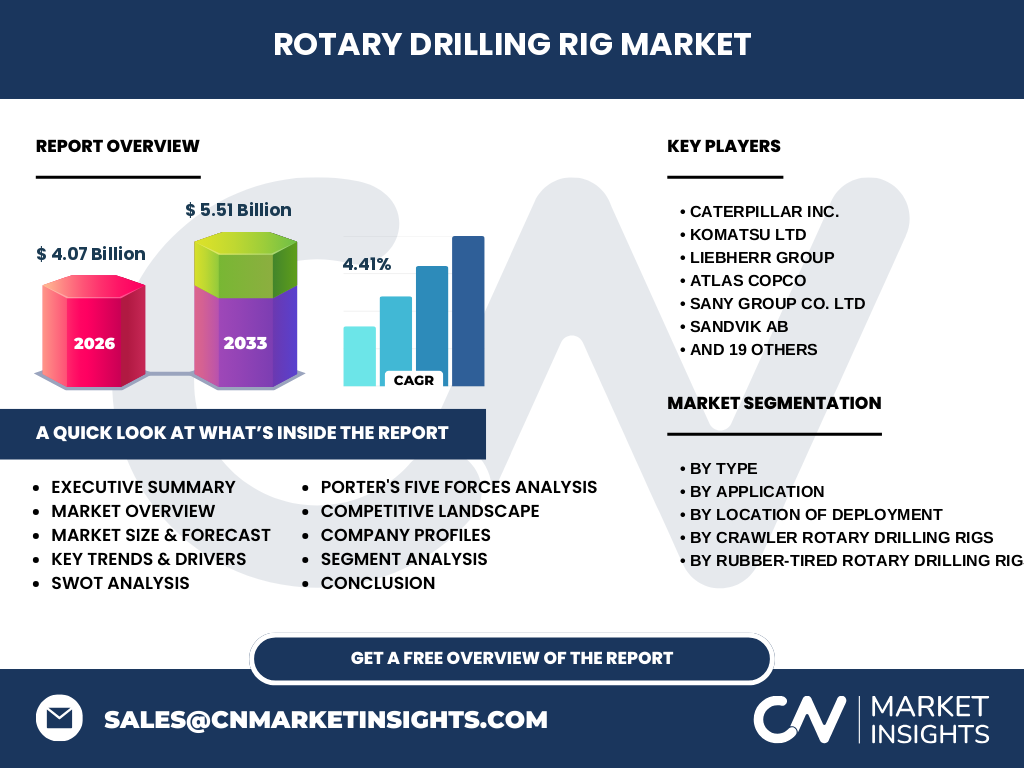
Market overview of the Rotary Drilling Rig Market
Our analysis indicates that the Rotary Drilling Rig Market size stands at $4.07 Billion in 2026. This sector encompasses heavy machinery deployed for deep-hole drilling in natural resource extraction, civil infrastructure, and geotechnical engineering. The industry relies heavily on steel alloy raw materials and hydraulic components, operating under stringent OSHA and ISO environmental and safety regulations globally.
Structural Growth Drivers and Market Constraints
The data suggests that robust infrastructure investments and escalating mineral exploration propel growth. However, high capital expenditure requirements for equipment like Crawler Rotary Drilling Rigs pose significant barriers. Supply chain bottlenecks for specialty engines and strict Tier 4 final emissions standards enforced by the EPA act as prominent operational constraints.
Emerging industry trends in the Rotary Drilling Rig Market
Industry trends highlight a rapid pivot toward automation and telematics integration. Manufacturers are incorporating remote diagnostics and electric-hybrid powertrains to lower carbon footprints. This shift heavily favors market leaders capable of embedding IoT sensors into heavy-duty chassis designs to optimize drilling torque and reduce rig downtime.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions, port congestion at major hubs like Shanghai and Rotterdam, and temporary project suspensions. Our research shows that the market rebounded sharply as governments fast-tracked shovel-ready infrastructure projects, stabilizing procurement timelines for both onshore and offshore deployment sites.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high concentration among multinational conglomerates. Key participants such as Caterpillar Inc., Komatsu Ltd, and SANY Group Co. Ltd leverage extensive global distribution networks and aftermarket service agreements. Competitors continuously vie for market share through targeted acquisitions of specialized attachment manufacturers.
Executive summary of the Rotary Drilling Rig Market
Our comprehensive report reveals a thriving sector projected to expand from $4.07 Billion in 2026 to $5.51 Billion by 2033, achieving a steady CAGR of 4.41%. Growth is primarily driven by surging global energy demands and underground mining expansion, requiring technological modernization across legacy equipment fleets.
Market forecast from 2027 to 2033
The data suggests the market will scale from $5.51 Billion over the forecast period, maintaining a compound annual growth rate of 4.41%. Sustained demand for metals, rare earth elements, and expanding urban transit tunneling projects will anchor this steady revenue expansion through 2033.
Segmentation analysis by type, application, and location
Segmentation is categorized by type (Crawler and Rubber-Tired Rotary Drilling Rigs), application (Oil and Gas, Mining, Other), and location of deployment (Onshore and Offshore). Crawler Rotary Drilling Rigs dominate rough terrain operations, while Rubber-Tired Rotary Drilling Rigs offer superior mobility for urban infrastructure projects.
Geographic distribution and regional market performance
Regional performance varies based on localized mining activity and infrastructure spending. The Asia-Pacific region commands the largest market share due to aggressive urbanization in China and India, while North America and Europe emphasize strict emissions compliance and equipment technological upgrades over sheer unit volume expansion.
In-depth regional review of key deployment zones
North America remains a mature market heavily influenced by EPA regulations and shale oil extraction economics. Conversely, Latin America and Africa present high-growth opportunities driven by greenfield mining projects, though logistics hurdles and local content laws require specialized market entry strategies for foreign OEMs.
Company profiles and strategic positioning
Industry stalwarts like Liebherr Group and Sandvik AB focus on premium, high-capacity engineering for harsh environments. Meanwhile, firms like Zoomlion Heavy Industry Science & Technology Co. Ltd and Bauer AG capture cost-sensitive segments by offering versatile hydraulic crawler configurations backed by aggressive financing terms.
Porter's Five Forces analysis of the industry
Rivalry is intense among established OEMs, driving continuous R&D into automated drilling systems. Supplier power is moderate, concentrated in specialized hydraulic pumps and steel alloys. Buyer power is high due to bulk purchasing by large mining conglomerates, while the threat of substitution remains low given the specialized physics of rotary drilling.
SWOT analysis of the Rotary Drilling Rig Market
Strengths include advanced automation and robust equipment durability. Weaknesses involve high initial capital outlays. Opportunities lie in electrification and autonomous deep-mining operations. Threats encompass volatile raw material pricing for steel and tightening geopolitical trade restrictions affecting global supply chains.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material suppliers providing structural steel and electronic microchips. Component manufacturers fabricate hydraulic pumps and masts, which OEMs like Atlas Copco and Vermeer Manufacturing assemble. Final distribution occurs through authorized dealers to mining operators and civil contractors.
Investment insights and high-potential areas
Our analysis indicates that capital should flow toward electric-hybrid rig development and autonomous drilling software startups. Investors should target OEMs expanding their aftermarket service revenues, as parts maintenance provides a resilient cash flow buffer against macroeconomic cyclicality.
Conclusion and key takeaways
The Rotary Drilling Rig Market industry trends confirm a transition toward smarter, cleaner, and more efficient extraction equipment. With a solid 4.41% CAGR leading to $5.51 Billion by 2033, technological innovation remains the definitive differentiator for market survival.
Research methodology and data triangulation
Baseline estimates are synthesized through meticulous triangulation combining customs trade registry data, primary executive interviews with industry stakeholders at companies like Schramm Inc. and Dando Drilling International Ltd., and secondary macroeconomic indicators regarding global mining capital expenditures.
Scope of the report and coverage parameters
This report covers global market sizing and forecasts from 2027 to 2033, analyzing Crawler and Rubber-Tired variants across Onshore and Offshore environments. Excluded from this scope are shallow auger drills and manual core sampling equipment utilized exclusively in agricultural landscaping.
Recent developments, partnerships, and strategic moves
Recent market activity is characterized by strategic joint ventures focused on hydrogen-powered prototype testing and digital fleet management platforms. Major players are actively acquiring software firms to enhance remote monitoring capabilities, ensuring compliance with shifting international safety and carbon-reduction mandates.