What is the scope and industry significance of the Job Simulation Market?
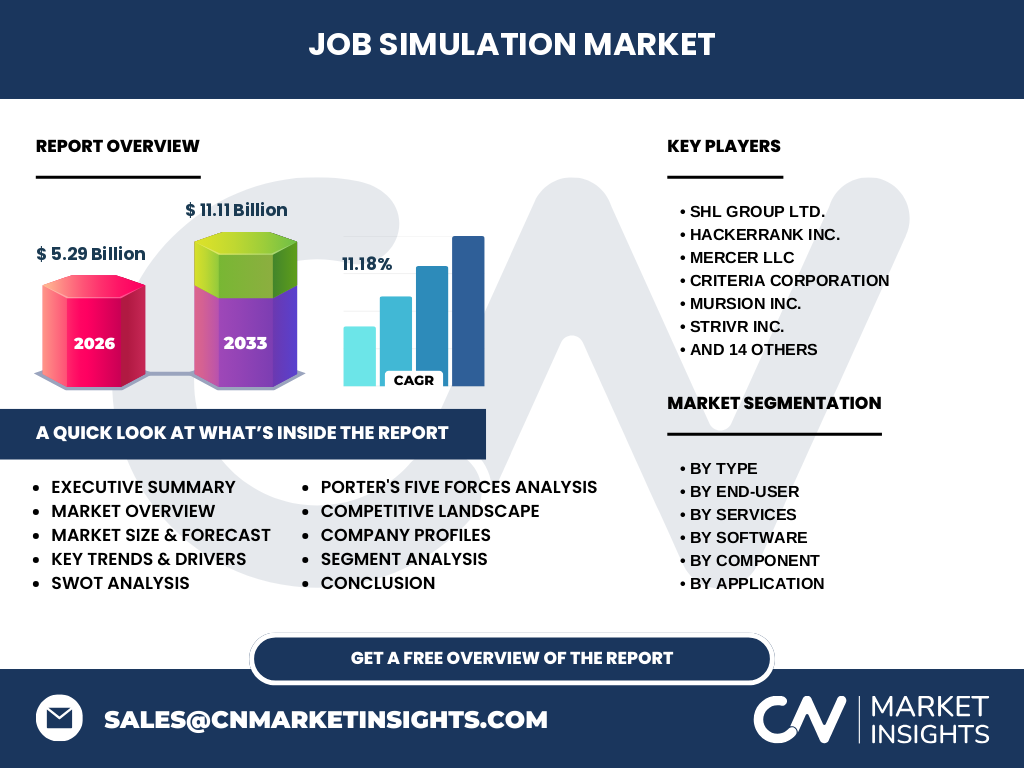
Our analysis indicates that the Job Simulation Market reached a valuation of 5.29 Billion in 2026. This sector encompasses immersive pre-employment testing, interactive behavioral evaluations, and technical screening tools that replace traditional static resumes with practical, real-world task evaluations.
Structural Growth Drivers and Market Restraints
The market is propelled by the urgent need for bias-free hiring and remote workforce evaluation. Key restraints include high initial setup costs for advanced virtual reality hardware and strict data privacy regulations like GDPR impacting cross-border cloud deployment.
Emerging trends and growth patterns in the Job Simulation Market
A definitive shift toward AI-driven Behavioral Assessments and immersive Technical Simulations is redefining candidate evaluation. Employers increasingly demand hyper-personalized scenario testing to accurately predict on-the-job performance and reduce costly early-stage employee turnover.
How did the COVID-19 pandemic impact the Job Simulation Market?
The pandemic served as an unprecedented catalyst, forcing remote-first recruitment protocols globally. Organizations rushed to adopt cloud-based Simulation Software and Assessment Software, permanently altering the hiring landscape and establishing a rapid post-pandemic recovery trajectory.
Competitive Benchmarking and Industry Concentration
The market features a mix of established HR giants and agile innovators. Leaders like SHL Group Ltd., HackerRank Inc., and Strivr Inc. dominate through proprietary algorithm integration, comprehensive platform ecosystems, and strategic enterprise-level contracts.
Executive Summary: Key Findings
Driven by a robust 11.18% CAGR from 2027 to 2033, the market is transitioning from a niche recruitment novelty into an essential enterprise software category. Companies failing to adopt interactive testing risk severe talent acquisition bottlenecks.
Market Forecast Projections Through 2033
Our research forecasts the global market to surge from 2027 to reach an impressive 11.11 Billion by 2033. This expansion is fueled by widespread enterprise digitization and increasing investments in automated talent intelligence platforms.
Comprehensive Segmentation Analysis
The sector breaks down across multiple vectors: By Type (Cognitive Assessments, Behavioral Assessments, Technical Simulations, Situational Judgment Tests); By End-User (BFSI, Healthcare, Retail, IT & Telecom, Education); By Services; By Software; and By Deployment Mode (On-Premises, Cloud-Based, Hybrid).
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading due to early tech adoption and stringent compliance standards. Meanwhile, Asia-Pacific exhibits the fastest adoption rates, driven by expanding IT sectors in India and fintech booms across Southeast Asia.
In-Depth Regional Review and Localized Constraints
North America benefits from mature venture capital ecosystems supporting innovators like Mursion Inc. and Criteria Corporation. Conversely, European markets prioritize strict labor laws and works council regulations, favoring privacy-compliant assessment vendors.
Strategic Positioning of Leading Company Profiles
Firms such as Mercer LLC, Talview Inc., and Codility Ltd. leverage advanced analytics to capture market share. Specialized vendors like Zenarate Inc. and Capsim Management Simulations Inc. focus on vertical-specific immersive roleplays and executive training.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate-to-high due to numerous SaaS alternatives. Threat of new entrants is mitigated by high R&D costs required for realistic simulation engines, while competitive rivalry is fierce among established talent assessment tech vendors.
SWOT Analysis of the Job Simulation Sector
Key strengths include high predictive hiring validity; weaknesses involve integration friction with legacy HRIS systems. Opportunities lie in emerging generative AI scenarios, while threats include rising cybersecurity regulations and algorithmic bias litigation risks.
Value Chain Analysis and Industry Structure
The value flow initiates with raw psychometric research and AI foundational models, moving through software developers like TestGorilla B.V. and Vervoe Inc., and culminating in enterprise HR deployment across global corporations and recruitment agencies.
Investment Insights and High-Potential Areas
Strategic investors should target cloud-native hybrid simulation platforms and sector-specific testing tools in healthcare and banking. High-potential returns cluster around firms integrating automated soft-skill scoring via natural language processing.
Conclusion and Strategic Takeaways
The data confirms that job simulations are no longer optional HR supplements. Market participants must prioritize seamless cloud integration, rigorous data privacy compliance, and advanced AI scoring capabilities to capture future enterprise budgets.
Rigorous Research Methodology for Baseline Estimates
Our baseline figures are triangulated using a rigorous mix of primary stakeholder interviews with HR executives, secondary macroeconomic indicators, regulatory filings from public entities like SHL and HackerRank, and comprehensive trade registry datasets.
Scope of the Report and Coverage Parameters
This report covers global revenue trends from 2026 base years through 2033 forecasts. Limitations include exclusion of informal offline assessment practices and localized un-registered recruitment consultancies operating outside major digital frameworks.
Recent Industry Developments and Strategic Moves
Recent milestones include strategic partnerships between tech innovators like Arctic Shores Ltd. and enterprise HR platforms, alongside product launches from Plum.io Inc. and Canditech Inc. aimed at expanding automated role-specific testing capabilities.