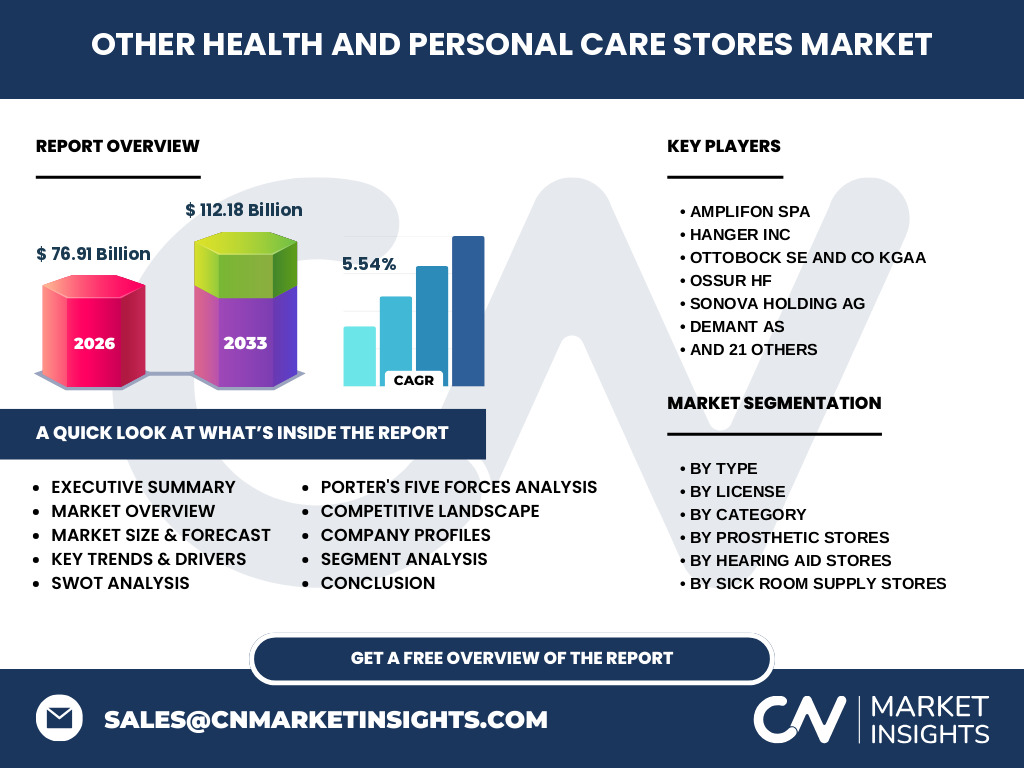
What is the market overview and scope of the Other Health and Personal Care Stores Market?
Our analysis indicates that the Other Health and Personal Care Stores Market valued at 76.91 Billion in 2026, encompasses specialized retail outlets providing vital medical devices, mobility solutions, and home care supplies, operating under strict FDA and regional healthcare compliance.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is propelled by an aging global demographic requiring home-based medical equipment, though supply chain bottlenecks for raw metals in prosthetic accessories and complex reimbursement policies from CMS pose ongoing margin restraints for independent operators.
Emerging trends and growth patterns in the industry
The shift toward direct-to-consumer digital storefronts by major players like SpinLife and MedMart is revolutionizing personal mobility scooter dealers, allowing patients to configure electric scooters online with virtual clinical consultations.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated telehealth integration and demand for oxygen equipment and hospital beds, forcing sick room supply stores to pivot toward contactless home delivery while navigating acute global logistics disruptions.
Competitive Benchmarking and Market Concentration
The landscape features a blend of specialized giants like Ottobock SE And Co KGaA in limb prosthetics and retail networks like Amplifon SpA, driving high market concentration through strategic acquisitions of local hearing aid clinics.
Executive Summary of the Other Health and Personal Care Stores Market
Our research forecasts the market to expand from 76.91 Billion in 2026 to 112.18 Billion by 2033 at a steady 5.54% CAGR, underpinned by rising chronic disease prevalence and technological advancements in wearable health retail.
Market Forecast from 2027 to 2033
Driven by robust demand for rehabilitation aids and diagnostic equipment, the market trajectory projects sustained acceleration, achieving 112.18 Billion by 2033 as advanced retail models capture shifting consumer healthcare preferences.
Segmentation Analysis by Type, License, and Category
The sector segments across Convalescent Supply Stores, Prosthetic Stores, Hearing Aid Stores, Sick Room Supply Stores, Medical Equipment And Supplies Stores, and Personal Mobility Scooter Dealers, partitioned further by branded licenses and premium versus mass product tiers.
Regional market analysis and geographic distribution
North America dominates the retail landscape due to favorable Medicare reimbursement frameworks, while the Asia-Pacific region demonstrates the fastest growth velocity driven by expanding urban healthcare infrastructure and rising disposable incomes.
In-depth Regional Review
European markets exhibit stringent CE mark compliance demands for surgical instruments and mobility aids, whereas North American operations leverage robust digital distribution channels managed by entities like Numotion and Hoveround Corporation.
Company Profiles and Strategic Positioning
Industry leaders such as Sonova Holding AG, Demant AS, and Hanger Inc leverage vertical integration, combining proprietary manufacturing of hearing aids and limb prosthetics with direct retail storefront dominance to capture high-margin segments.
Porter's Five Forces Analysis
Supplier power remains moderate due to specialized manufacturing dependencies, while competitive rivalry is intense among retail giants like Specsavers Group Ltd and Boots Hearingcare Parent Entity vying for consumer loyalty in urban retail spaces.
SWOT Analysis of the Industry
Key strengths lie in specialized clinical expertise and robust recurring product demand, whereas weaknesses involve high inventory holding costs for complex medical furniture; opportunities thrive in e-commerce expansion, offset by strict regulatory compliance threats.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with raw material sourcing for wound care products and hearing aid accessories, passing through specialized manufacturers, distributors, and specialized retail storefronts before reaching end-users in home or clinical care settings.
Investment Insights and High-Potential Areas
High-potential capital allocation targets digital platforms specializing in home care products and mobility accessories, where direct-to-consumer models yield superior margins compared to traditional brick-and-mortar operations.
Conclusion and Key Takeaways
The Other Health and Personal Care Stores Market presents resilient growth fueled by demographic shifts, rewarding firms that successfully integrate omnichannel retail strategies with stringent clinical compliance across diagnostic equipment and convalescent supplies.
Research Methodology for Baseline Estimates
Our data triangulation methodology combines primary stakeholder interviews with retail executives, secondary macroeconomic indicators from health ministries, and proprietary trade registry data to establish rigorous baseline valuations for 2026.
Scope of the Report and Coverage Parameters
This report covers global retail operations within specialized health stores, excluding general pharmacy chains, focusing strictly on specialized channels distributing items like hospital beds, electric scooters, and prosthetic accessories from 2027 through 2033.
Recent Developments in the Sector
Recent strategic moves include major retail partnerships by Starkey Hearing Technologies Retail and Miracle Ear Parent Operations, alongside product launches of advanced AI-integrated hearing aids expanding retail revenue streams.