What is the market overview and industry significance of the Isotropic Graphite Market?
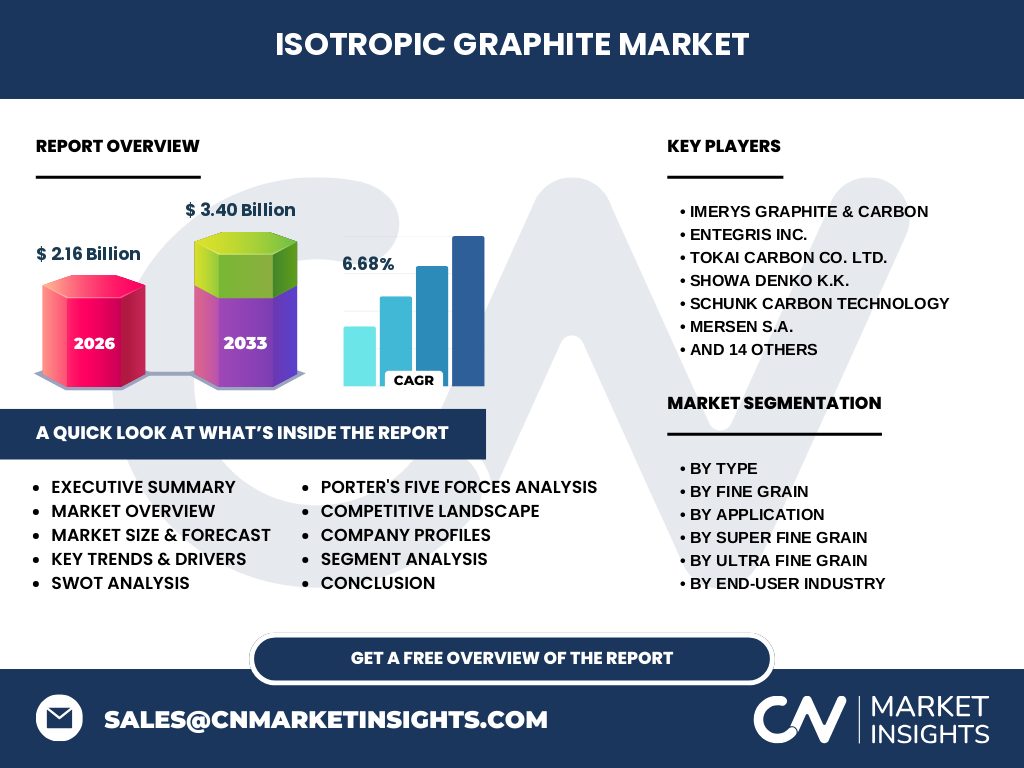
Our analysis indicates that the Isotropic Graphite Market represents a critical pillar in advanced manufacturing, valued at 2.16 Billion in 2026. This specialized material exhibits uniform physical properties in all directions, making it indispensable for high-temperature furnaces, electrical discharge machining (EDM), and semiconductor crystal growth where anisotropic materials would fail under thermal stress.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market thrives on surging demand from photovoltaic and semiconductor manufacturing sectors. However, strict export controls on raw petroleum coke and high graphitization energy costs act as primary restraints. Despite these hurdles, burgeoning opportunities in lithium-ion battery anode production and 5D telecommunications infrastructure components provide lucrative avenues for key industry participants like Tokai Carbon Co. Ltd. and Mersen S.A.
Emerging Trends and Growth Patterns in Isotropic Graphite
The shift toward ultra-high purity grades for extreme semiconductor applications is reshaping production methodologies. Leading players are heavily investing in advanced purification techniques to reduce ash content below 5 ppm, aligning directly with tightening quality mandates from tier-one wafer fabrication facilities across East Asia and North America.
How did COVID-19 impact the Isotropic Graphite Market and drive its recovery trajectory?
Pandemic-induced supply chain disruptions temporarily halted automotive and aerospace manufacturing lines, causing a dip in demand for specialty molds and heating elements. Recovery has been swift and robust, propelled by aggressive global stimulus packages directed at green energy transitions and localized semiconductor supply chain reshoring.
Competitive Benchmarking and Market Concentration
The global landscape features moderate consolidation, dominated by established conglomerates such as SGL Carbon, Imerys Graphite & Carbon, and Entegris Inc. These industry leaders leverage proprietary Isostatic pressing technologies and vertically integrated supply chains to maintain pricing power and secure long-term supply agreements with multinational OEMs.
Executive Summary of the Isotropic Graphite Industry
Our comprehensive research confirms robust health for the sector, projecting market expansion from 2.16 Billion in 2026 to 3.40 Billion by 2033 at a steady CAGR of 6.68%. Accelerated adoption in solar photovoltaic crucibles and nuclear graphite components underpins this positive long-term trajectory.
Market Forecast and Valuation Trajectory (2027 to 2033)
Driven by compounding industrial demand across electronics and green energy verticals, the market is poised to scale from 2027 through 2033, achieving a projected valuation of 3.40 Billion by the end of the forecast period. This trajectory reflects a resilient 6.68% CAGR supported by heavy capital expenditures in regional semiconductor foundries.
Segmentation Analysis: Breaking Down Types, Applications, and End-Users
Segmentation spans Fine Grain (utilized in electrodes, crucibles, molds, and heating elements), Super Fine Grain (targeting EDM electrodes and semiconductor components), and Ultra Fine Grain (critical for nuclear applications and aerospace). End-user demand is heavily concentrated across manufacturing, electronics, and chemicals sectors, supported by direct sales and extensive distributor networks.
Geographic Distribution and Regional Performance
Regional performance highlights Asia-Pacific as the undisputed manufacturing powerhouse, driven by massive semiconductor and solar wafer fabrication clusters in Taiwan, South Korea, and China. Meanwhile, North America and Europe maintain steady growth anchored by aerospace defense requirements and strict environmental compliance mandates governing chemical processing equipment.
In-Depth Regional Review of High-Growth Zones
In East Asia, localized manufacturing incentives and rapid EV battery adoption have accelerated demand for specialized sintering dies and high-precision molds. Concurrently, European markets focus on sustainability, favoring energy-efficient graphitization processes implemented by regional specialists like Graphite Materials GmbH and Loesche GmbH.
Strategic Positioning of Leading Market Participants
Major industry stakeholders employ distinct competitive strategies. Companies like Showa Denko K.K. and SCHUNK Carbon Technology focus on customized engineering solutions for harsh chemical environments, while Fangda Carbon New Material Co. Ltd. and Graphite India Limited capitalize on scale economies in bulk electrode and crucible production.
Porter's Five Forces Analysis of Competitive Pressures
Industry rivalry remains intense among established global players, while the threat of new entrants is remarkably low due to the immense capital expenditure required for high-pressure isostatic presses. Bargaining power of buyers is moderate, as technical switching costs are high for mission-critical semiconductor and aerospace components.
SWOT Analysis of the Isotropic Graphite Sector
Key strengths include exceptional thermal shock resistance and electrical conductivity. Weaknesses involve high production costs and energy-intensive manufacturing cycles. Opportunities lie in next-generation nuclear fusion reactors and silicon carbide (SiC) semiconductor tooling, while primary threats stem from raw material price volatility and geopolitical trade restrictions on high-grade needle coke.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with petroleum coke and coal tar pitch sourcing, transitioning through milling, mixing, isostatic molding, and multi-stage graphitization. Value is heavily captured during the high-precision machining and purification phases executed by specialized tier-1 processors before the finished components reach end-users in metallurgy and electronics.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward ultra-fine grain graphitization technologies and closed-loop recycling infrastructure. Firms specializing in semiconductor-grade purification and customized high-temperature furnace components offer superior margin expansion potential within the burgeoning Isotropic Graphite Market.
Conclusion and Strategic Takeaways
The Isotropic Graphite Market offers compelling growth underpinned by strict performance demands in electronics and green energy. Long-term success favors technologically agile firms capable of scaling ultra-fine grain production while navigating complex global supply chain dynamics and environmental regulations.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-suite executives, customs trade registries, and secondary macroeconomic indicators from industrial associations. This multi-layered approach ensures precise sizing of the Isotropic Graphite Market industry trends and regional revenue pools.
Scope and Parameters of the Market Report
This report encompasses a comprehensive global assessment of the Isotropic Graphite Market, evaluating historical data alongside forecasts through 2033. Analysis covers all primary grades, applications, and regional sub-markets, excluding unverified artisanal producers and non-graphite carbon allotropes to maintain strict data integrity.
Recent Corporate Developments and Strategic Partnerships
Recent market activity features strategic capacity expansions and joint ventures aimed at securing green-energy supply chains. Notable moves include proprietary product launches by Nippon Carbon Co. Ltd. and technological partnerships forged by SEC Carbon Ltd. to enhance energy efficiency in graphitization furnaces, reflecting broader industry commitment to sustainable manufacturing.