What is the scope and industry significance of the Coil Coatings Market?
The Coil Coatings Market is valued at 6.74 Billion in 2026, serving as a cornerstone for pre-painted metal solutions across architecture, appliance manufacturing, and transport sectors. Our analysis indicates that continuous roll coating technologies eliminate post-painting inefficiencies, providing critical corrosion resistance for steel and aluminum substrates handled by global fabricators.
Structural Growth Drivers and Market Restraints
Urbanization and lightweighting mandates act as primary catalysts for the Coil Coatings Market industry trends. Conversely, strict volatile organic compound limits enforced by the EPA and EU REACH regulations create cost pressures. Fluoropolymer and Siliconized Polyester lines help mitigate environmental friction, though raw material volatility in titanium dioxide and resin intermediates threatens margins.
Emerging Trends in Coil Coatings Market Application
The shift toward self-healing, solar-reflective PVDF formulations defines contemporary Coil Coatings Market analysis. Architects increasingly specify high-performance Polyvinylidene Difluoride and Aliphatic Polyurethane to meet net-zero building codes, favoring premium finishes that reduce urban heat island effects while lowering long-term lifecycle maintenance expenses for commercial facades.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain bottlenecks temporarily disrupted the Coil Coatings Market market size expansion, particularly through automotive shutdowns and container shortages at major ports. However, aggressive post-pandemic infrastructure stimulus and surging residential construction rebounded demand rapidly, pushing the sector toward a robust 7.44% CAGR trajectory through 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high among tier-one chemical innovators. PPG Industries Inc., Akzo Nobel N.V., and The Sherwin-Williams Company dominate through proprietary resin synthesis and global supply footprints. Competitors like Beckers Group and Jotun Group leverage localized manufacturing hubs to outpace rivals in customized architectural and appliance coatings.
Executive Summary of the Coil Coatings Market Report
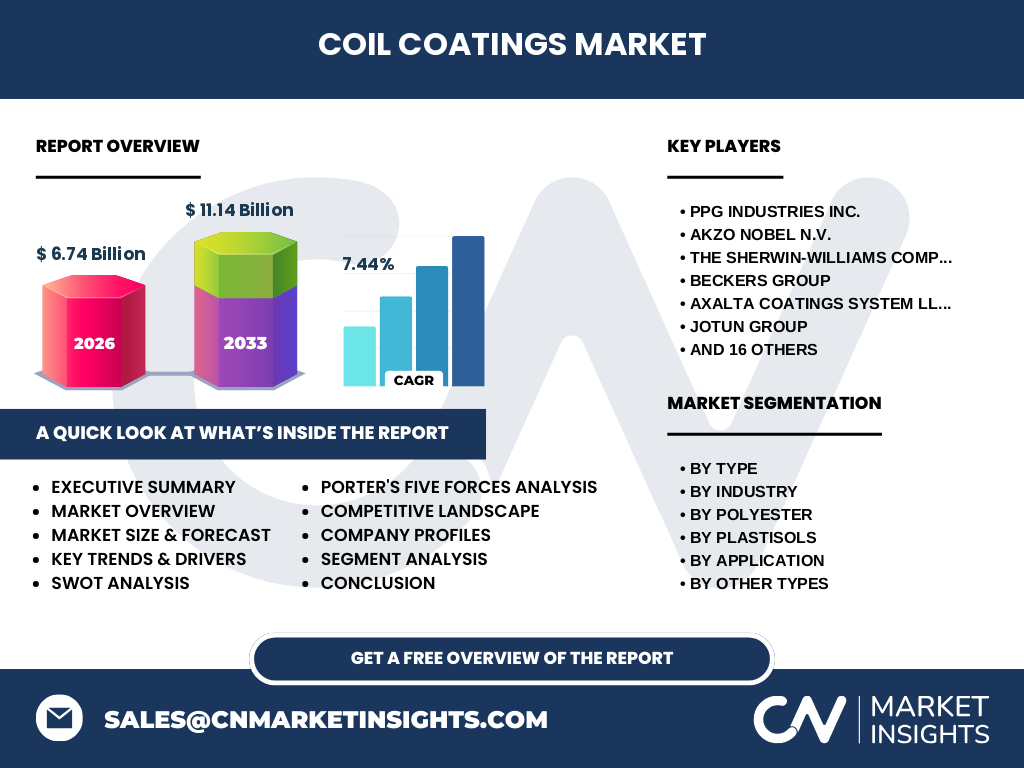
Our research forecasts the Coil Coatings Market to surge from 6.74 Billion in 2026 to 11.14 Billion by 2033 at a 7.44% CAGR. Construction end-uses and advanced Fluoropolymer chemistries anchor this expansion, rewarding agile manufacturers investing in sustainable, low-emission application lines across high-growth developing economies.
Long-Term Market Forecast from 2027 to 2033
Driven by industrial automation and green building mandates, the Coil Coatings Market is projected to reach 11.14 Billion by 2033. This expansion reflects a steady 7.44% CAGR from the 2026 baseline of 6.74 Billion, heavily fueled by infrastructure buildouts in APAC and accelerated adoption of high-durability coil-coated aluminum panels.
Comprehensive Segmentation Analysis
The Coil Coatings Market categorizes by Type (Polyester, Fluoropolymer, Siliconized Polyester, Polyvinylidene Difluoride (PVDF), Polyurethane (PU), Plastisols, Other Types), Industry (Construction, Automotive, Industrial And Domestic Appliances, Other Industries), and Application (Steel, Aluminum). Construction applications on Steel substrates currently command the largest revenue share.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Asia-Pacific leading volume consumption due to massive manufacturing bases in China and India. North America and Europe prioritize advanced technological specifications, centering investments on strict environmental compliances and high-performance architectural PVDF and Aliphatic Polyurethane systems.
In-Depth Regional Review and Localized Market Constraints
In North America and Europe, stringent environmental compliance mandates limit traditional solvent-borne formulations, accelerating adoption of high-solids and waterborne coil alternatives. Meanwhile, rapid industrialization across emerging Asian economies prioritizes cost-effective Standard Polyester and PVC Plastisols to support booming commercial real estate developments.
Company Profiles and Strategic Positioning
Industry leaders like Axalta Coatings System LLC, Hempel A/S, and Nippon Paint Holdings Co. Ltd. focus on R&D-driven product differentiation. Regional specialists such as Kansai Nerolac Paints Limited, Asian Paints Limited, and NOROO Coil Coatings Co. Ltd. exploit local distribution networks to capture localized demand in domestic appliance manufacturing.
Porter's Five Forces Analysis of the Industry
Bargaining power of raw material suppliers remains moderate-to-high, directly impacting resin and pigment pricing for coil formulators. Threat of substitutes is low given the unique corrosion-resistant benefits of coil coating. Competitive rivalry is fierce among global giants, driving continuous innovation in energy-saving curing technologies and extended warranty offerings.
SWOT Analysis of the Coil Coatings Market
Strengths lie in exceptional durability and cost efficiency over spray painting. Weaknesses include high initial capital outlays for coil lines. Opportunities emerge in renewable energy infrastructure, specifically solar panel frames. Threats involve severe regulatory crackdowns on fluoropolymer chemistry and persistent raw material cost inflation.
Value Chain Analysis from Raw Materials to End-Users
The value chain starts with petrochemical refiners supplying base resins and pigments, moving through specialized paint formulators like Teknos Group Oy and Shalimar Paints Limited. These formulators supply coil coaters who apply finishes to continuous metal strips before final fabrication for end-use markets.
Strategic Investment Insights and High-Potential Areas
Investors should target acquisitions of regional coil coating formulators possessing proprietary low-bake technology. Companies specializing in eco-friendly High-Performance Polyester and sustainable Polyurethane (PU) formulations represent prime targets as OEMs race to fulfill corporate carbon-neutrality pledges.
Conclusion and Strategic Takeaways
The Coil Coatings Market presents robust expansion potential, scaling to 11.14 Billion by 2033. Success hinges on balancing stringent ecological regulations with superior product performance. Firms investing in advanced resin chemistry and sustainable manufacturing will capture disproportionate market share.
Research Methodology and Baseline Triangulation
Our analysis is built by triangulating secondary macroeconomic indicators, trade registry data from chemical associations, and primary stakeholder interviews with executives from Brillux GmbH & Co. KG, Titan Coatings Inc., and Jiangsu Lanling Chemical Group Co. Ltd. This multi-tier methodology ensures highly accurate market sizing.
Scope and Limitations of the Research Report
This report covers global coil coating dynamics from 2026 to 2033, analyzing segmentation across types, industries, and applications. Limitations include unforeseen geopolitical trade shifts and sudden macroeconomic shocks that could alter raw material supply chains and regional pricing structures.
Recent Industry Developments and Strategic Moves
Strategic partnerships and eco-friendly product launches dominate recent developments. Major players like Tata Paints Limited, Berger Paints India Limited, and SK Kaken Co. Ltd. have recently introduced ultra-weatherable coil coatings designed to reduce building energy consumption, aligning directly with evolving global sustainability targets.