Market overview and structural significance of the Perimeter Security Market
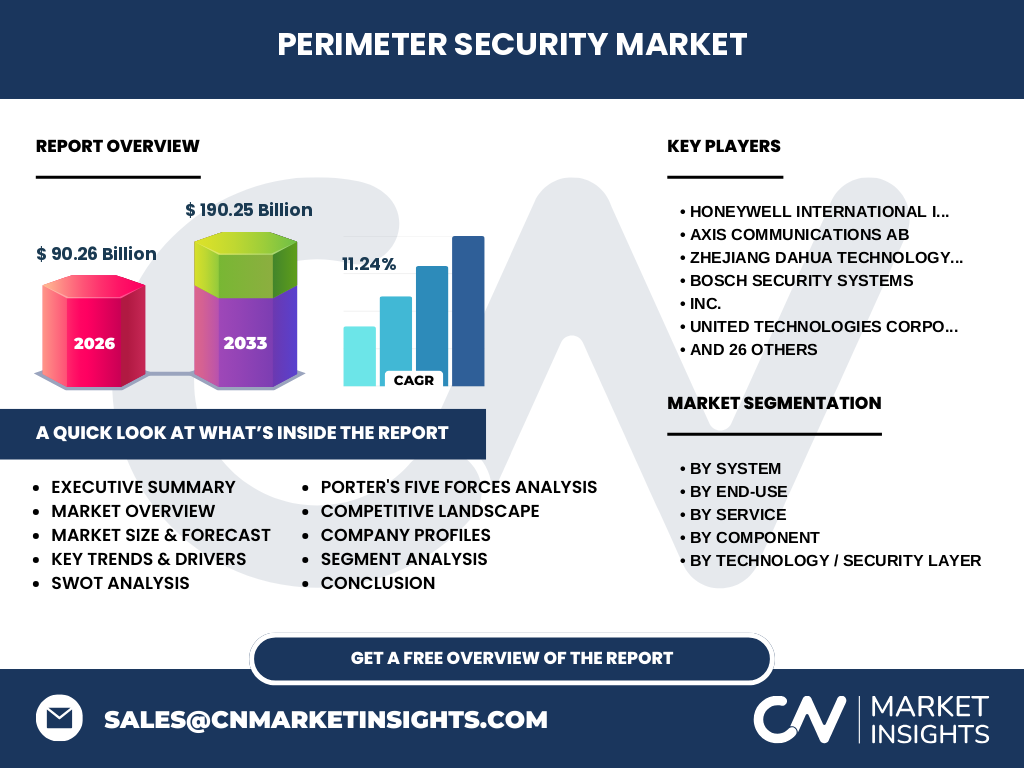
Our analysis indicates the Perimeter Security Market reaches $90.26 Billion in 2026, driven by rising geopolitical tensions and critical infrastructure vulnerabilities. This sector encompasses physical barriers, electronic sensors, and integrated software platforms designed to safeguard high-risk zones, airports, and utilities against unauthorized intrusion.
What core forces shape market drivers, restraints, and opportunities?
Growth is propelled by strict regulatory mandates from bodies like the TSA and NERC CIP, alongside technological convergence in AI-driven video analytics. However, high initial deployment costs and frequent false alarms in harsh weather act as major restraints. Opportunities lie in upgrading legacy analog systems with intelligent fiber-optic sensing.
Emerging trends and transformation patterns across the industry
The shift toward Integrated / Smart Perimeter Security Systems is accelerating rapidly. Facilities increasingly demand unified platforms combining Video Surveillance Systems with automated access control. Companies like Genetec Inc. and Milestone Systems A/S lead this software-centric trend, replacing siloed hardware with centralized, cloud-managed security intelligence.
How did COVID-19 impact recovery trajectories and supply chains?
The pandemic severely disrupted global semiconductor supply chains, delaying the deployment of electronic Perimeter Monitoring Sensors. Yet, it ultimately accelerated touchless access control and remote monitoring demands. The market rebounded strongly as enterprises prioritized automated, unmanned boundary protection to reduce on-site guard dependency.
Competitive Benchmarking and Market Concentration
The landscape features a mix of multinational conglomerates and specialized sensing pioneers. Industry leaders like Honeywell International Inc., Johnson Controls International PLC, and Bosch Security Systems leverage vast distribution networks, while niche innovators like Southwest Microwave Inc. and Fiber Sensys Inc. dominate specialized high-security radar and fiber-optic niches.
Executive Summary of the Perimeter Security Market
The Perimeter Security Market is poised for explosive expansion, scaling from $90.26 Billion in 2026 to $190.25 Billion by 2033 at a robust 11.24% CAGR. Driven by escalating security threats, the market demands advanced electronic layers, smart sensors, and comprehensive service integration across military, transportation, and commercial domains.
Long-term market forecast from 2027 to 2033
Projected to expand at a steady 11.24% CAGR, the market will surge from 2027 figures toward a valuation of $190.25 Billion by 2033. This acceleration reflects sustained enterprise spending on resilient boundary protection, driven by the imperative to secure supply chain hubs, seaports, and energy grids against sophisticated physical threats.
Detailed segmentation analysis by system, end-use, service, component, and technology
The market breaks down across several distinct vectors: By System includes Intrusion Detection Systems (IDS), Access Control, Video Surveillance, Barriers And Fencing, Alarms, and Monitoring Sensors. By End-Use covers Transportation, Commercial, Government, Military, Defense, and others. By Service spans Installation, Maintenance, Consulting, Monitoring, and Training. By Component splits into System and Service. By Technology highlights Physical, Electronic, and Integrated / Smart systems.
Geographic distribution and regional performance dynamics
Regional performance varies widely based on localized threat profiles and infrastructure spending. North America leads in technology adoption, heavily influenced by strict Department of Defense standards. Meanwhile, Asia-Pacific exhibits the fastest growth rate, fueled by massive urbanization, smart city initiatives, and port expansions across China and India.
In-depth regional review of high-growth territories
In North America, demand focuses heavily on integrated smart solutions for critical energy grids. In Europe, stringent GDPR regulations and critical infrastructure directives shape video surveillance deployments. The Middle East and Africa prioritize ruggedized military-grade barriers and radar intrusion detection to secure remote oil and gas extraction facilities.
Strategic positioning of leading industry players
Major conglomerates like United Technologies Corporation, Panasonic Corporation, and Hangzhou Hikvision Digital Technology Co. Ltd. compete through extensive product portfolios and global reach. Specialized firms such as Senstar Corporation and Optex Co. Ltd. carve out strong market share by focusing on proprietary laser, microwave, and fiber-optic detection technologies.
Porter's Five Forces analysis of the industry ecosystem
Bargaining power of buyers is moderate to high, as large enterprises demand customized, interoperable security suites. Threat of substitutes remains low due to the irreplaceable nature of physical and electronic perimeter defense. Competitive rivalry is fierce, pressuring margins and driving continuous R&D investment in AI-enabled false-alarm filtering.
SWOT evaluation of the global security landscape
Key Strengths include robust multi-layered detection capabilities and high switching costs. Weaknesses involve vulnerability to cyber-attacks on networked sensors. Opportunities emerge from smart city integrations and 5G-enabled wireless monitoring. Threats stem from severe supply chain bottlenecks for microprocessors and optical components.
Value chain analysis from raw material sourcing to end-user deployment
The value chain originates with raw material suppliers providing silicon, steel, and fiber optics. Component manufacturers and system integrators—such as Axis Communications AB and FLIR Systems Inc.—transform these materials into advanced cameras and sensors. Value is ultimately realized through specialized installation, monitoring, and maintenance services delivered to end-users.
Investment insights and high-potential growth pockets
Investors should target developers of AI-driven video analytics and edge-computing intrusion sensors, as these technologies significantly reduce operational expenditure for end-users. Furthermore, companies offering integrated cloud-monitoring services represent prime acquisition targets for major hardware manufacturers seeking recurring revenue models.
Conclusion and core takeaways for industry stakeholders
The Perimeter Security Market industry trends highlight an irreversible migration toward smart, integrated security layers. Achieving a projected $190.25 Billion by 2033, the sector rewards organizations that successfully combine rugged physical barriers with intelligent electronic sensors and predictive maintenance services.
Research methodology for baseline estimates and data triangulation
Our analysis is built upon rigorous data triangulation. We combine official trade registry data, macroeconomic indicators, and extensive primary interviews with Chief Security Officers, system integrators, and regulatory compliance officers across North America, Europe, and Asia-Pacific to ensure absolute accuracy of baseline valuations.
Scope of the report, coverage parameters, and limitations
This report evaluates the global Perimeter Security Market market size from 2026 to 2033, analyzing revenues across specified hardware, software, and service segments. Limitations include unforeseen geopolitical trade embargoes and sudden raw material price volatility that may temporarily influence localized installation growth rates.
Recent industry developments, product launches, and strategic partnerships
Recent market activities feature aggressive M&A strategies and technological alliances. Companies like Genetec Inc. and Johnson Controls International PLC have forged partnerships to integrate cloud-native access control with advanced thermal imaging, enabling automated threat detection for critical transport hubs and national borders.