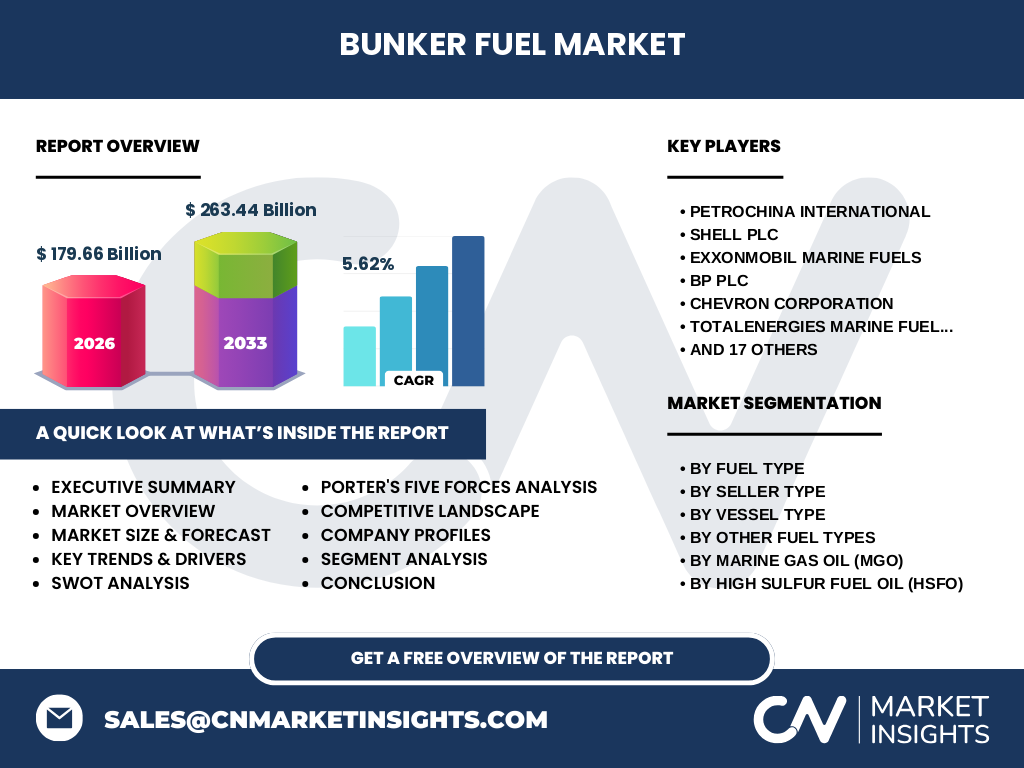
Market overview of the Bunker Fuel Market
The Bunker Fuel Market represents the vital lifeblood of global maritime logistics, encompassing the supply and distribution of marine propulsion fuels to commercial shipping fleets. Valued at 179.66 Billion in 2026, the sector underpins international trade by fueling bulk carriers, container ships, and tankers across major strategic waterways and bunkering hubs.
Key market drivers, restraints, challenges, and opportunities shaping Bunker Fuel Market
Stringent IMO sulfur cap regulations act as primary market shapers, accelerating the adoption of Very Low Sulfur Fuel Oil (VLSFO) and Liquefied Natural Gas (LNG). High feedstock volatility and refining bottlenecks present ongoing logistical hurdles, while burgeoning opportunities lie in developing renewable marine fuels and biogas LNG to meet decarbonization mandates.
Emerging trends and growth patterns in Bunker Fuel Market
The industry is witnessing an accelerated pivot toward alternative propulsion profiles, notably bio-LNG and synthetic LNG blends. Major ports are upgrading bunkering infrastructure to handle dual-fuel vessels, as shipping lines actively decarbonize operations to comply with tightening greenhouse gas reduction targets established by international maritime authorities.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions and suppressed global container volumes caused a sharp contraction in marine fuel demand during early 2020. However, the subsequent rebound in international trade catalyzed a robust market recovery, driving bunker demand upward and reinforcing the strategic resilience of key global bunkering ports.
Competitive landscape and strategic market dynamics
The competitive ecosystem features a mix of integrated supermajors and specialized independent traders. Companies like Shell plc, ExxonMobil Marine Fuels, and BP plc leverage refining scale and global supply networks, while independent leaders like World Fuel Services and Bunker Holding dominate physical distribution and logistical arbitrage.
Executive summary of the Bunker Fuel Market report
Our analysis indicates that the Bunker Fuel Market is poised for sustained expansion, reaching 263.44 Billion by 2033 from its 2026 baseline. Growing at a CAGR of 5.62%, the sector reflects a delicate balance between conventional high-sulfur residuals and cleaner marine distillates as environmental compliance dictates purchasing decisions.
Market forecast from 2027 to 2033
Driven by rising maritime freight volumes and stricter emissions corridors, the market will expand at a 5.62% CAGR throughout the forecast window. Valuation is projected to climb from 179.66 Billion in 2026 to peak at 263.44 Billion by 2033, rewarding operators who invest early in low-carbon bunkering infrastructure.
Segmentation analysis across fuel types, sellers, and vessels
The market bifurcates across multiple operational vectors: Fuel Types (HSFO, VLSFO, MGO, LNG, and renewables), Seller Types (Major Oil Companies, Large and Small Independent Distributors), and Vessel Types (Containers, Tankers, Bulk Carriers, and General Cargo). Each segment reacts uniquely to shifting regional refining yields and freight rate fluctuations.
Regional market analysis and geographic performance
Asia-Pacific dominates global bunkering volume, anchored by mega-ports like Singapore and Zhoushan. Meanwhile, European markets exhibit the strictest regulatory enforcement, accelerating regional demand for Ultra-Low Sulfur Marine Diesel Oil and synthetic LNG solutions as local carbon pricing mechanisms take effect.
In-depth regional review of key bunkering hubs
The Middle East remains a powerhouse for high-capacity blending and residual fuel supply, centered around the Fujairah Oil Terminal. Concurrently, North American ports experience steady demand growth driven by rigorous Emission Control Areas (ECAs), forcing local fleet operators toward VLSFO and distillate-heavy blends.
Company profiles and strategic positioning of leading players
Industry leaders maintain distinct strategic moats: PetroChina International and Unipec dominate Asian supply security, whereas TotalEnergies Marine Fuels and Chevron Corporation focus on expanding global LNG bunkering footprints. Independent giants like Vitol Group and Gunvor Group utilize nimble trading desks to capitalize on regional price spreads.
Porter's Five Forces analysis of the bunker industry
Bargaining power of buyers is moderately high due to transparent spot pricing and numerous independent suppliers. Threat of substitutes is intensifying via emerging wind-assist technologies and green ammonia, while industry rivalry remains fierce among major oil companies and global physical traders vying for port exclusivity.
SWOT analysis of the global bunker fuel sector
Key strengths include deeply entrenched maritime logistics networks and essential global trade utility. Weaknesses center on high carbon intensity and refining exposure. Opportunities emerge in renewable marine fuels, while threats involve unpredictable geopolitical shocks and tightening international emissions penalties.
Value chain analysis from raw materials to end-users
The value chain originates with upstream crude oil extraction and complex refinery processing into residual and distillate fractions. Midstream logistics involve dedicated bunker barges and terminal storage facilities (such as Fujairah Oil Terminal), culminating downstream in physical delivery to container ships and bulk carriers.
Investment insights and high-potential areas
Capital deployment should target dual-fuel supply infrastructure and the commercial scaling of biogas LNG. Investors will find lucrative entry points in partnering with independent distributors who possess proprietary physical barge networks across high-traffic Asian and Middle Eastern shipping lanes.
Conclusion and key takeaways for market stakeholders
The transition toward cleaner propulsion is no longer optional; it is the core determinant of market survival. With the market reaching 263.44 Billion by 2033, stakeholders must align supply portfolios with environmental regulations to capture expanding margins in low-sulfur and alternative fuel categories.
Research methodology and data triangulation
Baseline estimates are meticulously triangulated by cross-referencing port authority throughput statistics, trade registry manifests, and primary stakeholder interviews with bunkering executives. This is synthesized alongside secondary macroeconomic indicators and refinery capacity reports to ensure econometric validity.
Scope of the report and coverage parameters
This report covers global bunkering operations from 2026 through 2033, evaluating commercial shipping segments including containers, tankers, and bulk carriers. Geographical scopes span key global marine hubs across Asia, Europe, the Middle East, and the Americas, excluding domestic inland waterway vessels.
Recent developments in company announcements and partnerships
Recent market activity highlights aggressive joint ventures in bunkering infrastructure, with firms like Smit Lamnalco and Bunker Holding expanding their physical asset fleets to support dual-fuel LNG bunkering vessels. Major oil companies continue securing long-term offtake agreements for renewable marine fuels to future-proof their supply portfolios.