What is the Edutainment Market overview, scope, and industry significance?
Our analysis indicates that the Edutainment Market represents a dynamic convergence of educational pedagogy and immersive entertainment. Valued at 10.56 Billion in 2026, this sector bridges cognitive development with experiential learning. Regulatory frameworks from bodies like the U.S. Department of Education and regional cultural ministries increasingly validate these structured play environments. Industry participants like KidZania and Merlin Entertainments deliver high-value experiential nodes that transform traditional learning paradigms into quantifiable economic output.
Key market drivers, restraints, challenges, and opportunities shaping the Edutainment Market
Growth is propelled by rising disposable incomes and parental demand for experiential cognitive development. However, high capital expenditure for robust physical footprints and stringent safety mandates from organizations like ASTM International act as primary restraints. Operational logistics for mega-facilities exceeding 40,000 sq. ft. present complex facility management hurdles. Strategic opportunities lie in deploying proprietary augmented reality integrations to capture digitally native demographics across global metropolitan hubs.
Emerging trends and growth patterns in the Edutainment Market
The sector is witnessing a definitive shift toward hybrid physical-digital experiences. Educational institutions increasingly partner with interactive spaces like the Exploratorium and Science Museum Group to supplement formal STEM curricula. Our research highlights that immersive environments utilizing spatial computing are outperforming legacy static exhibits, driving higher visitor retention and increased ancillary spending on merchandise and food and beverage services.
COVID-19 impact analysis and recovery trajectory
The pandemic introduced severe operational disruptions, forcing prolonged closures across physical experiential centers globally. Cash flow compression compelled operators to fast-track digital adaptations, including virtual tours and home-delivery activity kits from brands like Crayola Experience LLC. The post-pandemic recovery trajectory exhibits a robust V-shaped rebound, driven by pent-up consumer demand for out-of-home family experiences and targeted government stimulus supporting cultural tourism infrastructure.
Competitive landscape, major players, market concentration, and strategic dynamics
The Edutainment Market displays a moderately fragmented landscape featuring localized independent science centers alongside multinational leisure conglomerates. Key participants such as LEGOLAND Discovery Centres, Pororo Park, and Discovery Cube Foundation leverage strong intellectual property partnerships to drive brand loyalty. Strategic consolidation is accelerating as major players acquire niche interactive game developers to expand their digital-physical ecosystems and protect market share against emerging entrants.
Executive summary of key findings about the Edutainment Market
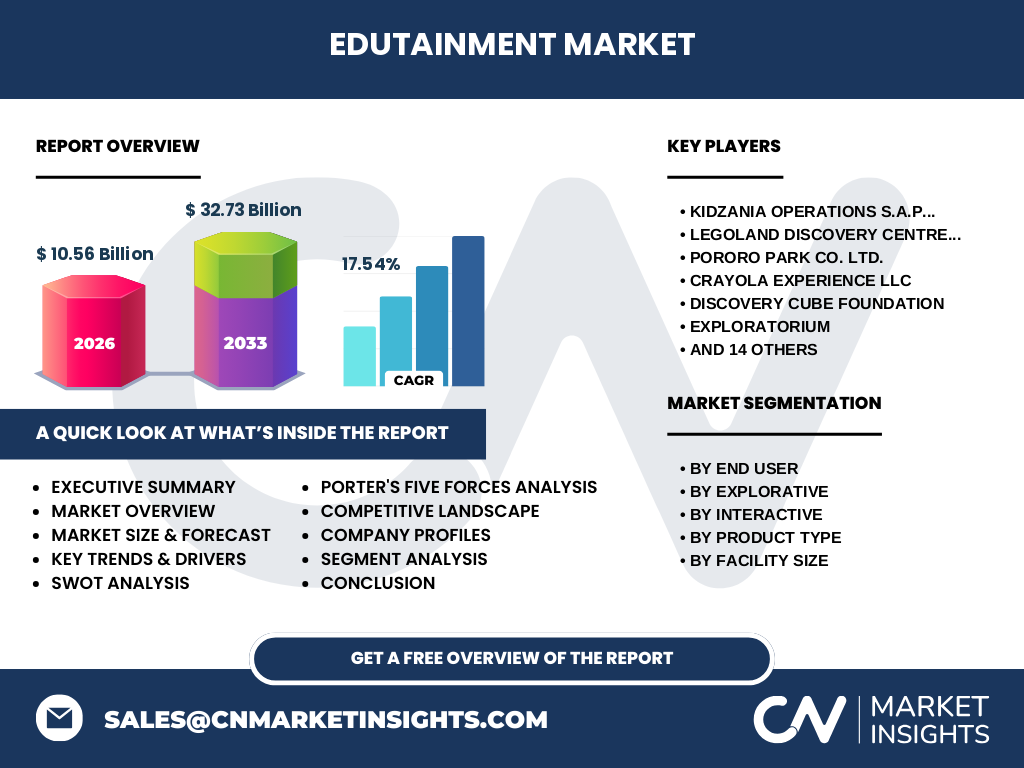
Our comprehensive research confirms a monumental valuation trajectory, projecting the market to surge from 10.56 Billion in 2026 to 32.73 Billion by 2033 at a robust CAGR of 17.54%. This expansion is anchored by surging demand for discovery-based learning tools and immersive technologies. Investors must prioritize assets demonstrating agile facility scaling and proprietary interactive software integration to capture outsized returns in this rapidly maturing industry.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Edutainment Market is poised for exponential expansion, scaling from the 2026 baseline of 10.56 Billion to reach 32.73 Billion by 2033. This performance reflects a sustained CAGR of 17.54% over the forecast window. Accelerated adoption of virtual reality experiences and large-scale interactive exhibits across emerging economies will serve as the primary catalysts for this multi-fold valuation increase.
Segmentation analysis by end user, explorative, interactive, product type, and facility size
Market segmentation reveals diverse operational dynamics. By End User, the sector serves Children and Teenagers. Explorative categories include Discovery-Based Learning Tools, Interactive Exhibits, and Immersive Environments. Interactive offerings feature Games, Simulations, and Virtual Reality Experiences spanning Product Types like Interactive and Explorative. Facility footprints range from 5,001 to 10,000 sq. ft., 10,001 to 20,000 sq. ft., 20,001 to 40,000 sq. ft., to mega-complexes exceeding 40,000 sq. ft.
Regional market analysis and geographic distribution
Geographic performance varies significantly due to localized educational spending, disposable income thresholds, and municipal zoning laws. North America currently maintains the highest revenue share, supported by institutional strongholds like the Boston Children’s Museum and Please Touch Museum. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by rapid urbanization, expanding middle-class demographics, and state-backed investments in science literacy centers like Science Centre Singapore and National Science Centre Delhi.
In-depth regional review of key markets
European markets, anchored by iconic institutions such as Cité des Sciences et de l’Industrie and Heureka The Finnish Science Centre, emphasize sustainability and pedagogical rigor aligned with European Union educational frameworks. In contrast, North American facilities prioritize high-throughput commercial entertainment models. Emerging markets in Latin America and the Middle East are leveraging mega-tourism hubs, integrating branded edutainment concepts into master-planned retail and entertainment real estate developments.
Company profiles and strategic positioning of leading entities
Industry leaders deploy distinct strategic moats to maintain competitive advantage. KidZania Operations specializes in hyper-realistic role-play micro-cities, while LEGOLAND Discovery Centres capitalize on globally recognized toy brand equity. Institutions like the Ontario Science Centre, Science World British Columbia, and Adventure Science Center rely on community trust and public-private funding models. Meanwhile, commercial ventures like WonderWorks Attractions and Papilonia Butterfly House focus on high-impact, location-based leisure entertainment.
Porter's Five Forces analysis of the Edutainment Market
Competitive rivalry is high among mid-tier operators, though proprietary IP ownership creates significant barriers to entry for new startups. Buyer power remains moderate, balanced by consumer appetite for novel educational experiences. Supplier power is low regarding raw construction materials but elevated for proprietary software developers. Threat of substitution is mitigated by the irreplaceable social and tactile value of physical edutainment complexes over purely digital alternatives.
SWOT analysis of the Edutainment Market
Strengths include high consumer demand for experiential learning and strong brand equity among major operators. Weaknesses involve high capital expenditure and vulnerability to public health disruptions. Opportunities emerge from expanding into Tier-2 and Tier-3 cities and integrating generative AI into interactive exhibits. Threats encompass regulatory tightening regarding child data privacy in digital games and macroeconomic inflationary pressures dampening discretionary family leisure budgets.
Value chain analysis from raw materials to end-users
The edutainment value chain originates with raw material suppliers providing structural steel, timber, and advanced semiconductors for hardware. Mid-stream entities comprise exhibit designers, software developers, and educational psychologists who engineer immersive environments and discovery tools. Downstream distribution involves facility operators, logistics coordinators, and marketing agencies delivering the final service directly to families, schools, and institutional end-users within specified square footage parameters.
Investment insights and strategic recommendations
Investors should target asset-light franchise models and scalable virtual reality experiences that bypass the heavy capital expenditures of traditional physical facilities. High-potential areas include hybrid venues sized between 10,001 and 20,000 sq. ft. that offer rapid turnaround on interactive exhibit rotations. Strategic partnerships with established science centers or EdTech software providers will yield superior risk-adjusted returns throughout the 2027 to 2033 forecast period.
Conclusion and key takeaways for stakeholders
The Edutainment Market represents a highly lucrative, fast-growing frontier at the intersection of leisure and education. Reaching a projected 32.73 Billion by 2033, the industry rewards operators who successfully blend physical immersion with digital interactivity. Stakeholders must navigate regulatory hurdles, facility management costs, and evolving consumer preferences to capture enduring market share in this expanding global ecosystem.
Research methodology used in compiling this report
Our baseline estimates are rigorously triangulated using a multi-tiered research methodology. This approach combines statutory financial filings from trade registries, primary qualitative interviews with C-suite executives across key companies, and secondary macroeconomic indicators from global trade organizations. Quantitative models cross-reference facility footfall metrics with consumer expenditure surveys to ensure high-fidelity market sizing and accurate growth projections.
Scope of the report and coverage parameters
This research report encompasses a comprehensive global assessment of the Edutainment Market across specified product types, explorative tools, interactive segments, and facility size categories. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East. Exclusions involve informal backyard play equipment and standard academic textbook publishing, maintaining a strict focus on out-of-home and immersive experiential learning facilities.
Recent developments, company announcements, and strategic moves
Recent industry momentum is defined by aggressive strategic partnerships and technological upgrades. Major operators are deploying capital toward next-generation virtual reality experiences and sustainable facility designs. Collaborations between regional science museums and digital content creators have surged, aimed at enhancing remote accessibility and expanding brand footprints beyond physical brick-and-mortar boundaries into omnichannel educational delivery models.