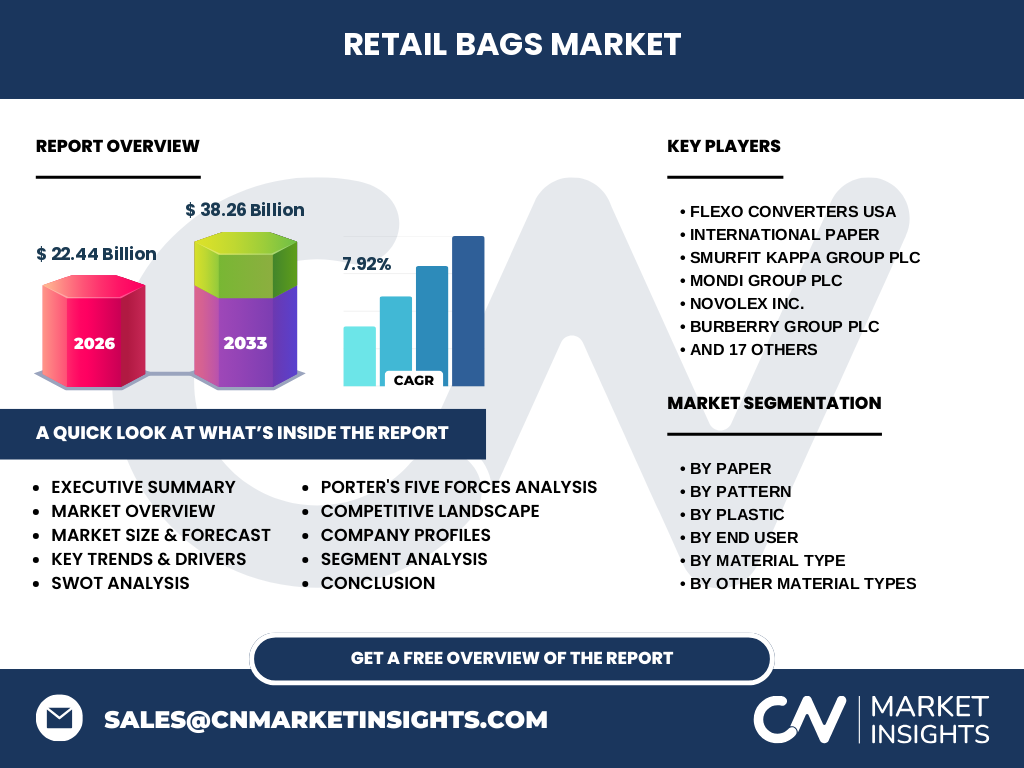
What is the Retail Bags Market?
Our analysis indicates that the Retail Bags Market encompasses the manufacturing and distribution of packaging solutions utilized across commercial sectors. Valued at USD 22.44 Billion in 2026, this industry is foundational for logistics and consumer engagement, spanning raw material processing from wood pulp to petroleum derivatives.
Key market drivers, restraints, challenges, and opportunities shaping Retail Bags Market
Growth is accelerated by e-commerce expansion, while strict municipal bans on single-use plastics act as primary restraints. Logistical hurdles involve raw material price volatility. Major opportunities lie in compostable substrates compliant with environmental standards set by bodies like the EPA and European Bioplastics.
Emerging trends and growth patterns in Retail Bags Market
The shift toward circular economy models defines current Retail Bags Market industry trends. Consumers demand traceable sourcing, pushing converters toward certified recycled paper and marine-degradable polymers, altering traditional supply chain pathways across major distribution hubs.
COVID-19 impact analysis — how the pandemic affected Retail Bags Market and the recovery trajectory
The pandemic caused severe supply chain bottlenecks for resin and kraft paper, followed by a surge in contactless grocery delivery. Post-pandemic recovery has institutionalized hygiene-focused packaging protocols while accelerating corporate sustainability mandates among leading retail chains.
Competitive benchmarking and strategic dynamics
The landscape features consolidated enterprises alongside agile converters. International Paper and Mondi Group plc leverage massive scale for paper integration, while specialists like Novolex Inc. focus on proprietary bio-resins to capture premium margins in restricted geographic zones.
Executive summary of the Retail Bags Market
Our Retail Bags Market analysis projects explosive expansion from USD 22.44 Billion in 2026 to USD 38.26 Billion by 2033 at a 7.92% CAGR. Regulatory pressures and consumer preferences for eco-friendly alternatives are fundamentally restructuring supplier portfolios worldwide.
Market forecast from 2027 to 2033
Driven by robust demand in emerging economies and stringent retail packaging laws, the market will scale from 2026 baselines to reach USD 38.26 Billion by 2033. This trajectory reflects a steady 7.92% CAGR, underpinned by heavy investments in automated paper-bag converting machinery.
Segmentation analysis across material and pattern categories
The market splits into Paper (Kraft, Recycled, Coated, With/Without Handles), Plastic (HDPE, LDPE, PP, Biodegradable, Reusable), and Other Materials (Cotton, Jute, Non-Woven, Hemp, Linen). Pattern variants include Textured, Printed, and Solid designs tailored to specific brand positioning strategies.
Regional market analysis and geographic performance
Geographic performance varies significantly due to localized legislative frameworks. North America and Europe lead in sustainable adoption driven by strict regulatory penalties, whereas Asia-Pacific demonstrates high-volume growth propelled by expanding organized retail and urban grocery sectors.
In-depth regional review
In Europe, EU packaging directives heavily penalize non-recyclable polymers, favoring paper giants like Smurfit Kappa Group plc. Meanwhile, North American markets balance high-throughput LDPE usage in warehousing with surging demand for locally manufactured kraft alternatives from firms like Atlantic Packaging.
Company profiles and strategic positioning
Industry leaders maintain distinct strategic moats. ProAmpac Intermediate Inc. and Coveris SA focus on flexible barrier innovations, whereas BioPak Pty Ltd. dominates compostable foodservice segments, aligning directly with strict commercial composting infrastructure developments.
Porter's Five Forces analysis for the sector
Bargaining power of suppliers is moderate due to consolidated pulp and resin producers. Threat of substitutes remains high from reusable canvas alternatives, while intense rivalry among established players like Antalis Group and Welton Bibby and Baron Limited compresses baseline margins.
SWOT analysis of the industry
Strengths include robust global distribution networks. Weaknesses involve vulnerability to cellulose and crude oil price fluctuations. Opportunities abound in closed-loop recycling partnerships, while threats stem from unpredictable trade tariffs and aggressive municipal plastic bans.
Value chain analysis from raw materials to end-users
Value flows from forestry harvesting and petrochemical refining to film extrusion and paper pulping. Converters such as Flexo Converters USA transform these inputs into finished goods before distribution via maritime ports to grocery stores and food service providers.
Investment insights and high-potential areas
Investors should target technological innovators pioneering enzymatic plastic degradation or automated handle-attachment machinery. Capital allocation toward localized recycling infrastructure offers high-yield potential as circular economy mandates tighten across major metropolitan markets.
Conclusion and key takeaways
The Retail Bags Market size of USD 22.44 Billion in 2026 sets the stage for a transformative expansion to USD 38.26 Billion by 2033. Agility in material science and strict regulatory compliance will dictate long-term market leadership through this 7.92% CAGR period.
Research methodology and data triangulation
Baseline estimates are synthesized by cross-referencing trade registry data, customs import-export logs, primary stakeholder interviews with executives at Rutan Poly Industries Inc. and Global-Pak Inc., and secondary macroeconomic indicators from global packaging federations.
Scope of the report and coverage parameters
This research evaluates global manufacturer shipments, volume metrics in metric tons, and revenue valuations across 2026 to 2033. Excluded from this scope are industrial bulk sacks and agricultural packaging, maintaining strict focus on retail-facing point-of-sale bag formats.
Recent developments in the corporate landscape
Recent strategic moves include Burberry Group plc transitioning entirely to certified sustainable luxury packaging, alongside joint ventures by El Dorado Packaging Inc. to expand automated recycled paper production capacity to meet surging retail demand.