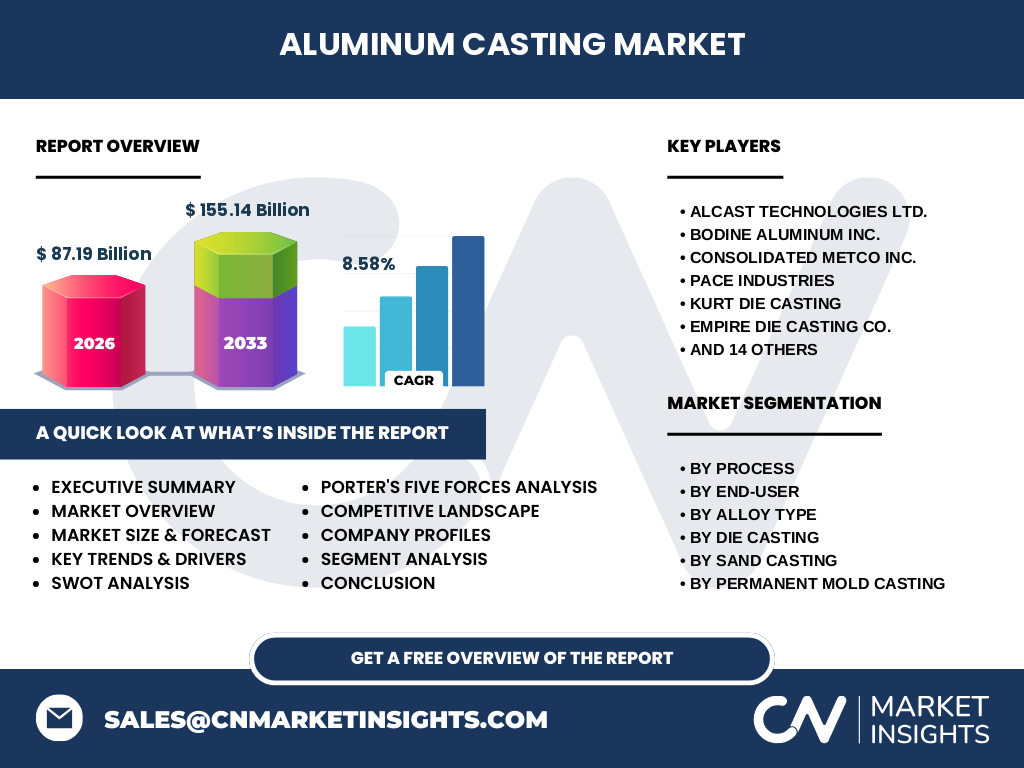
Market overview of the Aluminum Casting Market
The Aluminum Casting Market represents a critical manufacturing pillar encompassing specialized metallurgical processes that shape molten aluminum into complex industrial components. Based on our research, the market is valued at $87.19 Billion in 2026, driven by strict lightweighting mandates across transportation, industrial machinery, and construction sectors seeking high strength-to-weight ratios.
Structural Growth Drivers and Restraints in the Aluminum Casting Market
Our analysis indicates that structural growth is propelled by stringent environmental regulations from bodies like the EPA and EU mandating vehicular emissions reduction. However, volatile primary aluminum ingot pricing and energy-intensive foundry operations act as primary market restraints, challenging profit margins for foundational players like Pace Industries and Consolidated Metco Inc.
Emerging industry trends and growth patterns
The shift toward gigacasting and advanced vacuum-assisted die casting dominates current Aluminum Casting Market industry trends, enabling OEMs to consolidate dozens of stamped steel parts into single structural aluminum castings. This technological leap favors innovative foundries capable of producing large-format structural nodes for electric vehicle architectures.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and temporary automotive assembly shutdowns, severely impacting foundational demand in the Aluminum Casting Market. The recovery trajectory has been shaped by aggressive inventory restocking, localized nearshoring of supply chains, and surging demand for lightweight electric mobility infrastructure globally.
Competitive landscape and strategic market concentration
The competitive landscape exhibits moderate fragmentation characterized by specialized Tier-1 suppliers. Market leaders such as Endurance Technologies Limited and Bocar Group leverage proprietary alloy formulations and automated robotics, while regional players compete on localized metallurgical expertise and rapid turnaround for industrial OEMs.
Executive summary of key findings
Our comprehensive executive synthesis highlights that the Aluminum Casting Market is on an aggressive expansion path, scaling from $87.19 Billion in 2026 to reach $155.14 Billion by 2033 at a robust CAGR of 8.58%, driven primarily by automotive electrification and lightweighting imperatives.
Aluminum Casting Market forecast through 2033
The data suggests sustained acceleration, projecting the Aluminum Casting Market size to surge from its 2026 baseline of $87.19 Billion to an impressive $155.14 Billion by 2033. This expansion represents a steady compound annual growth rate (CAGR) of 8.58%, heavily underpinned by high-pressure die casting innovations.
Segmentation analysis across processes, alloys, and end-users
Market segmentation spans multiple critical dimensions: By Process (Die Casting, Sand Casting, Permanent Mold Casting), By Alloy Type (Aluminum-Silicon, Aluminum-Magnesium, Aluminum-Copper, Aluminum-Zinc), and By End-User (Transportation, Building and Construction, Industrial). Each segment plays a specialized role, with Al-Si alloys dominating powertrain and structural applications.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with Asia-Pacific leading due to dense automotive manufacturing hubs in China and India, while North America and Europe focus on advanced high-pressure die casting for electric vehicle platforms, adhering to stringent regional environmental compliance mandates.
In-depth regional review of high-growth territories
North American and European markets are experiencing transformative demand shifts fueled by local electric vehicle mandates. Foundries in these regions are modernizing equipment to process complex Aluminum-Magnesium alloys, while Asia-Pacific remains a high-volume powerhouse driven by cost-competitive raw material access and expansive industrial manufacturing ecosystems.
Company profiles and strategic positioning of leading players
Leading industry participants like Alcast Technologies Ltd., Bodine Aluminum Inc., and Empire Die Casting Co. maintain competitive moats through continuous R&D in thermal management and lightweight structural components, securing long-term supply agreements with major global automotive OEMs.
Porter's Five Forces analysis of the industry
Our analysis reveals moderate-to-high supplier power driven by primary aluminum commodity price fluctuations, alongside intense competitive rivalry among established foundries. However, buyer power is tempered by the high switching costs associated with precision-tooled automotive molds designed by specialists like Kurt Die Casting.
SWOT analysis of the Aluminum Casting Market
Key strengths include superior recyclability and lightweighting benefits; weaknesses involve high capital expenditure for foundry automation. Opportunities abound in electric vehicle structural components, while threats stem from potential material substitution by high-strength carbon composites and engineered plastics.
Value chain analysis from raw materials to end-users
The value chain flows from bauxite mining and primary aluminum smelting to secondary alloy refining, specialized foundry casting operations (utilized by firms like Haworth Castings), and final machining before delivery to transportation and construction end-users.
Investment insights and high-potential strategic areas
High-potential investment pockets center on automated vacuum die casting facilities and recycling infrastructure capable of processing scrap aluminum. Investors should target regional foundries capable of supplying complex structural battery housings for the rapidly expanding electric vehicle sector.
Conclusion and key takeaways
The Aluminum Casting Market analysis underscores a lucrative landscape characterized by a 8.58% CAGR pushing market value to $155.14 Billion by 2033. Foundries that successfully integrate advanced alloy technologies and sustainability measures will capture outsized market share.
Research methodology for baseline estimates
Our methodology triangulates data by synthesizing customs trade registries, primary stakeholder interviews with foundry executives, secondary macroeconomic indicators, and official reports from regulatory bodies such as the International Aluminum Institute to ensure maximum analytical accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics for the Aluminum Casting Market from 2026 to 2033, evaluating all major alloy formulations, casting techniques, and regional sub-markets, while excluding non-aluminum metal casting sectors such as ferrous iron and zinc die casting.
Recent developments in the industry
Recent strategic moves feature major investments in renewable energy-powered smelting and automated cell integration by global players like General Aluminum Mfg. Company and Regensburger Druckgusswerk Wolf GmbH, aimed at reducing carbon footprints while fulfilling massive electric vehicle structural component orders.